
Blog Details
Diskava. Beta. Kava
09Jun
MyKava Medical Plan vs Imana Afya Medical Plan: Which Medical Cover Is Right for You?
Choosing medical insurance is not only about finding the lowest premium. It is about understanding how the benefits are structured, how much protection each insured person receives, and whether the plan matches your family size, budget and healthcare needs.
At Imana Insurance Agency Kenya Ltd, clients can choose between two practical medical insurance options: the MyKava Medical Plan and the Imana Afya Medical Plan.
Both plans are designed to make medical insurance more accessible in Kenya, but they serve different needs.
The main difference is simple:
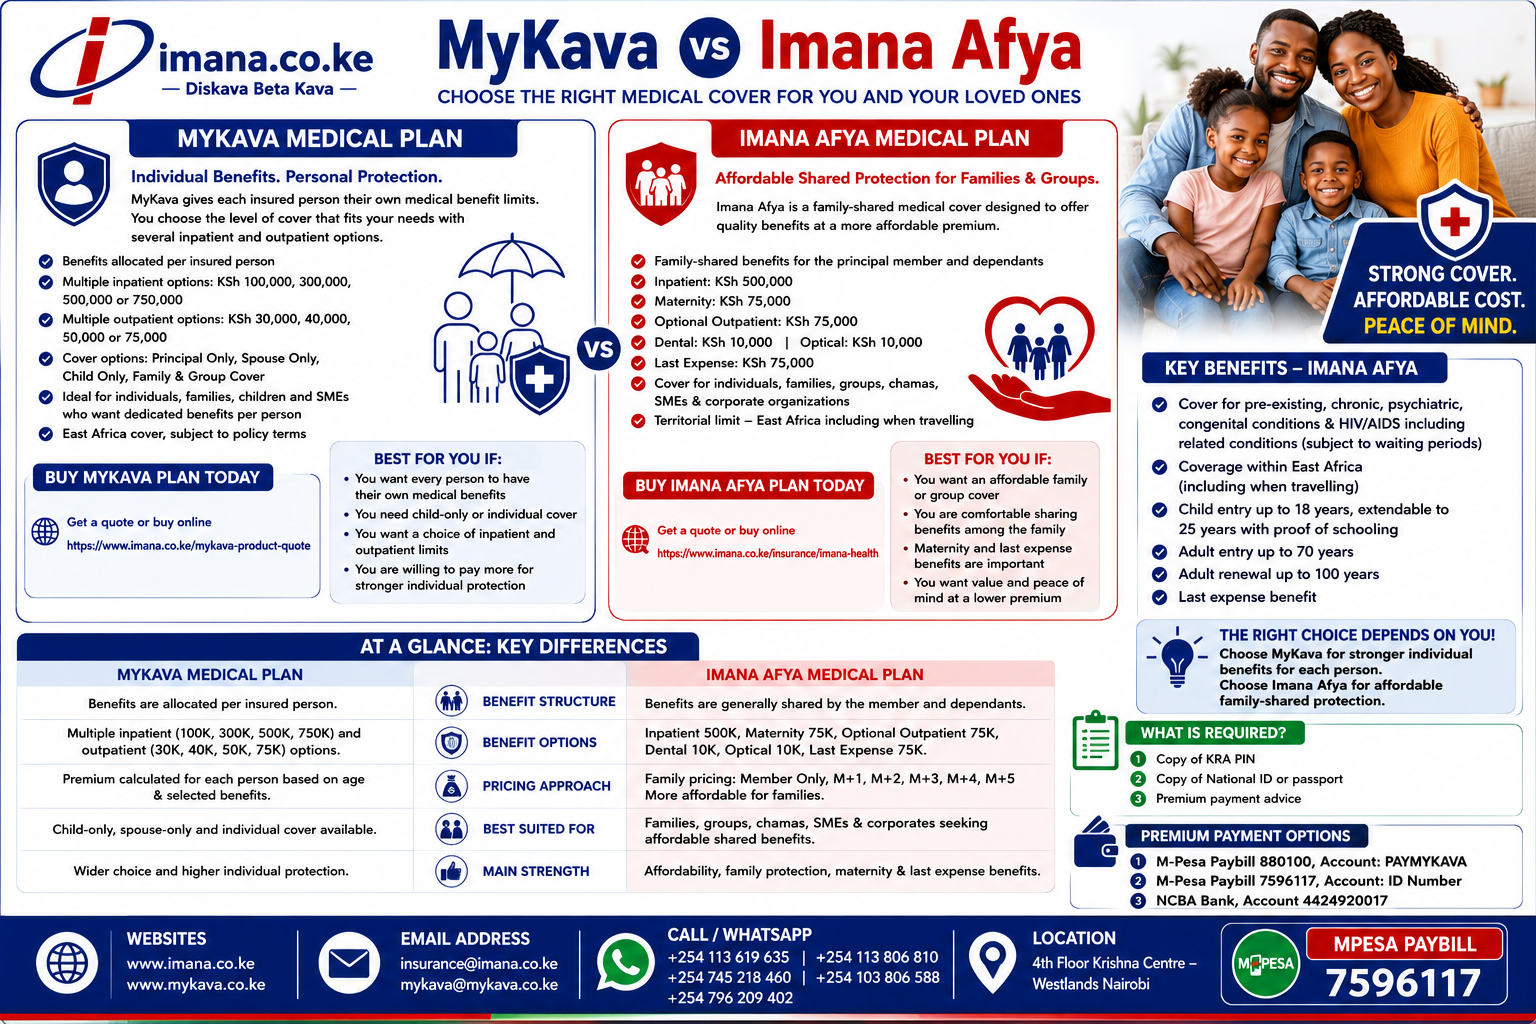
MyKava Medical Plan provides benefits per insured person, while Imana Afya Medical Plan offers affordable shared protection for families, groups and organizations.
What Is the MyKava Medical Plan?
The MyKava Medical Plan is designed for clients who want each insured person to have their own medical benefit limits.
This means that every person covered under the policy receives an individual allocation of medical benefits based on the selected plan.
MyKava offers several inpatient benefit options, including:
- KSh 100,000
- KSh 300,000
- KSh 500,000
- KSh 750,000
Outpatient options may include:
- KSh 30,000
- KSh 40,000
- KSh 50,000
- KSh 75,000
The plan can be structured for:
- Principal only
- Spouse only
- Child only
- Individual cover
- Family cover
- SME or group cover
Because the benefits are allocated per insured person, MyKava is suitable for families and individuals who want stronger personal protection and clearly defined medical limits for every member.
Who Should Choose the MyKava Medical Plan?
MyKava may be the better option when:
- You want every insured person to have their own benefit limits
- You need child-only or spouse-only medical cover
- You want several inpatient and outpatient options
- You prefer individual protection rather than shared family benefits
- You are willing to pay a higher premium for stronger personal cover
- You are an SME seeking clear medical limits for each employee
MyKava gives clients more flexibility when choosing benefit levels. The premium is generally determined by factors such as age, selected benefits and the number of people being covered.
What Is the Imana Afya Medical Plan?
Imana Afya is designed to provide affordable medical protection for individuals, families, groups, chamas, SMEs and corporate organizations.
The plan uses a shared-benefit structure, allowing the principal member and covered dependants to access benefits under one family arrangement.
Imana Afya includes:
- Inpatient cover of KSh 500,000
- Maternity benefit of KSh 75,000
- Optional outpatient cover of KSh 75,000
- Dental benefit of KSh 10,000
- Optical benefit of KSh 10,000
- Last expense benefit of KSh 75,000
The product also provides coverage within East Africa, including when travelling within the region. It may cover pre-existing, chronic, psychiatric, congenital conditions and HIV/AIDS-related conditions, subject to policy waiting periods.
Why Imana Afya Is Attractive to Families
The biggest strength of Imana Afya is affordability.
Instead of calculating a separate full premium for every family member, the plan is priced according to the number of dependants covered.
The available family structures include:
- Member only
- Member plus one
- Member plus two
- Member plus three
- Member plus four
- Member plus five
The inpatient and maternity package starts from KSh 8,230 per year for member-only cover.
The annual premium increases depending on the number of dependants included. This makes Imana Afya a practical option for households that want to cover several family members without paying separate premiums for each person.
Who Should Choose Imana Afya?
Imana Afya may be the right option when:
- You want an affordable family medical plan
- You are comfortable sharing benefits among family members
- Maternity protection is important to you
- You want last expense benefits included
- You need medical cover for a chama, group or SME
- You want coverage within East Africa
- Your priority is value and peace of mind at a lower premium
It is particularly suitable for families whose main goal is to secure essential medical protection while keeping the annual cost manageable.
The Main Difference Between MyKava and Imana Afya
The difference comes down to how medical benefits are allocated.
Under MyKava, each insured person receives their own selected benefit limits.
For example, when two people are each covered for KSh 500,000 inpatient, each person has access to their own KSh 500,000 limit.
Under Imana Afya, the available benefits are generally shared by the principal member and dependants covered under the family arrangement.
This makes MyKava stronger in terms of individual protection, while Imana Afya is more affordable for families and groups.
Which Plan Offers Better Value?
Both plans offer value, but in different ways.
MyKava offers better value to clients who want:
- Dedicated benefits for each insured person
- More inpatient and outpatient choices
- Individual, spouse-only or child-only cover
- Stronger protection per person
Imana Afya offers better value to clients who want:
- Lower family premiums
- Shared medical benefits
- Maternity and last expense cover
- Affordable protection for groups and organizations
There is no single plan that is automatically better for everyone. The right option depends on your family size, age, budget, medical needs and preferred benefit structure.
Can Families Combine MyKava and Imana Afya?
In some situations, families may compare both plans before deciding which structure works best.
A smaller family that wants strong individual limits may prefer MyKava.
A larger household seeking affordable shared protection may prefer Imana Afya.
Businesses, groups and chamas can also compare the two products depending on whether they want benefits allocated per person or shared under a group arrangement.
An insurance consultant can help you calculate the premiums and explain the policy terms before you buy.
What Is Required to Apply?
Applicants may be required to provide:
- Copy of KRA PIN
- Copy of National ID or passport
- Premium payment advice
- Details of the principal member and dependants
Additional underwriting information may be requested depending on the selected plan and policy terms.
How to Buy MyKava Medical Plan
You can request a quote or buy the MyKava Medical Plan online through:
https://www.imana.co.ke/mykava-product-quote
How to Buy Imana Afya Medical Plan
You can request a quote or apply for Imana Afya through:
https://www.imana.co.ke/insurance/imana-health
Get Help Choosing the Right Medical Cover
Choosing medical insurance should not feel confusing.
At Imana Insurance Agency Kenya Ltd, we help you compare the benefit structure, limits, premiums and policy conditions before you make a decision.
Our goal is to help you select a medical plan that fits your family, healthcare needs and budget.
Contact Imana Insurance Agency Kenya Ltd
Call or WhatsApp:
+254 113 619 635
+254 113 806 810
+254 745 218 460
+254 103 806 588
+254 796 209 402
Websites:
www.imana.co.ke
www.mykava.co.ke
Email:
insurance@imana.co.ke
mykava@mykava.co.ke
Location:
4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi, Kenya.
Final Verdict
Choose MyKava Medical Plan when you want individual medical benefits for every insured person.
Choose Imana Afya Medical Plan when you want affordable shared medical protection for your family, group or organization.
MyKava gives you stronger individual allocation.
Imana Afya gives you affordable shared protection.
The right choice is the one that gives you practical protection without placing unnecessary pressure on your budget.
Compare carefully. Choose wisely. Stay covered.