
Blog Details
Diskava. Beta. Kava
29Jul
MyKava Medical Insurance Kenya | Affordable Individual & Family Cover
Explore MyKava Medical Insurance options for individuals, children, families and groups in Kenya, with inpatient, outpatient, maternity, dental, optical and East Africa benefits.
Affordable Medical Insurance That Fits Different Life Stages
Medical expenses can arrive without warning.
A child may need emergency treatment. A parent may require hospital admission. A routine medical concern may develop into a condition that needs specialist care, diagnostic tests or ongoing treatment.
Without medical insurance, these costs can place considerable pressure on a family’s income and savings.
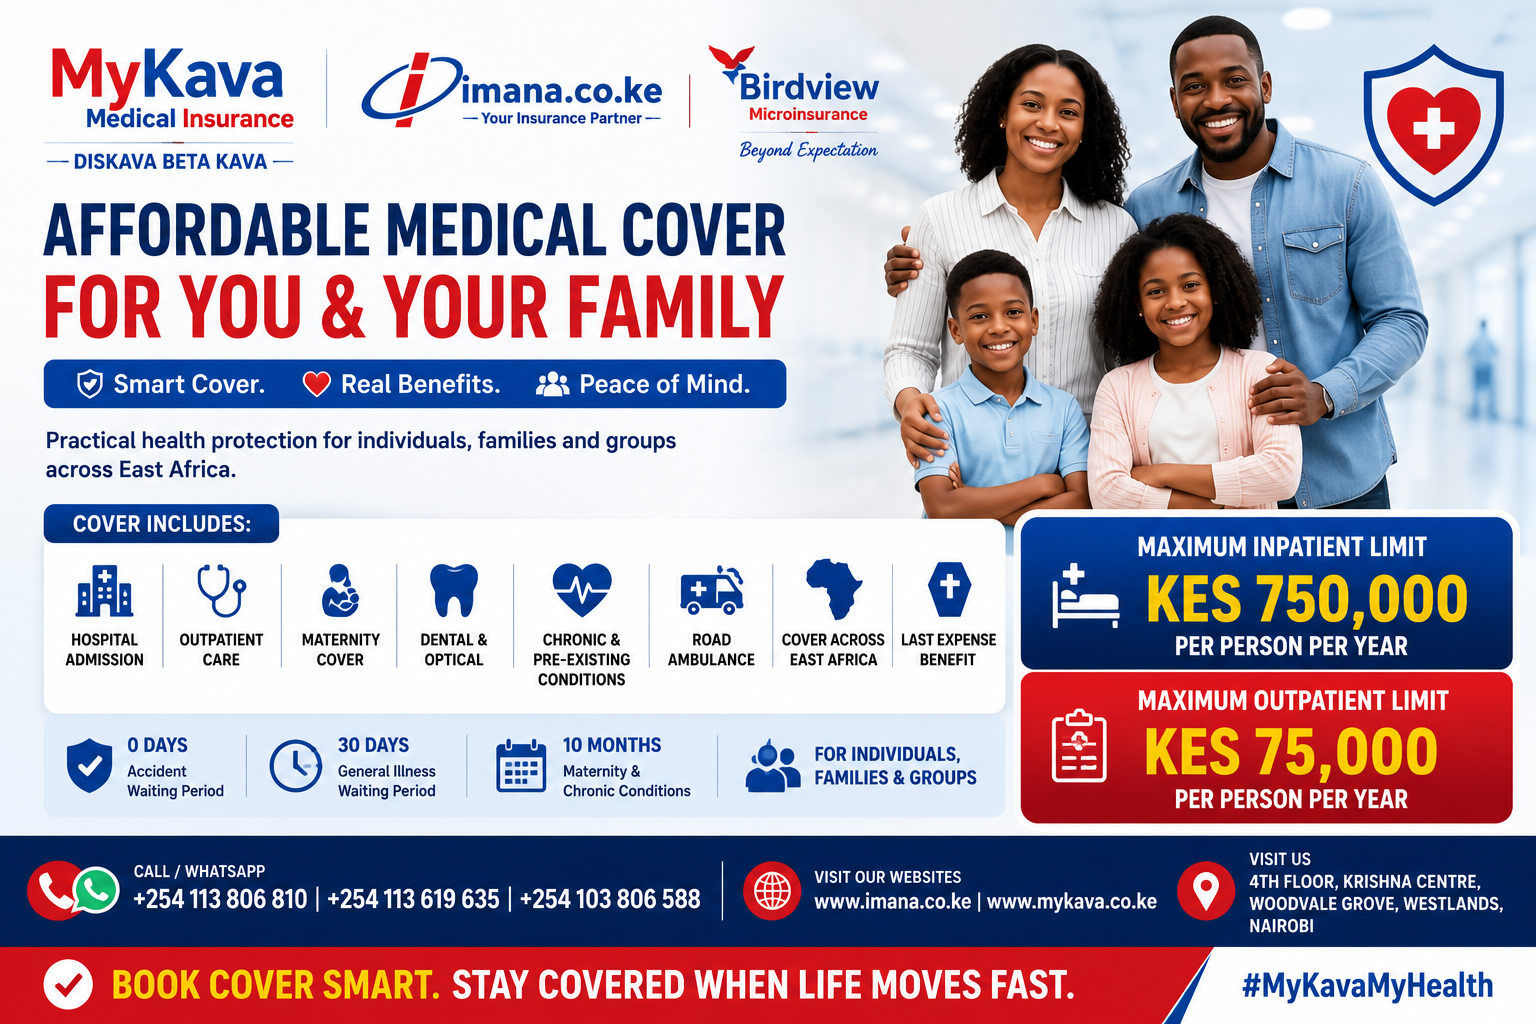
MyKava Medical Insurance provides practical medical protection for individuals, children, families and groups. The product offers several inpatient and outpatient options, allowing clients to select benefits according to their healthcare needs and available budget.
The cover is available through Imana Insurance Agency Kenya Ltd, which helps clients understand the options, review benefits and choose an appropriate plan.
Who Can Consider MyKava Medical Insurance?
The product may suit:
- Individuals looking for personal medical cover
- Parents seeking child-only medical insurance
- Couples and families
- Young adults taking out their first medical policy
- Senior family members within the eligible entry ages
- Employers seeking affordable group medical options
- Chamas, associations and organised groups
- Clients looking for East Africa medical protection
The available benefits and premiums depend on the age of the insured member and the inpatient or outpatient limits selected.
Four Inpatient Medical Insurance Options
MyKava Medical Insurance has four principal inpatient benefit levels:
- Plan 1: KSh 750,000 inpatient limit
- Plan 2: KSh 500,000 inpatient limit
- Plan 3: KSh 300,000 inpatient limit
- Plan 4: KSh 100,000 inpatient limit
This structure allows a client to select a higher or lower limit depending on the level of protection required and the available budget.
An inpatient limit is the maximum amount available for covered hospital-admission expenses during the insurance period, subject to the policy terms, applicable sublimits and exclusions.
What the Inpatient Cover May Include
The four plans include several important medical benefits, subject to the selected option and policy conditions.
These include:
- General ward hospital accommodation
- Road ambulance services
- Psychiatric hospitalisation
- Maternity benefits
- Treatment of certain chronic and pre-existing conditions
- Certain congenital conditions
- HIV/AIDS-related conditions
- Inpatient dental treatment
- Inpatient ophthalmology treatment
- Internal and external medical appliances
- Last expense benefit
- East Africa territorial cover
The applicable limit may differ from one benefit to another. Clients should therefore review both the overall inpatient limit and the individual sublimits within the selected plan.
Outpatient Medical Insurance Options
Clients may also select outpatient benefits.
The available annual outpatient limits are:
- KSh 75,000
- KSh 50,000
- KSh 40,000
- KSh 30,000
Outpatient insurance is intended for covered medical treatment that does not require overnight hospital admission.
Depending on the plan, outpatient benefits may include:
- General consultations
- Prescribed medication
- Diagnostic tests
- Laboratory services
- Dental care
- Optical care
- Certain vaccinations and immunisations
- Chronic-condition management
- Family-planning benefits
- Follow-up consultations
Outpatient benefits are not automatically unlimited. Treatment is paid within the selected annual limit and any applicable benefit sublimits.
Medical Insurance for Children
MyKava may be suitable for parents seeking medical insurance specifically for their children.
Children may be covered from birth, subject to the policy’s definition and eligibility conditions. Dependant cover may continue up to age 25 where the dependant remains in recognised full-time education and proof of schooling is provided.
This can help parents protect children against expenses arising from:
- Accidents
- General illnesses
- Hospital admission
- Medical consultations
- Prescribed medicine
- Certain congenital conditions
- Dental and optical treatment
- Diagnostic tests
Before buying child-only medical insurance, parents should confirm:
- The inpatient limit
- Whether outpatient cover is included
- The provider network
- Applicable waiting periods
- Benefit sublimits
- Pre-authorisation requirements
- The claims and admission procedure
Entry Ages and Renewal
Adults may enter the medical insurance plan from age 18 up to age 75.
Renewal may be extended beyond the maximum entry age, up to age 100, subject to the policy conditions and continuous renewal requirements.
The difference between entry age and renewal age is important.
The entry age determines whether a new applicant can join the plan. The renewal age determines how long an existing policyholder may continue renewing cover, subject to the insurer’s terms.
Clients approaching the maximum entry age should therefore consider applying before they become ineligible for new entry.
Cover for Pre-Existing and Chronic Conditions
One of the significant features of the plan is the inclusion of benefits for certain:
- Pre-existing conditions
- Chronic illnesses
- Psychiatric conditions
- Congenital conditions
- HIV/AIDS-related conditions
However, these benefits remain subject to waiting periods, sublimits, policy definitions and other conditions.
A pre-existing condition is generally a medical condition, illness, symptom or diagnosis that existed before the policy began, whether or not treatment had already been obtained.
Clients should disclose relevant medical information honestly during the application process.
Failure to provide accurate information may affect approval, treatment authorisation or claim payment.
Medical Insurance Waiting Periods
A waiting period is the time a policyholder must wait before specific benefits become available.
The main waiting periods under the presented plan are:
Accidents: 0 days
Accidental injury cover may begin immediately after the policy becomes effective, subject to confirmation of cover and payment of the required premium.
General illness: 30 days
Treatment for ordinary illnesses becomes available after a 30-day waiting period.
Maternity and pregnancy complications: 10 months
Maternity-related benefits and pregnancy complications have a 10-month waiting period.
Chronic and pre-existing conditions: 10 months
Benefits relating to chronic or pre-existing conditions also have a 10-month waiting period.
The presentation indicates that these waiting periods apply to individual policies and certain group policies whose premiums fall below the specified group threshold.
Waiting periods exist to prevent people from buying insurance only after treatment has already become necessary.
Maternity Insurance Benefits
Maternity benefits are available across the four inpatient plan options.
The applicable maternity limit depends on the selected plan:
- Higher inpatient plans offer higher maternity sublimits
- Lower plans offer smaller maternity sublimits
- The 10-month waiting period applies
- Pregnancy-related complications are subject to policy conditions
The maternity benefits may include covered expenses relating to:
- Normal delivery
- Caesarean section
- Pregnancy complications
- Maternity hospitalisation
Clients planning to start or grow a family should buy maternity insurance early because the waiting period begins from the effective date of the policy.
Buying cover after pregnancy has already begun may not provide benefits for that pregnancy.
Dental and Optical Benefits
Dental and optical benefits are provided within the outpatient structure.
The combined limits are:
- Plan 1: KSh 10,000
- Plan 2: KSh 7,500
- Plan 3: KSh 5,000
- Plan 4: KSh 5,000
Covered services may include:
Dental benefits
- Dental consultations
- Treatment of gum disease
- Extractions
- Fillings, excluding certain precious materials
- Scaling
- Dental X-rays
- Prescribed dental medication
Optical benefits
- Routine optical consultations
- Eye examinations
- Prescribed lenses
- Replacement lenses
- Optical prescriptions
- Limited frame benefit
Dental and optical expenses remain subject to the combined limit and the policy terms.
Diagnostic Tests and Pre-Authorisation
Certain advanced diagnostic procedures require approval before treatment.
These include:
- MRI scans
- CT scans
- PET scans
Pre-authorisation means the hospital or policyholder must obtain approval before the test is carried out.
Failure to obtain the required approval may affect reimbursement or payment.
For planned hospital admission, clients should also confirm the required approval timelines. In an emergency, the hospital or insured person should contact the relevant medical insurer or administrator within the stipulated period.
East Africa Medical Coverage
The plans provide territorial cover within East Africa.
This may be useful for:
- People who travel within the region
- Families with dependants living or studying in another East African country
- Business travellers
- Regional employees
- Clients who divide their time between Kenya and neighbouring countries
Emergency medical treatment while travelling may be covered for a limited period, subject to policy conditions, reasonable and customary medical costs and the insurer’s reimbursement rules.
Territorial cover does not mean every hospital in East Africa is automatically available on a cashless basis. Clients should confirm the approved provider network and reimbursement process before seeking non-emergency treatment outside Kenya.
Annual Medical Insurance Premiums
Premiums are calculated according to:
- Age band
- Selected inpatient limit
- Selected outpatient limit
- Number of people insured
- Additional benefit requirements
- Individual or group arrangement
The presentation shows indicative inpatient premiums starting from approximately KSh 4,810 per year for persons aged between one month and 20 years under the lowest inpatient option.
Indicative outpatient premiums begin from approximately KSh 5,860 per year for the same age group under the KSh 30,000 outpatient limit.
These amounts are starting points, not universal premiums.
Older age groups generally pay higher premiums because medical risk and expected healthcare usage tend to increase with age.
How to Select the Right Medical Insurance Plan
Choosing medical insurance should not be based on price alone.
Consider the following factors.
1. Your expected healthcare needs
A person who rarely visits hospital may select a different structure from someone managing an ongoing condition.
2. The number and ages of family members
A young child, adult and senior citizen may have very different healthcare requirements.
3. Inpatient limit
A low inpatient limit may be affordable, but it may be insufficient for a major admission, surgery or extended hospital stay.
4. Outpatient requirements
Consider how frequently you visit clinics, buy prescribed medicine or require diagnostic tests.
5. Maternity plans
Anyone considering pregnancy should examine the maternity waiting period and benefit limit carefully.
6. Chronic-condition benefits
Confirm how pre-existing and chronic conditions are treated and whether sublimits apply.
7. Hospital network
Check whether your preferred hospitals, clinics, doctors and pharmacies are available within the provider panel.
8. Dental and optical needs
Clients who regularly require dental or optical treatment should compare the applicable combined sublimit.
9. Waiting periods
A plan may appear attractive, but some benefits may not begin immediately.
10. Exclusions
Always review what the policy does not cover.
Important Medical Insurance Exclusions
Medical insurance does not cover every medical expense.
Notable exclusions may include:
- Refusal or failure to follow medical advice
- Herbal, acupuncture and chiropractic treatment
- Beauty treatments and massages
- Sanatorium and old-age-home stays
- Certain genetic tests and related conditions
- Cosmetic or plastic surgery, unless required following an insured accidental injury
- Vitamins, nutritional supplements and dietary replacements
- Treatment connected to alcoholism or drug addiction
- Weight-reduction treatment
- War, terrorism, riots, strikes and civil commotion
- Certain epidemics, pandemics or unknown diseases
- Expenses recoverable under SHA, WIBA or personal accident insurance
Clients should read the full policy document because exclusions, definitions and benefit restrictions determine how a claim will be handled.
The Relationship Between SHA and Private Medical Insurance
Private medical insurance does not necessarily replace SHA.
Depending on the treatment and applicable rules, some expenses may first be payable under SHA, while private insurance may address eligible expenses within the selected benefits and limits.
The presentation specifically notes that expenses recoverable through SHA, WIBA or personal accident insurance may be excluded from payment under the medical plan.
Clients should therefore understand how the different covers work together.
This helps prevent duplicated expectations and makes it easier to follow the correct claims process.
How to Apply for MyKava Medical Insurance
The application process generally involves the following steps:
- Select an inpatient limit.
- Decide whether outpatient cover is required.
- Confirm the age of each member.
- Add children or other eligible dependants.
- Review waiting periods.
- Understand the exclusions and benefit sublimits.
- Confirm the provider network.
- Submit the required identification and application information.
- Pay the approved premium.
- Receive written confirmation before using the cover.
A client should not assume that submitting an application means the cover has started.
Cover should be confirmed in writing after the required premium has been received and the application has been accepted.
Compare Medical Insurance Quotes Through Imana
Imana Insurance Agency Kenya Ltd helps clients compare medical insurance options and understand the practical differences between plans.
The comparison process may consider:
- Annual premium
- Inpatient limit
- Outpatient limit
- Maternity benefit
- Dental and optical benefits
- Chronic and pre-existing condition limits
- Entry and renewal ages
- Waiting periods
- Territorial cover
- Hospital networks
- Exclusions
- Claims and pre-authorisation requirements
The cheapest medical plan is not always the best.
A suitable plan should provide benefits that match the client’s age, family structure, health requirements and budget.
Medical Insurance in Westlands, Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd serves individuals, families and groups from its Westlands office and through digital channels across Kenya.
Visit:
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
The office is accessible to clients around:
- Westlands
- Sarit Centre
- Westgate
- Parklands
- Riverside
- Spring Valley
- Lavington
- Gigiri
- Runda
- Kitisuru
- Muthaiga
- Nairobi CBD
Clients in other counties can request quotations and submit documents online.
Request a MyKava Medical Insurance Quote
Protecting your health should not begin after a medical emergency.
Compare the available inpatient and outpatient options while you are healthy, review the waiting periods and select a plan that fits your needs.
Website: www.imana.co.ke
MyKava: www.mykava.co.ke
Medical quotation page: https://imana.co.ke/mykava-product-quote
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call or WhatsApp: +254 796 209 402
Choose cover before you need care. Plan today so a medical bill does not control tomorrow.
Frequently Asked Questions
What is the lowest inpatient limit available?
The lowest inpatient limit presented is KSh 100,000 per person per year.
What is the highest inpatient limit?
The highest inpatient option is KSh 750,000 per person per year.
Can I add outpatient cover?
Yes. Outpatient options range from KSh 30,000 to KSh 75,000 annually.
Can a child be insured without a parent?
Child-only medical cover may be available, subject to the applicable eligibility and policy conditions.
Are pre-existing conditions covered?
Certain pre-existing and chronic conditions may be covered within defined sublimits after the applicable waiting period.
What is the maternity waiting period?
The maternity and pregnancy-complications waiting period is 10 months.
Is there a waiting period for accidents?
The presented product provides a zero-day accident waiting period, subject to confirmation that the policy is active.
What is the general illness waiting period?
The general illness waiting period is 30 days.
Are dental and optical benefits included?
They are included within the outpatient benefits, subject to a combined limit based on the selected plan.
Does the cover apply outside Kenya?
The plan has an East Africa territorial scope, subject to provider, reimbursement and policy conditions.
Is a medical examination required before joining?
The presentation indicates that medical examinations are not generally required, but applicants must still provide accurate health information where requested.
Are MRI and CT scans covered?
They may be covered subject to the selected benefits, limits and prior authorisation.
Can senior citizens join?
New adult applicants may enter up to age 75. Existing members may qualify for renewal extensions subject to the policy terms.
Are the premiums fixed?
No. Premiums vary by age and the inpatient and outpatient benefits selected.
Premiums, benefits, waiting periods, hospital access, exclusions and claim payments remain subject to the insurer’s underwriting requirements, policy schedule and full policy wording. Indicative premiums may change, and written confirmation of cover should be obtained before treatment is sought.