
Blog Details
Diskava. Beta. Kava
15Jul
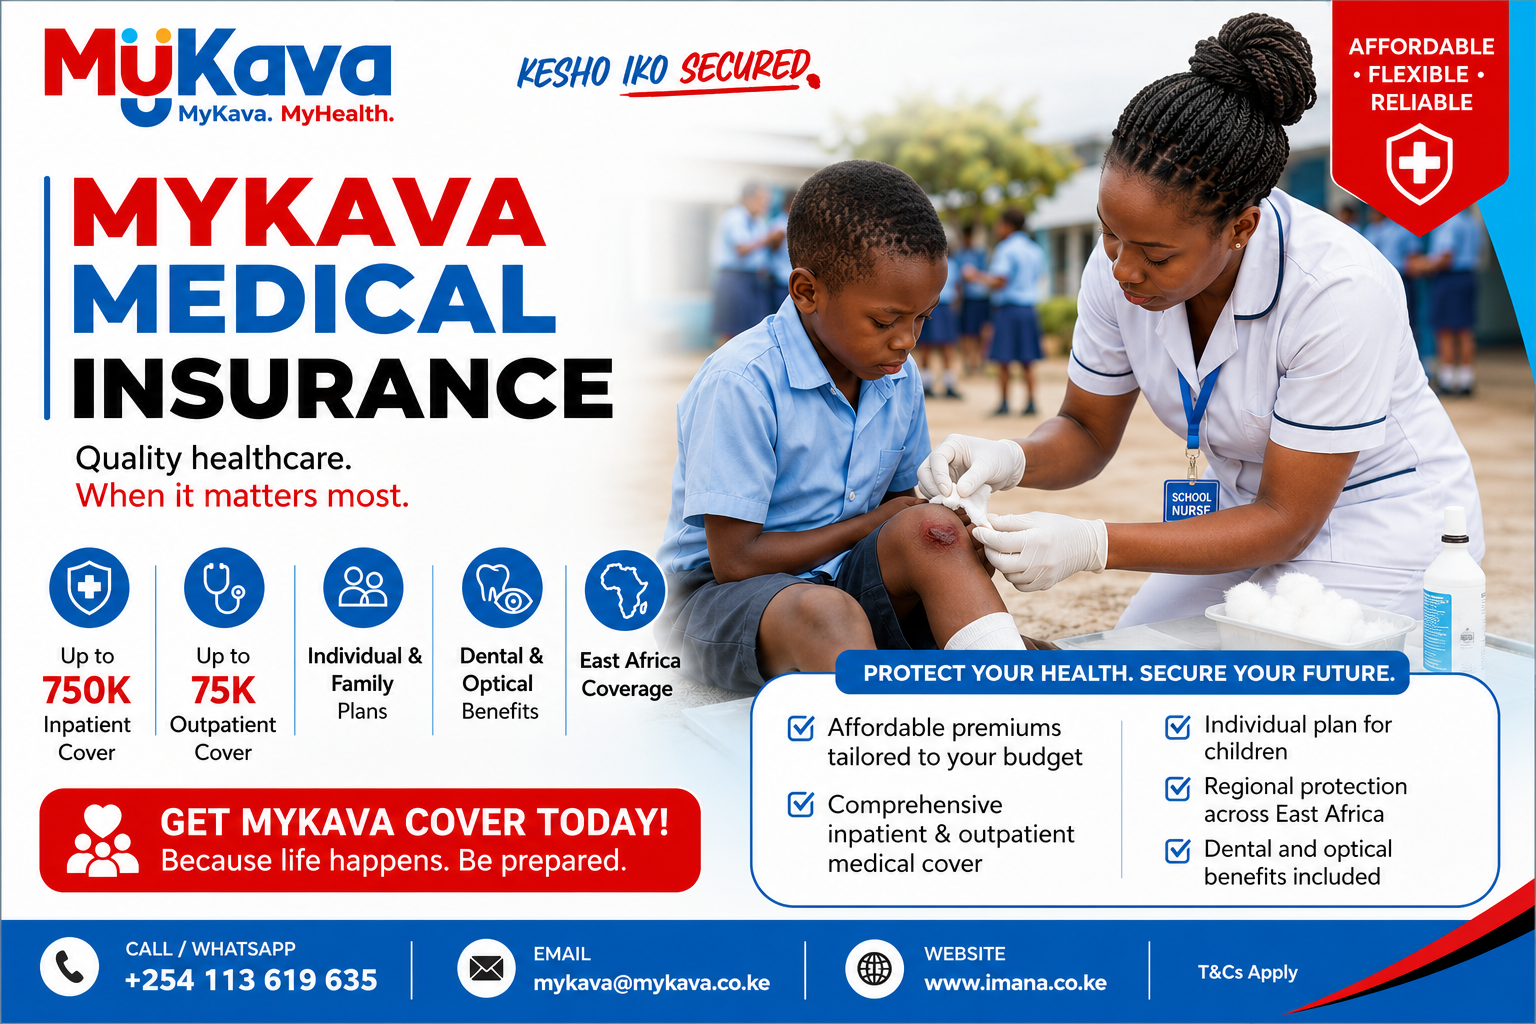
MyKava Medical Insurance: Affordable Health Cover for Individuals and Families in Kenya
Medical emergencies rarely arrive with a warning. A child may fall while playing at school, a parent may suddenly require specialist attention, or an ordinary illness may lead to unexpected hospital expenses.
When this happens, the biggest concern should be recovery—not the cost of treatment.
MyKava Medical Insurance is designed to give individuals, children, families and groups access to flexible and affordable healthcare protection. The cover helps members prepare for both planned and unexpected medical needs while reducing the financial pressure that often comes with treatment.
What Is MyKava Medical Insurance?
MyKava Medical Insurance is a health insurance solution that provides inpatient and outpatient medical benefits. It allows clients to select the level of protection that suits their healthcare needs, age and budget.
The product is suitable for:
- Individuals
- Children
- Couples
- Families
- Parents and senior citizens
- Groups and organisations
MyKava also offers regional protection across East Africa, making it useful for people who live, work, study or travel within the region.
Key Benefits of MyKava Medical Insurance
1. Inpatient Cover of Up to KSh 750,000
Inpatient insurance helps cover medical expenses when a member is admitted to hospital.
MyKava offers several inpatient benefit options:
- KSh 100,000
- KSh 300,000
- KSh 500,000
- KSh 750,000
The availability of different limits makes it easier for clients to choose a plan that matches their budget and level of risk.
Inpatient cover can provide valuable financial protection when dealing with hospital admission, treatment and other eligible medical expenses, subject to the policy terms and conditions.
2. Outpatient Cover of Up to KSh 75,000
Not every medical condition requires hospital admission. Many families regularly spend money on consultations, laboratory tests, medication and follow-up treatment.
MyKava offers outpatient benefit options of:
- KSh 30,000
- KSh 40,000
- KSh 50,000
- KSh 75,000
This benefit can help members manage routine and unexpected healthcare expenses without paying the entire cost from their personal savings.
3. Individual Medical Plans for Children
Children are naturally active. They run, play, explore and sometimes get injured.
A fall during school break, a sports injury or a sudden illness can create an urgent need for medical attention. MyKava allows parents and guardians to purchase an individual medical plan for a child without necessarily placing the child under a full family policy.
This is particularly helpful for:
- Parents seeking child-only medical insurance
- Guardians taking care of dependants
- Families whose existing medical cover excludes some children
- Parents looking for additional protection beyond another health scheme
4. Dental and Optical Benefits
Dental pain and eyesight problems can affect a person’s health, confidence, school performance and productivity.
MyKava Medical Insurance includes dental and optical benefits under applicable plans. These benefits can assist with eligible dental and eye-care services, depending on the selected cover and policy conditions.
Clients should confirm the exact limits, waiting periods and covered procedures when requesting a quotation.
5. East Africa Regional Coverage
Healthcare needs do not always arise when someone is close to home.
MyKava provides regional protection across East Africa. This can be valuable for business owners, employees, students, families and frequent travellers who move between countries within the region.
The geographical scope and participating medical facilities should always be confirmed before purchasing the policy.
MyKava Medical Insurance Premiums
MyKava premiums are determined by factors such as:
- The insured person’s age
- The selected inpatient limit
- The selected outpatient limit
- Additional benefits
- The number of people being insured
- Applicable underwriting conditions
For inpatient cover, annual premiums shown in the product schedule begin from approximately KSh 4,810 for eligible younger members selecting the KSh 100,000 inpatient limit.
Higher benefit limits and older age bands attract higher premiums because the expected healthcare risk is greater.
Outpatient cover is priced separately according to the chosen limit and age category.
A personalised quotation is therefore essential. It helps the client understand the exact premium, benefits, exclusions and terms before making payment.
Why Health Insurance Matters
A medical emergency can affect more than a person’s health. It can interrupt school, work, business operations and family plans.
Without medical insurance, families may be forced to:
- Use emergency savings
- Borrow money
- Sell valuable assets
- Delay treatment
- Depend on relatives and friends
- Settle large hospital bills from personal income
Health insurance does not prevent sickness or accidents. It helps reduce the financial shock when treatment is required.
It transforms an unpredictable medical expense into a planned annual cost.
MyKava Medical Insurance for Families
Families have different healthcare needs.
Children may require regular consultations, parents may need ongoing medical reviews, and older family members may have a higher likelihood of hospital admission.
MyKava allows families to select different benefit levels based on their needs and affordability. This flexibility can help households avoid paying for a one-size-fits-all plan that may not reflect their actual circumstances.
When comparing family medical insurance, consider:
- The number and ages of family members
- Preferred hospitals
- Existing medical conditions
- Inpatient and outpatient limits
- Dental and optical needs
- Regional travel requirements
- Waiting periods
- Co-payments and exclusions
The cheapest policy is not always the most suitable. A good medical plan should provide practical protection at a premium the family can sustain.
Medical Insurance for Parents and Senior Citizens
As people grow older, access to reliable healthcare becomes increasingly important.
MyKava provides premium options for eligible members up to 75 years old, according to the product schedule. Premiums increase across the age bands because older members generally present a higher medical risk.
Before enrolling an older parent or relative, disclose all relevant medical information accurately. Failure to declare existing conditions may affect claim assessment or eligibility.
It is also important to confirm:
- Entry-age requirements
- Pre-existing-condition terms
- Waiting periods
- Hospital network
- Benefit limits
- Renewal conditions
MyKava Medical Insurance for Groups
MyKava can also be considered by organised groups and employers seeking medical protection for their members or employees.
Group medical cover may be relevant for:
- Small and medium-sized businesses
- Associations
- Welfare groups
- Churches
- Professional organisations
- Chamas
- Community groups
Group arrangements may differ from individual policies, so organisations should request a tailored quotation based on membership size, age distribution and required benefits.
How to Choose the Right MyKava Plan
Before purchasing a policy, ask yourself three important questions.
How much inpatient protection do I need?
A higher inpatient limit provides more protection against major hospital expenses. However, it also attracts a higher premium.
Choose a limit that provides meaningful protection without creating an unsustainable annual cost.
Do I need outpatient cover?
People with children, regular prescriptions or frequent consultations may benefit from outpatient cover.
Someone who rarely visits a clinic may choose to prioritise inpatient protection, depending on their circumstances.
Which additional benefits matter to me?
Dental, optical and regional benefits can be important, but the policy should reflect your actual needs.
Review each benefit carefully instead of choosing a plan solely because it has the lowest premium.
Important Questions to Ask Before Buying
Before paying for MyKava Medical Insurance, request clarification on:
- Covered hospitals and medical providers
- Waiting periods
- Pre-existing conditions
- Exclusions
- Claim procedures
- Co-payments
- Dental and optical limits
- Regional coverage
- Policy start date
- Renewal terms
- Required documents
Insurance becomes valuable when the policyholder understands what is covered, what is excluded and how to access treatment.
How to Apply for MyKava Medical Insurance
The application process generally involves:
- Requesting a quotation.
- Providing the ages and details of the people to be insured.
- Selecting inpatient and outpatient limits.
- Reviewing the benefits, exclusions and policy terms.
- Completing the required application documents.
- Paying the applicable premium.
- Receiving confirmation of cover and membership information.
Applicants should provide complete and truthful information during the application process.
Protect Your Health Before an Emergency Happens
A child’s fall, a sudden fever or an unexpected hospital admission can happen on an ordinary day.
The best time to arrange medical insurance is before treatment becomes urgent.
MyKava Medical Insurance provides flexible options for individuals, children, families, older members and groups. With inpatient cover of up to KSh 750,000, outpatient cover of up to KSh 75,000, child-only plans, dental and optical benefits and East Africa regional protection, clients can choose a plan based on their needs and budget.
Request a Free MyKava Medical Insurance Quote
Call or WhatsApp: +254 113 619 635
Email: mykava@mykava.co.ke
Website: www.imana.co.ke | www.mykava.co.ke
Benefits, premiums, eligibility, waiting periods and claims are subject to the insurer’s terms, conditions and underwriting requirements.
Get affordable MyKava Medical Insurance in Kenya with inpatient cover up to KSh 750,000, outpatient cover up to KSh 75,000, child-only plans, dental, optical and East Africa coverage.