
Blog Details
Diskava. Beta. Kava
15Aug
Motor Insurance Kenya | Compare Car Insurance Quotes, Excesses & Covers
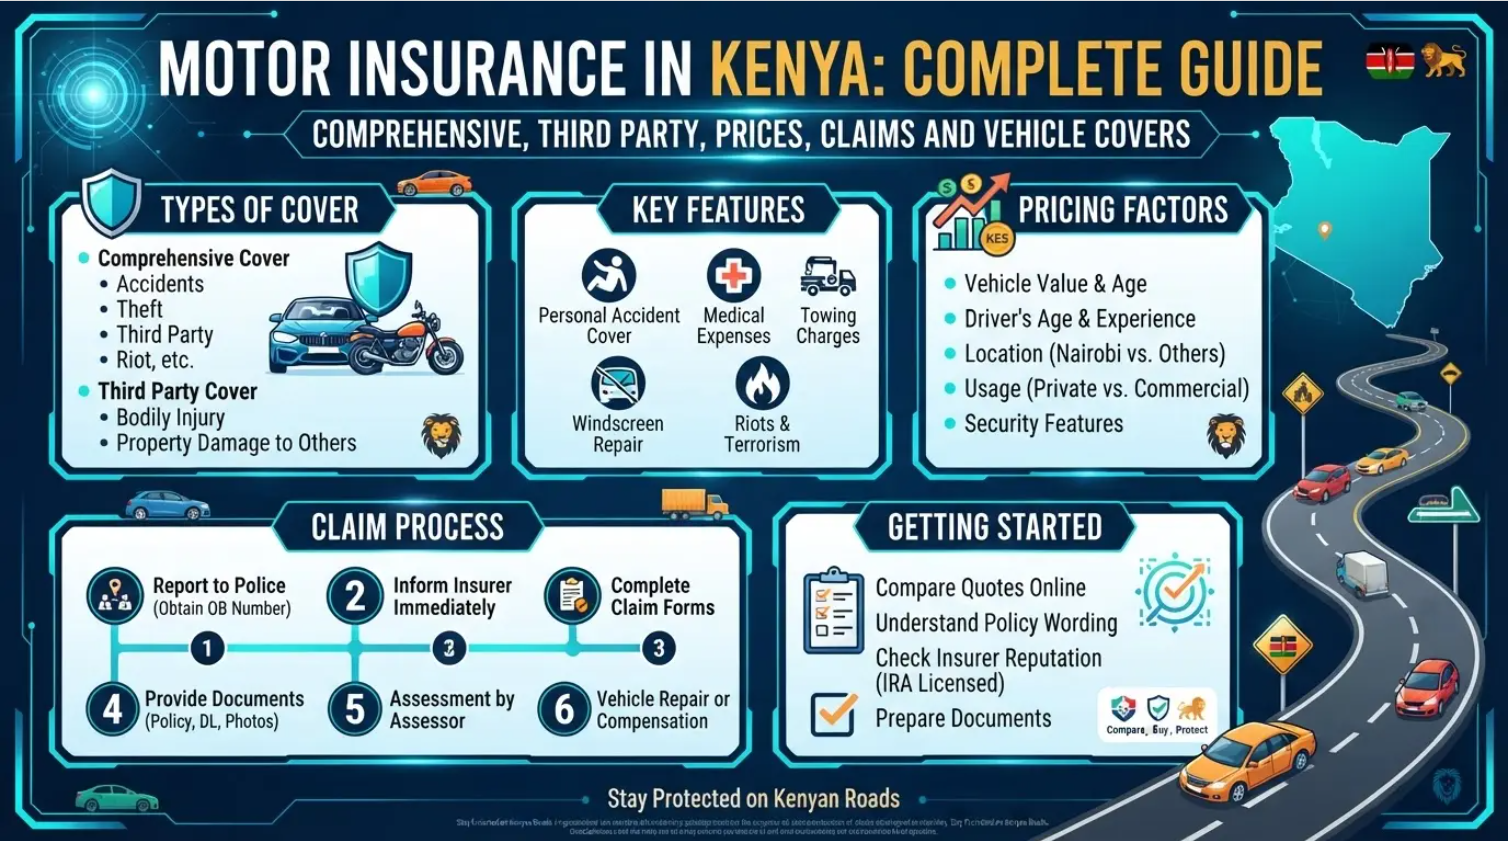
Complete guide to Motor Insurance in Kenya covering Comprehensive and Third Party insurance, prices, Excess Protector, PVT, valuation, claims, windscreen, road rescue, COMESA, PSV, motorcycles and more.
Motor Insurance is one of the most important financial protections for vehicle owners in Kenya.
Whether you drive:
- A private car
- Commercial vehicle
- PSV taxi
- Uber or Bolt vehicle
- Matatu
- Bus
- School bus
- Motorcycle
- Boda boda
- Tuk-Tuk
- Tour van
- Safari vehicle
- Duty-free vehicle
the correct insurance should reflect how the vehicle is actually used.
Kenya's motor-insurance framework requires applicable third-party protection for vehicles used on public roads, while the Insurance Regulatory Authority regulates insurers and insurance intermediaries operating in the market.
At Imana Insurance Agency Kenya Ltd, motorists can compare Motor Insurance quotations for private cars, commercial vehicles, PSVs, motorcycles and Tuk-Tuks. Imana's online quotation form currently allows customers to select Comprehensive, Third Party or Third Party Fire & Theft cover and provide details including vehicle value, year, passengers and valuation status.
The best Motor Insurance policy is not necessarily the cheapest. It is the policy that correctly describes your vehicle, how you use it and the financial risks you cannot comfortably carry yourself.
What Is Motor Insurance?
Motor Insurance is an agreement under which an insurer provides specified financial protection relating to a motor vehicle in exchange for payment of a premium.
Depending on the policy selected, Motor Insurance may protect against:
- Third-party bodily injury
- Third-party death
- Third-party property damage
- Accidental damage to your vehicle
- Theft
- Fire
- Flood damage
- Passenger liability
- Other insured risks
Imana currently lists three principal forms of Motor Insurance: Comprehensive, Third Party Only and Third Party Fire & Theft. It also lists private, commercial, PSV, motorcycle, Tuk-Tuk, tour-service and school-bus vehicle classes.
Comprehensive vs Third Party Motor Insurance in Kenya
One of the first decisions a motorist must make is whether to buy Comprehensive or Third Party Insurance.
Third Party Only Insurance
Third Party Only, commonly called TPO, primarily protects against eligible legal liability arising from injury, death or property damage caused to other people.
It is the basic compulsory form of motor protection.
However, it does not ordinarily pay to repair your own vehicle after an accident.
If your Third-Party-insured vehicle:
- Collides with another car
- Overturns
- Is damaged while parked
you may need to meet your own repair expenses.
Imana describes TPO as the minimum legal option and distinguishes it from Comprehensive Insurance, which protects the insured vehicle against a wider range of risks.
Third Party, Fire and Theft
Third Party Fire & Theft sits between TPO and Comprehensive Insurance.
It generally includes:
- Third-party liability
- Theft of the insured vehicle
- Fire damage to the insured vehicle
It does not ordinarily provide the same accidental-damage protection as Comprehensive Insurance.
Imana's online motor quotation form currently includes Third Party Fire & Theft as a selectable Motor Insurance option.
Comprehensive Motor Insurance
Comprehensive Insurance provides the broadest standard Motor Insurance protection.
Depending on the policy and extensions selected, it may cover:
- Accidental damage
- Collision
- Overturning
- Fire
- Theft
- Flood
- Third-party liability
- Other specified risks
Imana's Motor Insurance page identifies accidents, fire, theft, floods and third-party liabilities among the risks generally addressed by Comprehensive cover.
However:
Comprehensive does not mean everything is automatically covered.
Every policy still contains:
- Excesses
- Limits
- Exclusions
- Driver conditions
- Territorial limits
- Security requirements
- Claims procedures
Motor Insurance Prices in Kenya
There is no single price for Motor Insurance in Kenya.
The premium depends on several factors.
Third Party Insurance pricing
Third Party premiums are commonly influenced by the vehicle class.
For example, pricing may differ between:
- Private car
- Commercial vehicle
- PSV taxi
- Matatu
- Bus
- Motorcycle
- Tuk-Tuk
A private family vehicle should not be priced or insured in the same way as a vehicle carrying passengers for hire and reward.
Comprehensive Insurance pricing
Comprehensive premiums are generally influenced by factors such as:
- Vehicle market value
- Vehicle type
- Vehicle age
- Intended use
- Claims history
- Driver profile
- Insurer
- Selected extensions
- Applicable excess
- Security measures
The Imana Motor Quote form specifically asks for vehicle value, type of cover, vehicle make, year of manufacture, professional valuation status and passenger capacity, illustrating some of the information used when preparing Motor Insurance quotations.
Why comparing premiums alone can be misleading
Two Comprehensive quotations may have different:
- Excesses
- Windscreen limits
- Road rescue benefits
- Courtesy-car provisions
- PVT protection
- Excess Protector
- Driver restrictions
The better comparison is therefore:
Premium + benefits + excesses + exclusions + claims conditions
What Is an Insurance Excess?
An excess is the portion of an admissible insured loss that remains payable by the policyholder under the terms of the policy.
For example:
Repair cost:
KSh 200,000
Applicable excess:
KSh 20,000
Subject to the policy and other applicable adjustments:
- Policyholder bears KSh 20,000
- Insurer considers the remaining KSh 180,000
Different excesses may apply to:
- Ordinary accidental damage
- Young drivers
- Inexperienced drivers
- Theft
- Total loss
- Windscreen claims
Always understand the excess before selecting a quotation.
What Is Excess Protector?
Excess Protector is an optional extension intended to protect the policyholder against specified excess amounts that would otherwise be payable during an admissible claim.
It can significantly improve a Comprehensive Motor policy.
However, Excess Protector may not eliminate every excess.
Always ask:
- Does it cover the basic excess?
- Does it include theft excess?
- Does it cover young-driver excess?
- Does it cover inexperienced-driver excess?
- Are there vehicle-class restrictions?
Do not assume “Excess Protector” means zero contribution under every possible motor claim.
What Is PVT Motor Insurance?
PVT commonly refers to Political Violence and Terrorism cover.
It may be added to a Motor Insurance policy to provide protection against specified losses arising from events such as:
- Political violence
- Terrorism
- Riots
- Civil commotion
- Related malicious acts
depending on the wording.
Standard Comprehensive Insurance should not automatically be assumed to include all these risks.
PVT should therefore be checked separately when comparing quotations.
Why Vehicle Valuation Matters
Vehicle valuation is particularly important under Comprehensive Insurance.
A professional valuation helps establish the vehicle's reasonable current market value.
Imana's motor quotation form asks whether the vehicle has undergone professional valuation, while its Motor Insurance page identifies vehicle valuation as part of its motor service offering.
A valuation may consider:
- Make and model
- Year of manufacture
- Mileage
- General condition
- Accessories
- Modifications
- Existing damage
- Market value
Underinsurance
Underinsurance occurs when the vehicle is insured below an appropriate value.
Depending on the policy, this may result in:
- Reduced claim settlement
- Application of an average condition
- Inadequate total-loss compensation
Trying to reduce your premium by deliberately declaring an unrealistically low vehicle value can therefore become very expensive during a claim.
Overinsurance
Overinsurance occurs when the vehicle is insured substantially above its reasonable value.
Insurance is based on indemnity.
That means paying premium on an inflated vehicle value does not normally entitle the policyholder to profit after a total loss.
The aim should be accurate valuation, not simply a high or low figure.
Motor Insurance Claims in Kenya
The true value of Motor Insurance becomes visible when something goes wrong.
Imana operates an online claim-notification system covering Motor Insurance and other policy classes. Its claim form requests policy or vehicle-registration information, accident details, damage estimates, police-report information and other claim details.
What to do after a motor accident
1. Protect people
Check for injuries and arrange emergency assistance where necessary.
2. Secure the scene
Use:
- Hazard lights
- Reflective triangles
- Safe positioning where possible
3. Take photographs and videos
Capture:
- Vehicle positions
- Registration plates
- Vehicle damage
- Road conditions
- Traffic signs
- Third-party property
4. Exchange details
Record:
- Driver names
- Telephone contacts
- Vehicle registrations
- Insurance information
- Witness contacts
5. Report to the police
Obtain the required police documentation.
6. Notify your insurer or intermediary
Do this promptly.
7. Avoid unauthorised repairs
The insurer may need to appoint a motor assessor and approve repairs.
8. Do not admit liability
Provide factual information without privately accepting responsibility or promising compensation.
Documents Commonly Required for Motor Claims
Depending on the claim, you may need:
- Claim form
- Insurance certificate
- Policy schedule
- Vehicle logbook
- Driver's licence
- Police abstract
- Photographs
- Repair estimate
- Assessor's report
- Third-party information
- Witness details
Imana's claim platform allows motorists to start notification online and indicates that supporting-document requirements are communicated after claim submission.
Claims:
https://imana.co.ke/claims-request
Windscreen Insurance
Windscreen protection may form part of a Comprehensive Motor policy or be subject to a separate limit.
It may apply to:
- Front windscreen
- Rear glass
- Side windows
depending on the insurer.
Check:
- Annual windscreen limit
- Whether an excess applies
- Whether side glass is included
- Whether replacement requires prior approval
Do not assume the entire vehicle sum insured is available for a broken windscreen.
Courtesy Car Cover
A Courtesy Car benefit may provide temporary replacement transport while your insured vehicle is undergoing approved repairs following an admissible claim.
Terms may include:
- Maximum number of days
- Vehicle category
- Availability
- Approved repair period
- Qualifying claim type
A courtesy car is not automatically part of every Comprehensive Motor policy.
It should be specifically checked during quotation comparison.
Road Rescue and Towing
Road Rescue can provide important assistance after:
- Accidents
- Breakdown
- Flat battery
- Tyre problems
- Other roadside emergencies
Possible services may include:
- Towing
- Battery jump-start
- Tyre assistance
- Fuel assistance
- Recovery
Imana's PSV page specifically lists towing after an accident among Comprehensive PSV benefits, illustrating how roadside-related assistance may form part of selected Motor Insurance arrangements.
Check:
- Towing limit
- Distance covered
- Number of call-outs
- Geographical area
- Whether breakdown and accident towing are treated differently
COMESA Yellow Card Insurance
Motorists driving from Kenya into participating regional countries may require a COMESA Yellow Card.
The regional Yellow Card framework provides recognised cross-border third-party Motor Insurance protection within participating jurisdictions, and Kenya has long-standing legal rules recognising the regional motor third-party scheme.
It is useful for:
- Private vehicles
- Commercial vehicles
- Tour vehicles
- Motorcycles
- Cross-border transport
However:
A COMESA Yellow Card does not automatically provide Comprehensive own-damage protection for your vehicle outside Kenya.
The motorist should separately confirm whether the underlying Comprehensive policy has been territorially extended.
Imana lists COMESA Yellow Card Insurance among its available motor-related products.
COMESA Yellow Card:
https://imana.co.ke/comesa-insurance
PSV Insurance in Kenya
PSV Insurance is designed for vehicles carrying passengers for hire and reward.
It may apply to:
- Taxis
- Uber
- Bolt
- Other online taxis
- Matatus
- Buses
- Shuttles
- School buses
- Tour vans
Imana's PSV page currently lists both Comprehensive and Third Party Only options for taxis, online taxis, private-hire vehicles, matatus, buses, school buses, staff buses, shuttles and tour vans.
Comprehensive PSV may include
Depending on the policy:
- Own vehicle accidental damage
- Fire
- Theft
- Third-party liability
- Passenger liability
- Windscreen
- Towing
- Other selected benefits
Imana's PSV guidance specifically lists accidental damage, theft, fire, third-party liability, passenger legal liability, windscreen-related benefits and towing among possible Comprehensive PSV protections.
PSV Insurance:
https://imana.co.ke/psv-insurance
Uber, Bolt and Online Taxi Insurance
A vehicle carrying paying passengers through an online platform should be insured according to its actual commercial passenger use.
Imana classifies chauffeur-driven online taxis such as Uber, Bolt and similar services within its PSV Motor Insurance categories.
A private motor certificate should not be selected merely because:
- The car is privately owned
- Taxi work is part-time
- The driver operates only on weekends
The actual use is what matters.
School Bus Insurance in Kenya
School buses carry a particularly sensitive passenger risk: children and students.
Appropriate School Bus Insurance should consider:
- Correct vehicle classification
- Seating capacity
- Passenger liability
- Driver requirements
- Comprehensive or Third Party cover
- Inspection and regulatory requirements
Imana currently lists School Bus among its Motor Insurance classes and includes school buses within its PSV bus offerings.
Schools should also consider complementary covers such as:
- Student Personal Accident
- WIBA for employees
- Group Personal Accident
- Public Liability
Motor Insurance protects the vehicle and motor-related liabilities; it should not be treated as the school's complete insurance programme.
Motorcycle Insurance in Kenya
Motorcycle Insurance may be arranged for:
- Private motorcycles
- Commercial motorcycles
- Delivery motorcycles
- PSV boda bodas
Imana's Motor Insurance page specifically recognises private, commercial and PSV motorcycle classes.
The correct classification matters.
A motorcycle used for boda boda passenger transport should not be presented as being used only privately.
Motorcycle Insurance:
https://imana.co.ke/motorcycle-insurance
Tuk-Tuk Insurance in Kenya
Tuk-Tuks may be used for:
- Private purposes
- Commercial carriage
- Passenger transport
The appropriate policy depends on actual use.
Imana lists Tuk-Tuk Insurance among its dedicated Motor Insurance product classes and also allows Tuk-Tuk selection through its motor quotation form.
A passenger Tuk-Tuk should have the correct passenger-service classification rather than being insured under an inappropriate private class.
Tour Van and Safari Vehicle Insurance
Tour-service vehicles frequently operate:
- Over long distances
- In national parks
- On rural roads
- Across international borders
- With passengers and luggage
Tour-service vehicle insurance may therefore require consideration of:
- Passenger liability
- Vehicle modifications
- Road rescue
- Comprehensive protection
- Cross-border extensions
- COMESA Yellow Card
Imana includes Tour Service Vehicles among its Motor Insurance categories and shuttles and tour vans within its PSV offerings.
Duty-Free Motor Insurance in Kenya
Duty-free vehicles may be used by qualifying:
- Diplomats
- Embassies
- International organisations
- Development agencies
- Expatriates under appropriate arrangements
Insurance underwriting may consider:
- Duty-free registration status
- Vehicle ownership
- Diplomatic or organisational documentation
- Vehicle value
- Intended use
- Driver eligibility
The insurance should reflect the vehicle's actual status and value.
Duty-free status does not eliminate the need for appropriate Motor Insurance.
MyKava's published insurance guidance specifically addresses insurance for private individuals, expatriates and organisations in areas such as Gigiri, Runda, Muthaiga, Kitisuru, Nyari, Rosslyn, Loresho and Village Market, and includes motor and COMESA-related solutions.
Expat Motor Insurance in Kenya
Expatriates living or working in Kenya may own:
- Locally registered vehicles
- Duty-free vehicles
- Employer-provided vehicles
- Temporarily imported vehicles
The appropriate insurance depends on:
- Registration
- Ownership
- Vehicle value
- Residency arrangement
- Intended use
- Territorial requirements
An expatriate travelling regularly across East Africa should also consider:
- COMESA Yellow Card
- Territorial extensions
- Road rescue
- Travel Insurance
MyKava's published material identifies expatriates among the clients it serves with motor and other insurance solutions.
One-Month Motor Insurance in Kenya
Some vehicle classes and insurers may offer short-term or one-month Motor Insurance, particularly under Third Party arrangements.
Short-term cover may be useful where:
- A vehicle will operate for a limited period.
- A vehicle is being prepared for sale.
- A PSV is temporarily returning to operation.
- The motorist needs interim protection before annual renewal.
- A seasonal vehicle is being used temporarily.
Availability depends on:
- Vehicle class
- Insurer
- Period requested
- Underwriting requirements
Short-term insurance should not be confused with annual insurance paid by instalments.
Short-term policy
The policy itself expires after the selected short period.
Annual policy paid by instalments
The policy may run for twelve months while premium payments are made under agreed terms.
Repeated one-month purchases may also cost more over a full year than annual cover.
Always compare both options.
Private vs Commercial Motor Insurance
One of the most important Motor Insurance rules is:
Declare the vehicle's actual use.
Private Motor Insurance
Generally designed for:
- Personal use
- Family use
- Social and domestic activities
Commercial Motor Insurance
May apply to:
- Delivery vehicles
- Trucks
- Pickups
- Business-use vans
- Goods-carrying vehicles
Imana expressly distinguishes private vehicles from commercial vehicles and passenger-service vehicles in its Motor Insurance classifications.
A vehicle insured under the wrong use may create serious problems during claims.
Documents Required for Motor Insurance
A quotation may require:
- National ID or passport
- KRA PIN
- Vehicle logbook or eLogbook
- Registration number
- Make and model
- Year of manufacture
- Vehicle value
- Seating capacity
- Intended use
- Existing insurance
- Claims history
For Comprehensive cover, you may additionally require:
- Vehicle valuation
- Inspection
- Photographs
PSV or commercial risks may require additional regulatory or operational documents.
Imana's PSV process identifies logbook, KRA PIN and National ID/passport among the documents used when arranging PSV cover.
How to Compare Motor Insurance Quotations
Do not compare only:
Insurer A – KSh X
versus
Insurer B – KSh Y
Compare:
- Type of policy
- Vehicle value
- Basic excess
- Young-driver excess
- Theft excess
- Excess Protector
- PVT
- Windscreen limit
- Courtesy car
- Road rescue
- Passenger liability
- Territorial limits
- COMESA options
- Claims process
- Repair-garage conditions
- Optional extensions
The premium is only one part of the decision.
The cheapest quotation can become expensive when a claim exposes what was left out.
How to Get a Motor Insurance Quote Through Imana
Imana's motor quotation platform allows customers to select:
- Private Car
- Commercial Vehicle
- PSV
- Motorbike
- Tuk-Tuk
and choose:
- Comprehensive
- Third Party
- Third Party Fire & Theft.
Motor quotation
https://imana.co.ke/motor-quote
Motor Insurance information
https://imana.co.ke/insurance/motor-insurance
PSV Insurance
https://imana.co.ke/psv-insurance
Motorcycle Insurance
https://imana.co.ke/motorcycle-insurance
COMESA Yellow Card
https://imana.co.ke/comesa-insurance
Claims
https://imana.co.ke/claims-request
Why Use an Insurance Intermediary for Motor Insurance?
Motor Insurance is much more than obtaining a certificate.
An intermediary can help you:
- Identify the correct vehicle class.
- Obtain quotations.
- Compare premiums and benefits.
- Understand excesses.
- Check valuation requirements.
- Review extensions.
- Coordinate policy issuance.
- Support claims.
- Review cover before renewal.
Imana's Motor Insurance page states that the agency helps customers compare multiple Motor Insurance quotations and provides digital-certificate and claims-support services.
Motor Insurance in Westlands, Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Imana's official website confirms its office at Krishna Centre, 4th Floor, Woodvale Grove, Westlands.
Websites
Imana Insurance Agency Kenya Ltd
https://imana.co.ke
MyKava Travel & Insurance
https://mykava.co.ke
Frequently Asked Questions About Motor Insurance in Kenya
Is Motor Insurance compulsory in Kenya?
Applicable third-party Motor Insurance is compulsory for vehicles used on Kenyan roads under the Motor Vehicles Third Party Risks framework.
What is the difference between Comprehensive and Third Party Insurance?
Third Party Insurance primarily protects against eligible liability to others.
Comprehensive Insurance additionally provides own-vehicle protection against specified risks such as accidental damage, theft and fire.
How much does Motor Insurance cost in Kenya?
The cost depends on the type of cover, vehicle class, value, use, insurer, claims history and selected benefits.
Is Comprehensive Insurance priced according to vehicle value?
Vehicle value is an important underwriting factor. Imana's motor quotation form requests the proposed car value when preparing Comprehensive and other quotations.
What is Excess Protector?
It is an optional extension that may protect against specified policy excesses.
What is PVT?
PVT means Political Violence and Terrorism protection and may be purchased as an extension where available.
Do I need a vehicle valuation?
Comprehensive insurers may require valuation to confirm the vehicle's reasonable insured value.
Does Comprehensive Insurance include windscreen cover?
It may, subject to the insurer's windscreen limit, excess and policy terms.
Does Comprehensive Insurance include a courtesy car?
Not automatically. Check whether the benefit is included or available as an extension.
What is road rescue?
Road rescue may provide towing and other roadside assistance within stated limits.
Do I need COMESA Insurance when driving outside Kenya?
A COMESA Yellow Card may be required or useful for recognised third-party protection when driving into participating jurisdictions.
Can Uber and Bolt vehicles use private Motor Insurance?
They should be insured under the appropriate commercial passenger or PSV category. Imana categorises chauffeur-driven online taxis under PSV Motor Insurance.
Can school buses obtain Comprehensive Insurance?
Yes, subject to underwriting. Imana identifies school buses within its Motor and PSV classes.
Can motorcycles get Comprehensive Insurance?
Availability depends on the insurer, vehicle and use. Motorcycle policies may also be arranged on Third Party terms.
Can I insure a Tuk-Tuk?
Yes. Imana lists Tuk-Tuk Insurance among its Motor Insurance offerings.
Is one-month Motor Insurance available?
Short-term Motor Insurance may be available for selected vehicle classes and insurers. Confirm the exact duration, class and benefits before purchase.
Does Imana help with motor claims?
Yes. Imana provides an online claim-notification facility that accepts Motor Insurance claims and collects accident and policy information.
The Bottom Line
Motor Insurance in Kenya should be selected according to:
- Vehicle value
- Vehicle class
- Actual use
- Passenger exposure
- Financial ability to absorb loss
- Territorial requirements
- Desired benefits
The policy should also be reviewed for:
- Excess
- Excess Protector
- PVT
- Vehicle valuation
- Windscreen cover
- Courtesy car
- Road rescue
- Claims procedure
- COMESA Yellow Card
Special vehicle classes such as:
- PSVs
- School buses
- Motorcycles
- Tuk-Tuks
- Tour vehicles
- Duty-free vehicles
- Expat vehicles
require insurance that accurately reflects their use and circumstances.
Before purchasing Motor Insurance, ask yourself:
If my vehicle is damaged, stolen or involved in a serious accident tomorrow, do I understand exactly what this policy will and will not pay?
If the answer is no, do not compare premium alone.
Compare the whole policy.
Compare Motor Insurance Quotations with Imana
Imana Insurance Agency Kenya Ltd helps individuals, businesses and fleet owners understand and compare suitable Motor Insurance options.
Learn. Compare. Get a Quote. Buy. Claim. Renew—with Imana.
Physical Office:
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Website:
https://imana.co.ke
MyKava:
https://mykava.co.ke
Motor Insurance:
https://imana.co.ke/insurance/motor-insurance
Get a Motor Quote:
https://imana.co.ke/motor-quote
Report a Claim:
https://imana.co.ke/claims-request
Author:
Raymond Momanyi – Founder & CEO, Imana Insurance Agency Kenya Ltd
Compare the premium. Understand the benefits. Declare the correct vehicle use. Insure wisely.
Motor Insurance premiums, vehicle-age requirements, excesses, extensions, short-term availability, valuation rules and underwriting conditions vary between insurers and vehicle classes. Obtain a current written quotation, policy schedule and full policy wording before purchasing cover.