
Blog Details
Diskava. Beta. Kava
13Aug
Excess vs Contribution in Motor Insurance Kenya Explained
Understand the difference between excess and contribution in motor insurance claims in Kenya, including basic excess, excess protector, underinsurance, betterment and claim deductions.
Do You Know the Difference Between Excess and Contribution in Motor Insurance?
Buying Comprehensive Motor Insurance does not necessarily mean that every admissible claim will be settled at 100% with no amount payable by the policyholder.
Two terms that can cause considerable confusion during motor claims are:
- Excess
- Contribution
They are related to claim settlement, but they do not mean the same thing.
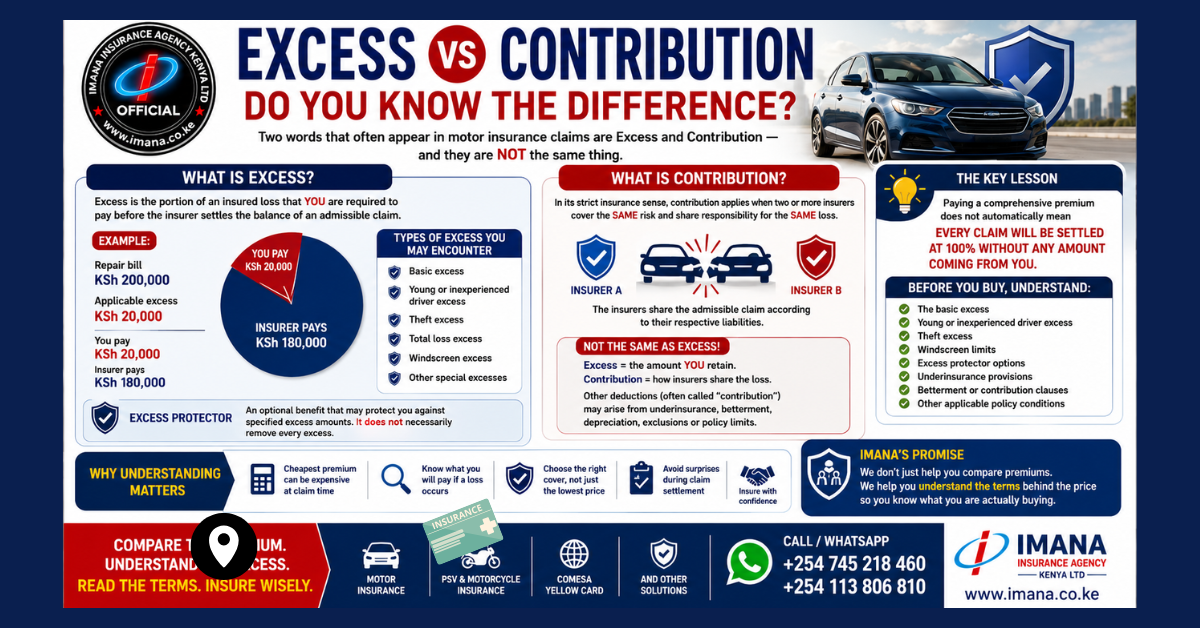
An excess is normally an amount or percentage of an insured loss that remains payable by the policyholder before or as part of the insurer's settlement.
Contribution, in its strict insurance-law meaning, normally concerns situations where two or more insurers cover the same insured interest against the same risk and therefore share responsibility for an admissible loss.
Motorists may also hear the word “contribution” used more loosely when they are asked to meet part of a repair bill because of:
- Underinsurance
- Betterment
- Depreciation
- Uninsured items
- Policy limits
- Other claim conditions
Those deductions should be distinguished from the formal insurance principle of contribution.
The important lesson is simple: Comprehensive Insurance can provide broad protection, but policy excesses, limits, exclusions and other claim deductions can still affect the amount ultimately paid.
What Is an Insurance Excess?
An insurance excess is the portion of an admissible claim that the insured is responsible for paying under the policy.
The excess is normally specified in:
- The quotation
- Policy schedule
- Motor-policy wording
- Endorsements
- Excess schedule
A motor policy may express the excess as:
- A fixed amount
- A percentage of the claim
- A percentage of the vehicle's value
- A percentage subject to a minimum amount
The actual calculation depends on the policy.
Kenyan insurers openly incorporate excesses into Comprehensive Motor Insurance products. For example, Britam states that its Comprehensive Motor policy compensates specified losses subject to an excess and also offers Excess Protector as an optional motor benefit. (Britam)
Example of How a Motor Insurance Excess Works
Assume your insured vehicle is involved in an accident.
The admissible repair cost is:
KSh 200,000
Your applicable policy excess is:
KSh 20,000
Subject to the policy terms and any other applicable deductions:
- You contribute: KSh 20,000
- Insurer considers: KSh 180,000
This is why a motorist should understand the excess before purchasing the policy—not after an accident.
The lowest premium may sometimes come with a less favourable excess structure.
Why Do Insurance Policies Have an Excess?
An excess means the policyholder retains a small portion of the insured risk.
It can help:
- Reduce very small claims
- Encourage reasonable risk management
- Reduce claims-administration costs
- Influence the premium charged
- Share a defined portion of loss between insurer and insured
A higher voluntary excess may sometimes reduce the premium, while a lower excess can make the policy more expensive.
This varies between insurers.
Different Types of Motor Insurance Excess in Kenya
A motor policy may contain more than one type of excess.
That is why asking simply, “What is the excess?” may not be enough.
1. Basic Excess
The basic excess is the standard amount payable by the policyholder when making an eligible own-damage claim.
For example:
- Collision
- Accidental damage
- Overturning
The calculation is stated in the policy.
2. Young Driver Excess
A higher or additional excess may apply where the vehicle was being driven by a person below the age specified in the policy.
For example, a policy may distinguish between:
- Drivers over a specified age
- Drivers below that age
Do not assume that every authorised driver attracts the same excess.
3. Inexperienced Driver Excess
Some insurers apply an additional excess where the driver has held a licence for less than the minimum period stipulated in the policy.
This can apply even if the driver is legally licensed.
Ask:
- What qualifies as an inexperienced driver?
- Does this excess apply in addition to the basic excess?
- Can it be protected by Excess Protector?
4. Theft Excess
Theft claims may carry a separate excess.
This is especially important for:
- High-theft-risk vehicles
- Commercial vehicles
- Vehicles without required tracking devices
- Theft involving keys or security conditions
A theft excess may differ substantially from the accidental-damage excess.
5. Total-Loss Excess
Some policies may apply specific conditions or excesses following:
- Vehicle theft
- Constructive total loss
- Actual total loss
The insured should confirm how total-loss claims are calculated.
6. Windscreen Excess
Windscreen protection may have:
- A separate annual limit
- A separate excess
- A maximum amount payable
Do not assume that the vehicle's full Comprehensive sum insured applies to windscreen damage.
What Is Excess Protector?
Excess Protector is an optional motor-insurance extension designed to protect the policyholder against specified excess amounts that would otherwise be payable after an admissible claim.
It is widely available as an optional motor benefit in Kenya. Britam, for example, lists Excess Protector alongside Political Violence and Terrorism, Loss of Use and Personal Accident benefits in its motor quotation system. (Britam)
However:
Excess Protector does not necessarily remove every excess contained in the policy.
Some policies may exclude or restrict protection for:
- Young-driver excess
- Inexperienced-driver excess
- Theft excess
- Total-loss excess
- Certain commercial vehicles
- Specific claim circumstances
Always request confirmation of exactly which excesses the extension protects.
What Is Contribution in Insurance?
In the strict insurance sense, contribution applies where the same risk is insured under more than one policy and more than one insurer could be responsible for the same loss.
Insurance is based on the principle of indemnity: an insured person should generally be restored to the financial position they occupied before the loss, rather than profit from it.
If the same vehicle or property were insured against the same loss by two insurers, the policyholder should not normally collect the full loss twice.
Instead, the insurers may share the admissible claim according to their respective liabilities.
Example
Suppose an asset is properly insured against the same risk under two applicable policies.
An admissible loss occurs.
Rather than:
- Insurer A paying the full loss and
- Insurer B paying the full loss again,
the insurers may contribute their appropriate shares.
That is the classic principle of contribution.
Contribution Is Not the Same as Excess
This distinction is crucial.
Excess
The policyholder is contractually required to bear part of the loss.
Contribution
Two or more insurers may share responsibility for the same insured loss.
Therefore:
Excess concerns the amount retained by the insured. Contribution primarily concerns how overlapping insurers share an indemnity loss.
Why Do Motorists Sometimes Call Other Claim Deductions “Contribution”?
In everyday claims conversations, a motorist may be told:
“You will need to contribute something toward the repairs.”
That amount may not technically arise from the insurance doctrine of contribution.
It could arise from:
- Underinsurance
- Betterment
- Depreciation
- Wear and tear
- Uninsured improvements
- Policy limits
- Applicable excess
Understanding the reason for the deduction matters because each operates differently.
What Is Underinsurance?
Underinsurance occurs when an asset is insured for less than its appropriate value.
For example, assume a vehicle's reasonable insurable value is:
KSh 4,000,000
but it is insured for:
KSh 2,500,000
The vehicle may be significantly underinsured.
Depending on the policy wording, this can affect a partial-loss settlement through an average condition.
The insured may therefore have to meet part of the repair cost.
This is not the same thing as the basic policy excess.
How the Average Clause Can Affect a Claim
A simplified illustration can help.
Suppose:
- Correct value of vehicle: KSh 4,000,000
- Sum insured: KSh 3,000,000
- Admissible damage: KSh 400,000
The vehicle was insured for only 75% of its appropriate value.
Where an average condition applies, the insurer may calculate its responsibility proportionately before other applicable deductions.
The precise calculation depends on the policy wording and claim assessment.
This demonstrates why intentionally lowering a vehicle value to obtain a cheaper premium can become costly during a claim.
Why Vehicle Valuation Matters
For Comprehensive Motor Insurance, an accurate vehicle valuation helps establish an appropriate sum insured.
A professional valuation may record:
- Current market value
- Make and model
- Year of manufacture
- Mileage
- Vehicle condition
- Existing damage
- Accessories
- Modifications
- Chassis and engine details
An incorrect value creates two different problems.
Underinsurance
The insured value is too low.
This can result in:
- Inadequate total-loss settlement
- Possible application of average
- A larger amount being borne personally
Overinsurance
The vehicle is insured above its reasonable value.
Paying premium on an inflated amount does not normally entitle the policyholder to profit from a claim.
The purpose of indemnity insurance is to compensate for an insured loss—not create a financial gain.
What Is Betterment?
Betterment arises when repairing damaged property would leave the policyholder in a materially better position than immediately before the accident.
This can occur when an old or substantially worn component is replaced with a completely new one.
For example:
A vehicle has a significantly worn component immediately before an accident.
The accident damages the component.
Repair requires fitting a brand-new replacement.
Depending on the policy and circumstances, the insurer may require the insured to meet part of the cost representing the improvement in value.
This is sometimes informally called a “contribution.”
Technically, however, it is more accurately described as a betterment adjustment.
Betterment vs Excess
The two should not be confused.
Excess
Exists because the insurance contract says the insured retains a specified part of an admissible claim.
Betterment
May arise because the repair improves the asset beyond its pre-loss condition.
It is therefore possible for a claim to involve:
- An excess
- A betterment deduction
at the same time.
The exact treatment depends on the policy wording.
What About Depreciation?
Depreciation reflects the reduction in an asset's value due to:
- Age
- Usage
- Wear
- Market conditions
A claim involving replacement parts or a total loss may be affected by how the policy values the asset.
Depreciation is not automatically the same as:
- Excess
- Contribution
- Betterment
These concepts should be considered separately.
A Practical Motor Claim Example
Suppose a Comprehensive Motor Insurance claim has an assessed repair cost of:
KSh 300,000
Potential claim adjustments could include:
Basic excess
KSh 20,000
Betterment
KSh 15,000 for specified replacement components, where applicable under the policy
Uninsured item
KSh 10,000 for an accessory not included in the insurance
The policyholder could therefore have to meet more than the basic excess.
This does not mean Comprehensive Insurance has failed.
It means the settlement is being calculated according to the agreed policy.
That is why understanding the policy before buying it matters.
Does Comprehensive Motor Insurance Pay 100% of Every Claim?
No.
“Comprehensive” describes the broad class of motor protection. It does not mean there can never be deductions.
A Comprehensive policy may provide protection against:
- Accidental damage
- Theft
- Fire
- Third-party liability
- Other insured risks
Kenyan Comprehensive Motor products also commonly make claims subject to an excess. (Britam)
A settlement may still be affected by:
- Excess
- Policy limits
- Underinsurance
- Betterment
- Excluded items
- Uninsured accessories
- Breach of policy conditions
- Depreciation where applicable
- Previous unrepaired damage
- Other endorsements
Does Excess Apply to Every Motor Claim?
Not necessarily.
The applicable excess depends on:
- Type of claim
- Policy
- Insurer
- Vehicle class
- Driver
- Extensions purchased
For example:
- Accidental damage may carry one excess.
- Theft may carry another.
- Windscreen claims may have separate treatment.
- Third-party claims may operate differently.
Read the schedule rather than assuming one excess applies to everything.
Can Excess Protector Make My Claim Completely Free?
Not necessarily.
An Excess Protector may pay specified excesses but still exclude others.
Before buying it, ask:
- Does it protect the basic accidental-damage excess?
- Does it protect young-driver excess?
- Does it protect inexperienced-driver excess?
- Does it protect theft excess?
- Does it protect total-loss excess?
- Does it apply to every authorised driver?
- What exclusions apply?
Do not buy an extension based only on its name.
Can I Avoid Underinsurance by Increasing the Vehicle Value?
The goal should not be to choose the highest possible value.
The goal is to choose an accurate value.
Insuring a KSh 3 million vehicle for KSh 5 million does not mean an insurer will automatically pay KSh 5 million after a total loss.
Similarly, insuring it for KSh 1.5 million just to reduce the premium can expose you to serious underinsurance.
Use a realistic value supported by professional valuation where required.
How to Read a Motor Insurance Quotation Before Buying
Before comparing premiums, check the following.
1. Basic Excess
Ask:
How much would I pay after an ordinary accidental-damage claim?
2. Young Driver Excess
Confirm the applicable age threshold.
3. Inexperienced Driver Excess
Check the minimum required driving experience.
4. Theft Excess
Determine what portion of a theft claim remains yours.
5. Excess Protector
Establish exactly which excesses are protected.
6. Windscreen Limit
Check:
- Annual limit
- Excess
- Replacement conditions
7. Vehicle Value
Ensure the sum insured reflects a reasonable current market value.
8. Average Condition
Ask what happens if the vehicle is found to have been underinsured.
9. Betterment
Find out whether replacement of worn components can result in a contribution from you.
10. Accessories
Confirm whether:
- Entertainment equipment
- Special rims
- Tracking equipment
- Modifications
- Commercial accessories
are included.
Why the Cheapest Motor Insurance Quotation Can Become Expensive
Imagine two quotations.
Quotation A
Premium: lower
But it contains:
- Higher excess
- No Excess Protector
- Smaller windscreen benefit
- No road rescue
- No Political Violence and Terrorism
- Restrictive driver conditions
Quotation B
Premium: slightly higher
But it includes broader protection and lower out-of-pocket exposure.
Quotation A may look attractive when buying the policy.
Quotation B may prove significantly more valuable when an accident happens.
Premium tells you what insurance costs before a claim. Policy terms tell you what insurance may cost you after a claim.
Questions to Ask Before Buying Comprehensive Car Insurance
Ask your insurer or intermediary:
- What is my basic excess?
- Is the excess fixed or percentage-based?
- What is the minimum excess?
- Is there a young-driver excess?
- Is there an inexperienced-driver excess?
- What is the theft excess?
- Can I buy Excess Protector?
- Which excesses does it protect?
- What windscreen limit applies?
- Is the vehicle correctly valued?
- Does an average condition apply?
- How does betterment work?
- Are accessories included?
- What happens after a total loss?
- What are the main exclusions?
Get the answers before making payment.
What to Do If You Do Not Understand a Claim Deduction
Do not simply accept the words:
“You have to contribute.”
Ask what the deduction actually represents.
Request a written claim calculation showing, where applicable:
- Assessed loss
- Approved repair amount
- Basic excess
- Additional excess
- Underinsurance adjustment
- Betterment adjustment
- Depreciation
- Uninsured items
- Amount payable by insurer
- Amount payable by policyholder
Imana has previously highlighted excess, betterment and underinsurance among issues consumers should understand when analysing delayed, reduced or disputed claim settlements. (Imana)
A clear calculation makes it easier to determine whether the deduction is consistent with the policy.
What If You Disagree With the Claim Settlement?
Start by asking the insurer or intermediary for:
- Written settlement calculation
- Relevant policy clause
- Valuation report
- Assessor's findings
- Explanation of each deduction
If the issue remains unresolved, follow the insurer's complaint-handling process.
The Insurance Regulatory Authority regulates and supervises Kenya's insurance industry and provides consumer-protection mechanisms for policyholders. (Insurance Regulatory Authority)
The Role of an Insurance Intermediary
This is one of the areas where professional insurance advice matters.
A customer should not discover the meaning of:
- Excess
- Average
- Betterment
- Policy warranties
only after an accident.
A competent intermediary should explain these terms while comparing quotations.
At Imana Insurance Agency Kenya Ltd, the objective is not merely to present customers with premium figures.
We help customers compare:
- Premiums
- Excesses
- Benefits
- Extensions
- Vehicle values
- Policy conditions
- Claims requirements
- Important exclusions
Because two Comprehensive quotations with different excess structures should not be treated as identical policies.
Compare Motor Insurance Quotations Through Imana
Imana Insurance Agency Kenya Ltd helps motorists compare:
- Comprehensive Motor Insurance
- Third-Party Only Insurance
- Third-Party Fire and Theft
- Private Motor Insurance
- Commercial Motor Insurance
- PSV Insurance
- Online Taxi Insurance
- Motorcycle Insurance
- Tour and Safari Vehicle Insurance
- Fleet Insurance
- COMESA Yellow Card
Useful Imana links
Motor Insurance:
https://www.imana.co.ke/insurance/motor-insurance
Car Insurance:
https://www.imana.co.ke/car-insurance
Compare Motor Insurance Quotations:
https://www.imana.co.ke/motor-quote
PSV Insurance:
https://www.imana.co.ke/psv-insurance
Motorcycle Insurance:
https://www.imana.co.ke/motorcycle-insurance
Report an Insurance Claim:
https://www.imana.co.ke/claims-request
Frequently Asked Questions About Excess and Contribution
What is an insurance excess?
An excess is the portion of an admissible insured loss that remains payable by the policyholder according to the policy terms.
Is excess the same as contribution?
No.
Excess is the amount retained by the policyholder.
Contribution, in its strict insurance meaning, normally involves two or more insurers sharing the same insured loss.
Why am I being asked to contribute toward a motor repair?
Ask for the specific reason. The amount could result from:
- Excess
- Underinsurance
- Betterment
- Uninsured parts
- Depreciation
- Another policy condition
Not every amount informally called a “contribution” arises from the legal doctrine of contribution.
What is Excess Protector?
It is an optional extension that may protect against specified excesses. It does not necessarily remove every excess.
Can underinsurance reduce my claim?
Yes, where the policy contains an applicable average condition or other relevant provisions. Maintaining an accurate insured value is therefore important.
What is betterment in a motor claim?
Betterment occurs where repairing or replacing damaged property improves it beyond its pre-loss condition. The policyholder may sometimes be required to meet the improvement element.
Does Comprehensive Insurance mean I will never pay anything after an accident?
No. Comprehensive policies may still contain excesses, limits, exclusions and other deductions.
Does every insurer have the same excess?
No. Excess structures vary by insurer, vehicle category and quotation.
Can I compare excesses before buying insurance?
Yes—and you should.
Premium, excess and benefits should be considered together.
The Bottom Line
Excess and contribution are not the same thing.
Excess
The portion of an admissible claim that the insured is required to bear under the policy.
Contribution
In its technical insurance sense, the sharing of an insured loss among multiple insurers covering the same risk.
Other amounts you may personally meet
These can arise from:
- Underinsurance
- Betterment
- Depreciation
- Uninsured accessories
- Policy limits
- Other terms and conditions
Therefore, before buying Comprehensive Motor Insurance, do not ask only:
“How much is the premium?”
Also ask:
“What could I still have to pay if a claim occurs?”
That question can reveal the true difference between two insurance quotations.
At Imana Insurance Agency Kenya Ltd, we help motorists understand the terms behind the price—not simply compare the headline premium.
Because the cheapest insurance quotation can become very expensive when the claim happens.
Contact Imana Insurance Agency Kenya Ltd
Call/WhatsApp: +254 745 218 460 | +254 113 806 810
Website: https://www.imana.co.ke
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Compare the premium. Understand the excess. Read the terms. Insure wisely.
Motor-insurance excesses, claim deductions, betterment provisions, average clauses and Excess Protector benefits differ between insurers and policies. Always obtain the quotation, policy schedule and complete wording applicable to your specific vehicle before purchasing cover.
Author: Raymond Momanyi, Founder & CEO, Imana Insurance Agency Kenya Ltd