
Blog Details
Diskava. Beta. Kava
08Sep
Motor Insurance Claims in Kenya: Step-by-Step Guide
Learn how to file a motor insurance claim in Kenya, including police reporting, documents, assessment, repairs, excess, theft, windscreen and total-loss claims.
A road accident, vehicle theft or damaged windscreen can be stressful. Knowing what to do immediately—and what not to do—can protect your safety, preserve important evidence and prevent avoidable delays in your motor insurance claim.
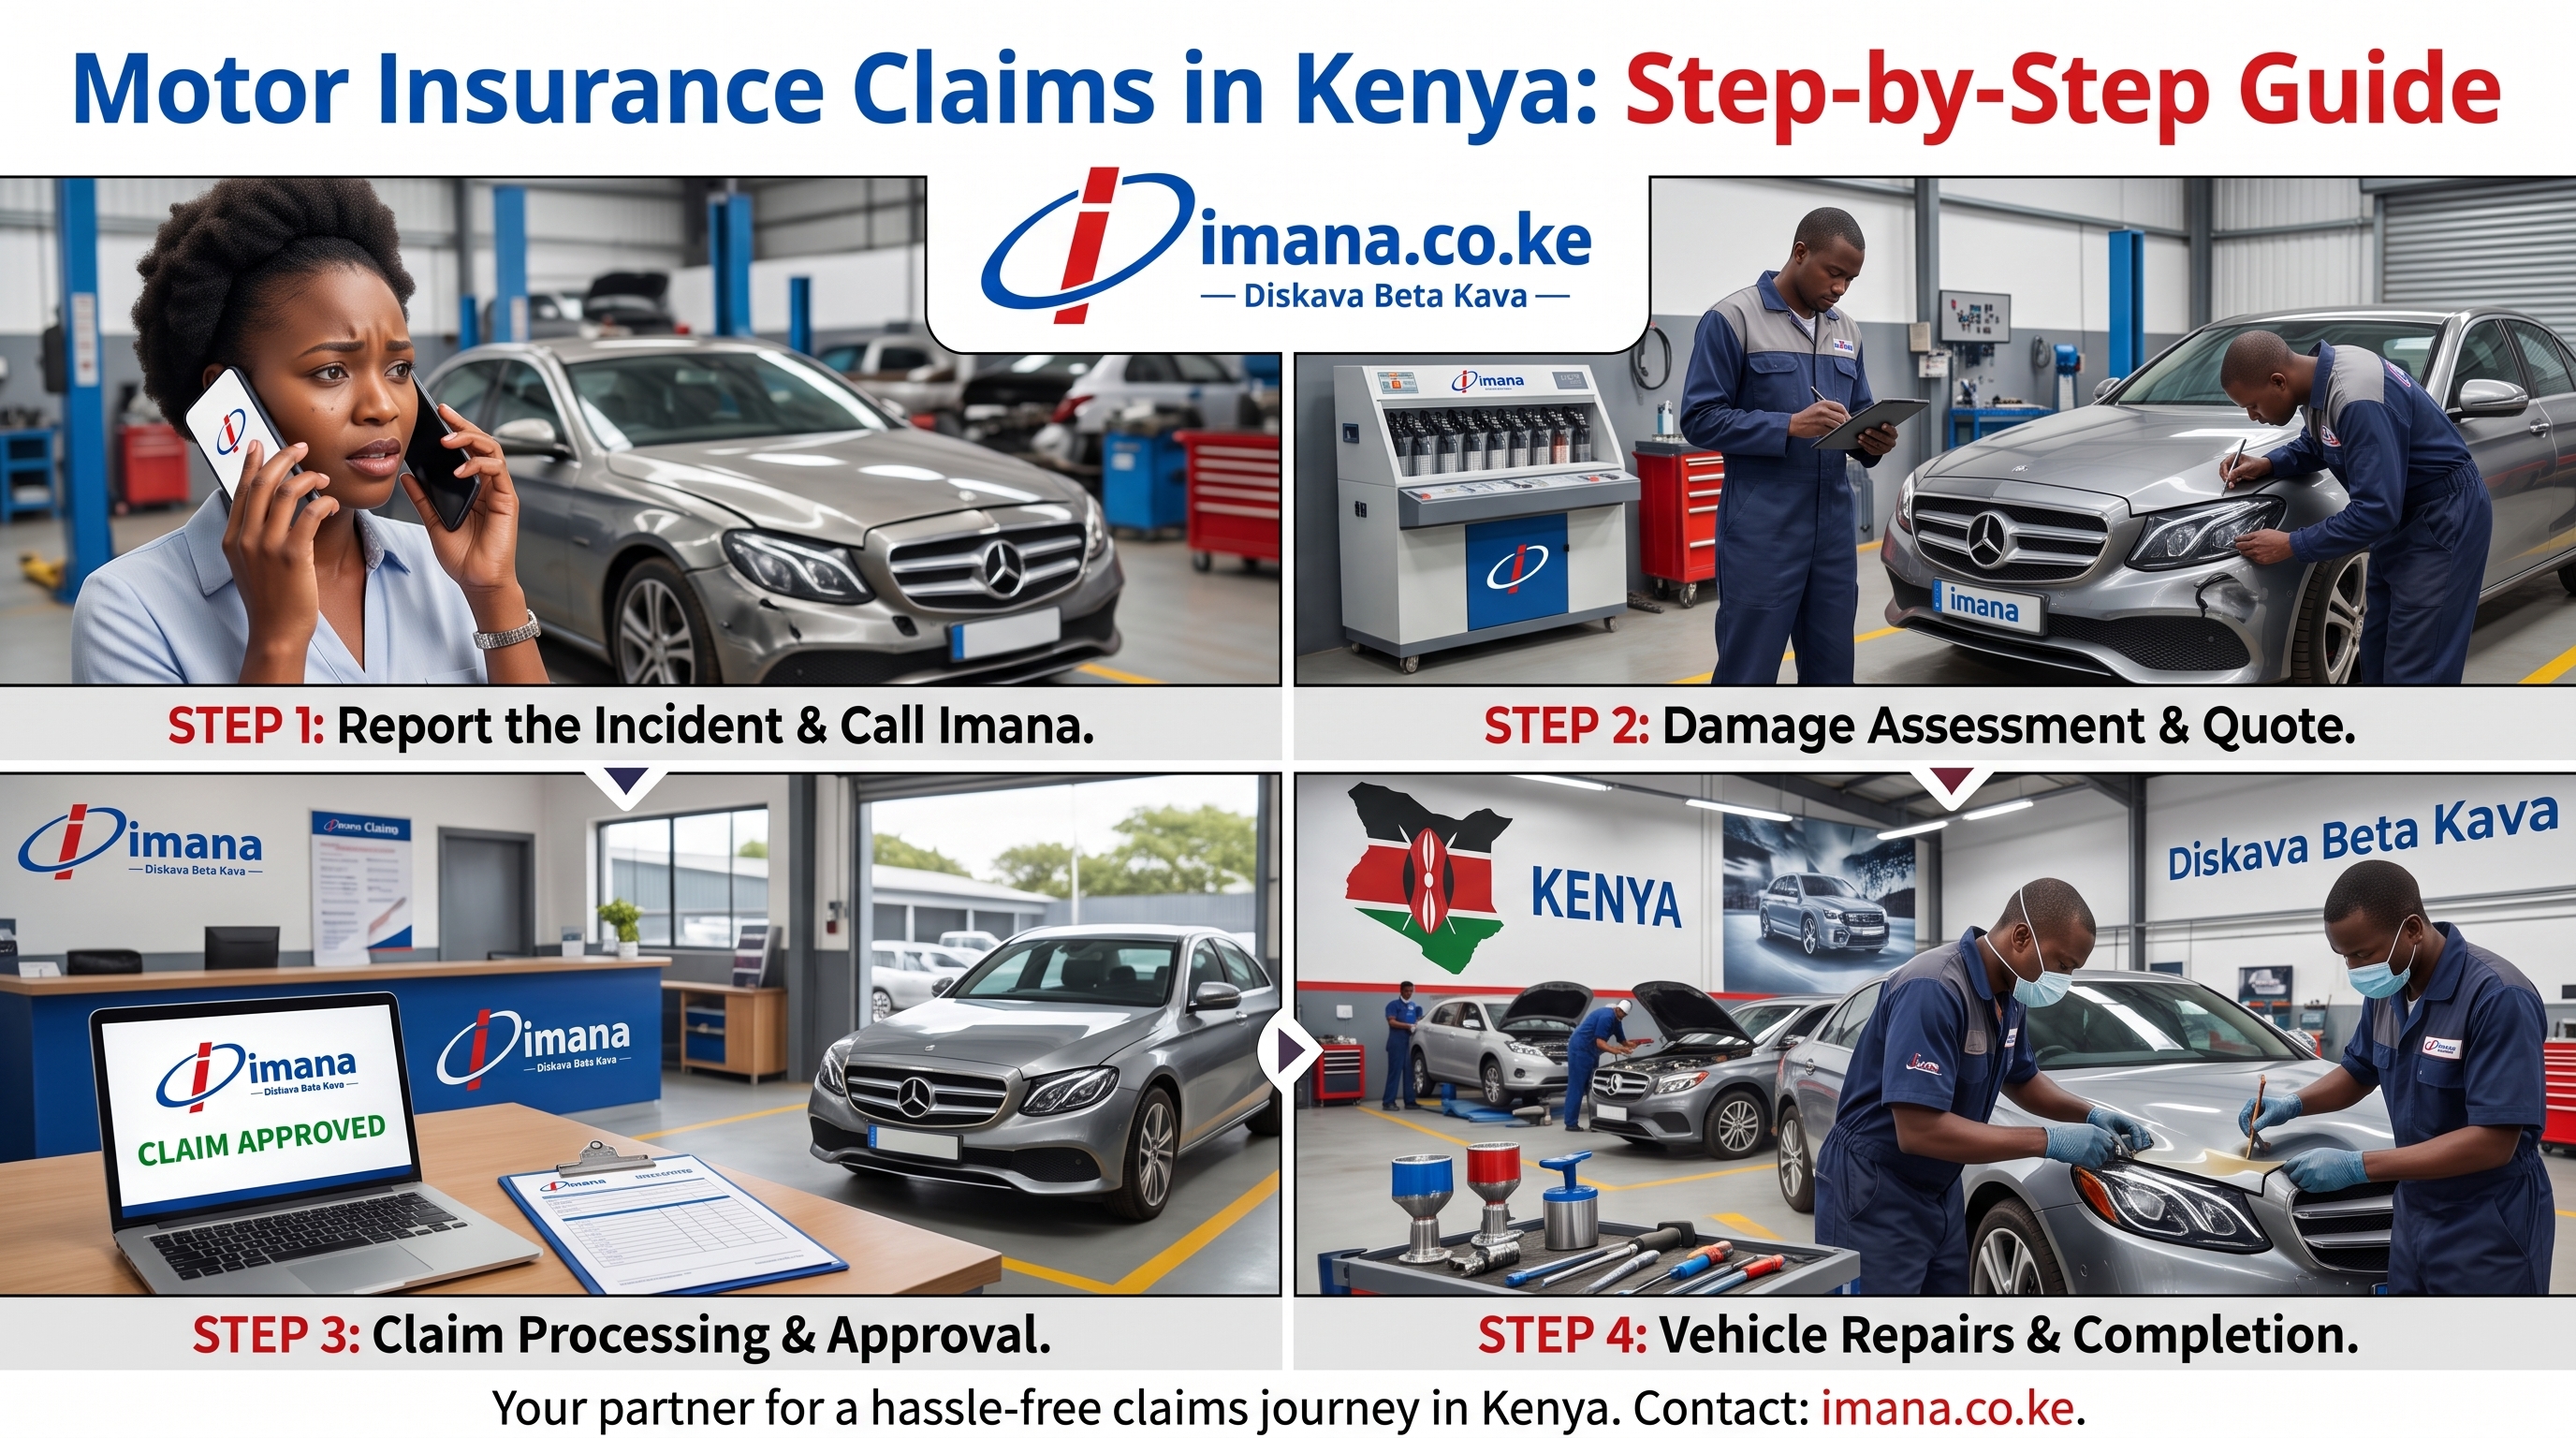
This guide explains the motor insurance claims process in Kenya, from the accident scene and police report to vehicle assessment, repairs, excess payments and total-loss settlement.
Imana Insurance Agency Kenya Ltd helps motorists compare cover from licensed Kenyan insurers, understand their policy terms and navigate claims documentation. You can request a motor insurance quotation, compare available options through the Imana Insurance quotation website or explore digital insurance options through MyKava.
Quick answer: After an accident, prioritise safety, obtain medical or emergency assistance where necessary, report the incident to the police when required, document the scene, notify your insurer or intermediary immediately and do not authorise repairs before the insurer has assessed the vehicle.
What is a motor insurance claim?
A motor insurance claim is a formal request asking an insurer to respond to an accident, theft, fire, malicious damage, windscreen breakage, third-party liability or another event covered by the policy.
Whether the insurer pays—and how the claim is settled—depends on:
- The type of motor insurance purchased
- Whether the policy was active when the incident happened
- The insured vehicle’s declared use
- The cause and circumstances of the loss
- The applicable exclusions and excesses
- Whether optional benefits were included
- The accuracy and completeness of the claim documents
A comprehensive policy may cover accidental damage to the insured vehicle, theft, fire and third-party liability, subject to its terms. Third-party-only insurance generally does not pay for damage to the policyholder’s own vehicle. Kenyan courts have similarly recognised that without comprehensive cover, an owner may have to meet the cost of repairing their own vehicle.
For a wider explanation of cover options, read Imana’s Complete Guide to Motor Insurance in Kenya.
What should you do immediately after an accident?
1. Stop and secure the scene
Stop as safely as possible. Switch on the hazard lights and, where available, place a warning triangle at a safe distance.
Do not leave the scene if anyone has been injured or if the law requires the accident to be reported.
2. Check for injuries
Check yourself, your passengers and other road users. Call emergency services when anyone is injured or trapped.
Avoid moving a seriously injured person unless leaving them in place creates an immediate danger.
3. Call the police when necessary
Contact the police immediately where:
- Someone has been injured or killed
- The accident involves pedestrians, cyclists or animals
- Several vehicles are involved
- A public service vehicle is involved
- Public property has been damaged
- A driver appears intoxicated
- A driver refuses to provide details
- The vehicles are obstructing the road
- There is disagreement about what happened
- Theft, malicious damage or suspected fraud is involved
Kenya’s Traffic Act requires an accident to be reported as soon as reasonably possible and within 24 hours where the driver has not provided the required particulars or where injury has occurred.
Even following a relatively minor accident, promptly reporting the incident and obtaining an Occurrence Book reference can create an important official record.
4. Do not admit liability
Remain calm and cooperate with the police and other parties, but do not admit fault, promise payment or negotiate a private settlement at the scene.
You may describe what happened factually. The insurer, police investigators and other authorised professionals will assess liability using the available evidence.
5. Photograph and record the scene
If it is safe, take clear photographs or videos showing:
- The vehicles before they are moved
- Vehicle registration numbers
- The points of impact
- Damage to every vehicle
- The wider road layout
- Road signs and traffic lights
- Skid marks and debris
- Weather and visibility
- Injuries or damaged property, where appropriate
Photographs do not replace a police report, but they can help the insurer, assessor or investigator understand the circumstances.
6. Exchange third-party details
Collect the other driver’s:
- Full name and telephone number
- National identification or passport details
- Driving-licence details
- Vehicle registration number
- Vehicle owner’s details
- Insurer and certificate details
- Employer or fleet-owner details, where applicable
Record the names and contacts of independent witnesses. Do not rely only on a verbal promise that the other driver will contact you later.
What is a police abstract, and is it always required?
A police abstract summarises the accident information recorded by the police. It may identify the vehicles, drivers, insurers, injuries and status of police investigations.
Insurers commonly request an abstract for accident claims, especially where third parties, injuries, theft or substantial damage are involved. Keep the police-station name, OB number, investigating officer’s details and abstract safely.
A police abstract is important evidence, but it is not automatic proof that an insurer must accept liability or pay a claim. The insurer will still examine the policy, accident circumstances, vehicle use, driver details and supporting evidence.
How quickly should you notify the insurer?
Notify your insurer or insurance intermediary immediately—or as soon as reasonably possible—after the incident.
Do not wait for:
- The police abstract to be issued
- The vehicle to reach a garage
- A third party to demand compensation
- Medical treatment to end
- Every supporting document to become available
Initial notification can usually be made before the complete claim file is submitted. Provide the missing documents as they become available.
The precise notification requirement is found in your policy. Unexplained late notification may delay an investigation and could affect the claim where the insurer has been materially prejudiced.
Imana clients can start the process through the claims request page or call/WhatsApp +254 796 209 402.
Documents commonly required for a motor claim
Requirements differ by insurer and claim type, but a motor-claim file may include:
- Completed and signed claim form
- Police abstract
- Driver’s licence
- National identity document
- Vehicle logbook or proof of ownership
- Insurance certificate or policy schedule
- Photographs of the accident and damage
- Repair estimate
- Towing receipt
- Written accident statement
- Witness or third-party details
- Inspection or assessment report
- Financier’s interest or loan-balance documents
- All vehicle keys in a theft claim
- Medical or third-party documents where injuries occurred
Submit truthful and consistent information. If you discover an error after submitting the claim, correct it promptly in writing.
Completing the motor insurance claim form
The claim form normally asks for:
- Policy and vehicle information
- Driver information
- Date, time and location of the incident
- Journey purpose
- Description of the accident
- Third-party and witness details
- Police reporting details
- Nature of the damage
- Previous accidents or claims
Avoid guesses presented as facts. If something is unknown, say so and provide it later.
The description on the claim form should be consistent with your statement, police record and photographs. Material contradictions can lead to further investigation.
Vehicle assessment and inspection
After receiving notification, the insurer may appoint a motor assessor to inspect the vehicle and determine:
- Whether the damage is consistent with the reported accident
- Which repairs are accident-related
- Whether parts should be repaired or replaced
- A reasonable repair cost
- The vehicle’s pre-accident value
- Whether repair is economical
- Whether the vehicle may be a total loss
The assessor represents the insurer’s technical assessment process. An assessment does not automatically amount to repair authority or confirmation that the claim has been admitted.
Do not dismantle or repair the vehicle before inspection unless the insurer has given written permission or urgent action is necessary to prevent further damage.
Towing after an accident
If the vehicle cannot be driven safely:
- Ask the insurer or intermediary whether an approved towing provider is available
- Confirm the destination before the vehicle is moved
- Record the towing operator’s details
- Ask for an itemised receipt
- Remove personal belongings where safe
- Photograph the vehicle before towing
Reasonable towing or recovery costs may be covered under some comprehensive policies, subject to limits and approval. Do not assume every towing or storage charge will be reimbursed.
Panel garages and your preferred repairer
Many insurers maintain networks of approved or panel garages. Using a panel garage may simplify assessment, repair approval, spare-parts discussions and payment.
If you prefer another garage, obtain the insurer’s written approval first. The insurer may:
- Approve the garage
- Request alternative quotations
- Limit payment to an assessed amount
- Ask you to meet any difference
- Decline unauthorised repair costs
Ask who is responsible for the repair warranty and what happens if defects appear after collection.
Repair authority
Repair authority is the insurer’s approval for specified repair work to begin.
Do not confuse:
- Delivering the vehicle to a garage
- Receiving an assessor’s inspection
- Obtaining a repair estimate
- Receiving formal repair authority
These are separate stages. Before work begins, confirm in writing:
- The approved repair scope
- The approved garage
- Your excess contribution
- Whether any damage is excluded
- Whether betterment or depreciation applies
- Whether parts are available
- The anticipated repair period
What is a motor insurance excess?
An excess is the portion of an admissible claim that the policyholder must pay or bear.
Different excesses may apply depending on:
- The vehicle class
- Driver age or experience
- Theft
- Unidentified third-party damage
- Windscreen claims
- Young or unnamed drivers
- The circumstances of the accident
For example, if approved repairs cost KSh 200,000 and an applicable excess of KSh 20,000 applies, the insured may be responsible for KSh 20,000 while the insurer meets the approved balance, subject to the policy.
Read Imana’s detailed guide: The Power of an Excess Protector.
How does Excess Protector work?
Excess Protector is an optional benefit designed to pay certain excesses that would otherwise be borne by the policyholder.
It does not necessarily remove every excess in every situation. The benefit may exclude or limit:
- Theft excess
- Young or inexperienced-driver excess
- Claims involving an unidentified third party
- Claims arising from excluded vehicle use
- Specific compulsory excesses
- Losses outside the policy terms
Confirm which excesses are protected before purchasing or renewing your policy. Imana’s archive also explains Excess Protector in comprehensive motor insurance.
Political Violence and Terrorism claims
Standard comprehensive motor insurance may not automatically cover loss caused by political violence, terrorism, riots or related disturbances. Protection normally depends on whether the relevant extension was purchased and active.
If your vehicle is damaged during such an event:
- Move away from danger.
- Report the incident to the police.
- Notify the insurer immediately.
- Photograph the vehicle and surrounding area when safe.
- Preserve reliable information about the event.
- Do not repair the vehicle before assessment and approval.
The insurer will determine whether the incident falls within the purchased extension and whether any exclusions apply.
How to file a motor-theft claim
When a vehicle is stolen:
- Report the theft to the police immediately.
- Obtain an OB number and the investigating officer’s details.
- Notify the insurer or intermediary without delay.
- Provide the logbook, keys, policy documents and identification requested.
- Give accurate information about the vehicle’s location, security devices and last authorised user.
- Cooperate with police and insurer investigations.
- Notify the financier if the vehicle is under finance.
The insurer may wait for the police investigation or policy-defined recovery period before considering settlement. Missing keys, inconsistencies, undisclosed vehicle use or inaccurate security information may require further investigation.
How to file a windscreen claim
For a damaged windscreen or window:
- Photograph the damage
- Notify the insurer before replacement
- Confirm the applicable windscreen limit
- Ask whether an approved supplier must be used
- Obtain approval or a claim reference
- Keep the invoice and payment receipt
- Pay any applicable excess
If the replacement cost exceeds the insured windscreen limit, the policyholder may have to pay the difference.
When is a vehicle treated as a total loss?
A vehicle may be declared a total loss when:
- It cannot be repaired safely
- It has been stolen and not recovered
- The repair cost is uneconomical compared with its pre-accident value
- Structural or other damage makes repair impractical
A total-loss settlement is not automatically equal to the figure printed as the sum insured.
Depending on the policy, settlement may consider:
- The vehicle’s pre-loss market value
- The policy’s valuation basis
- The sum insured
- Applicable excesses
- Outstanding premium
- Salvage arrangements
- Underinsurance
- The financier’s interest
Ask for the valuation and settlement calculation in writing. Remove the vehicle from your policy or transfer cover only after receiving the insurer’s instructions.
What happens when the vehicle is financed?
Where a bank, SACCO, asset-finance company or other lender has a noted financial interest, the insurer may have to involve that institution in the settlement.
In a total-loss claim:
- The financier may be paid first
- The outstanding loan balance may be deducted
- Any remaining admissible amount may be paid to the insured
- The insured may still owe the financier if the settlement is below the outstanding balance
Provide the insurer with the financier’s letter, discharge requirements and current loan balance promptly.
What if the other driver is uninsured?
If you have comprehensive insurance, notify your own insurer and submit the claim under your policy, subject to its terms and excesses. Your insurer may later exercise recovery rights against the responsible party.
If you only have third-party cover, your policy will ordinarily not repair your own vehicle. You may need to pursue the responsible driver or vehicle owner directly.
Preserve:
- The police abstract
- Vehicle and driver details
- Photographs
- Witness contacts
- Repair estimates
- Correspondence and demand letters
Ask your insurer or legal adviser for guidance before agreeing to a private settlement.
Why are motor insurance claims delayed?
Common causes include:
- Late notification
- Incomplete documents
- Delayed police records
- Disagreement about accident circumstances
- Missing third-party information
- Repair-estimate disputes
- Spare-parts availability
- Questions about vehicle ownership or use
- Financier approvals
- Suspected fraud
- Ongoing police or investigator enquiries
- Delayed excess payment
Respond quickly to reasonable information requests and keep copies of every document submitted.
For further guidance, read Why Insurance Claims Are Delayed or Declined in Kenya.
Common reasons motor claims are declined
A claim may be declined where the loss is outside the policy or where a material condition has been breached. Examples include:
- The policy had expired or was cancelled
- Premium obligations were not met
- The vehicle was used for an undeclared purpose
- A private vehicle was being used for hire or reward
- The driver was unlicensed or excluded
- The driver was under the influence of alcohol or drugs
- The loss was intentional or fraudulent
- Material information was misrepresented
- Repairs were completed before inspection or authorisation
- The damage resulted from wear, mechanical breakdown or poor maintenance rather than an insured accident
- The loss occurred outside the territorial limits
- The vehicle was overloaded or used unlawfully
- A required extension was not purchased
A decline should be supported by the policy wording and the facts of the claim. Ask the insurer to identify the exact clause relied upon.
How to challenge a motor-claim decision
If you disagree with a delay, deduction or rejection:
- Request the decision and reasons in writing.
- Ask for the policy clause supporting the decision.
- Submit missing evidence or correct factual errors.
- Request an internal review by the insurer.
- Ask Imana Insurance Agency to help coordinate and clarify the matter.
- If unresolved, lodge a complaint with the Insurance Regulatory Authority.
The IRA accepts complaints relating to regulated insurance entities, including complaints about delays in settling payable claims.
Motor insurance claims checklist
Before submitting your claim, confirm that you have:
- Protected life and obtained emergency help
- Reported the accident to the police where required
- Obtained the OB number and police abstract
- Notified the insurer immediately
- Taken photographs
- Collected third-party and witness details
- Completed the claim form
- Provided driver and ownership documents
- Preserved towing and recovery receipts
- Avoided unauthorised repairs
- Confirmed the applicable excess
- Kept copies of every submission
How Imana supports motor insurance customers
Imana Insurance Agency Kenya Ltd can assist customers by:
- Explaining claim-notification requirements
- Providing the correct claim form and document checklist
- Coordinating communication with the insurer
- Following up on vehicle assessment
- Clarifying repair-authority and excess requirements
- Helping customers understand settlement calculations
- Escalating unresolved service concerns through the appropriate channels
- Comparing motor insurance quotations at renewal
Imana acts as an insurance intermediary. Claim admission, liability assessment and settlement remain subject to the insurer’s policy terms, assessment and applicable Kenyan law.
Compare motor insurance before your next renewal
The claims experience begins with buying the correct cover. Before renewing, check:
- The declared vehicle use
- The sum insured and current market value
- Driver restrictions
- Excess amounts
- Windscreen and entertainment-system limits
- Towing and loss-of-use benefits
- Excess Protector
- Political Violence and Terrorism extension
- Authorised-repair arrangements
- Territorial limits
Explore Imana’s Motor Insurance Authority Guide and Comprehensive Motor Insurance Price Guide.
For quotation comparison:
- Visit ImanaInsurance.com for guided quotation comparison and enquiries.
- Visit Imana.co.ke for authoritative Kenyan insurance guides and product information.
- Visit MyKava.co.ke for digital travel and insurance comparison pathways.
- Submit a motor quotation request.
Frequently asked questions about motor claims in Kenya
How long do I have to report a motor accident?
Notify your insurer immediately and follow the deadline stated in your policy. Where injury has occurred—or required particulars were not exchanged—the Traffic Act requires reporting to the police as soon as reasonably possible and within 24 hours.
Can I repair my vehicle before the insurer inspects it?
You should not begin repairs before inspection and written authority unless the insurer approves this or emergency work is required to prevent additional damage. Preserve photographs, damaged parts and receipts.
Does a police abstract guarantee payment?
No. It records information about the accident, but the insurer must still determine whether the claim falls within the policy.
Who pays the excess?
The policyholder normally pays or bears the applicable excess. An active Excess Protector benefit may pay specified excesses, subject to its terms.
Does third-party insurance repair my car?
Third-party-only insurance generally covers specified liability to other people. It does not normally cover accidental damage to your own vehicle.
Is the sum insured automatically paid after a total loss?
Not necessarily. Settlement depends on the policy’s valuation basis, pre-loss value, sum insured, excess, outstanding premium, salvage and any financier’s interest.
Can Imana approve my claim?
No. The insurer decides whether to admit and settle the claim. Imana can help customers prepare documentation, understand requirements, communicate with the insurer and follow up on progress.
Get help with a motor insurance claim or quotation
For motor claim support, policy review or quotation comparison, contact:
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands, Nairobi
Call/WhatsApp: +254 796 209 402
Websites:
- www.imanainsurance.com — quotation comparison and customer enquiries
- www.imana.co.ke — insurance authority guides and product information
- www.mykava.co.ke — digital travel and insurance comparison
Imana Insurance Agency Kenya Ltd is a Westlands-based insurance intermediary helping individuals, families and businesses compare insurance quotations from licensed Kenyan insurers across Motor, Medical, WIBA, PSV, Travel, Motorcycle, Cyber, SME/Corporate and other insurance classes.
Author: Raymond Momanyi
Founder & CEO, Imana Insurance Agency Kenya Ltd
Disclaimer: This article provides general information and does not replace the terms, conditions, exclusions or endorsements in an individual insurance policy. Claim requirements and settlement decisions vary by insurer, policy and circumstances.