
Blog Details
Diskava. Beta. Kava
30Jul
Comprehensive vs Third-Party Motor Insurance Kenya | Compare Quotes
Understand the difference between comprehensive and third-party motor insurance in Kenya. Compare protection, claims, excesses, costs and benefits before insuring your vehicle.
Understanding Your Motor Insurance Options
Every vehicle used on a public road in Kenya needs appropriate third-party insurance unless it falls within a specific legal exception.
Kenyan law prohibits a person from using—or allowing another person to use—a motor vehicle on a road without a policy or security that meets the legal requirements for third-party risks. The policy must be issued by an insurer authorised to conduct motor insurance business. (Kenya Law)
Meeting the minimum legal requirement, however, is not the same as protecting your own vehicle.
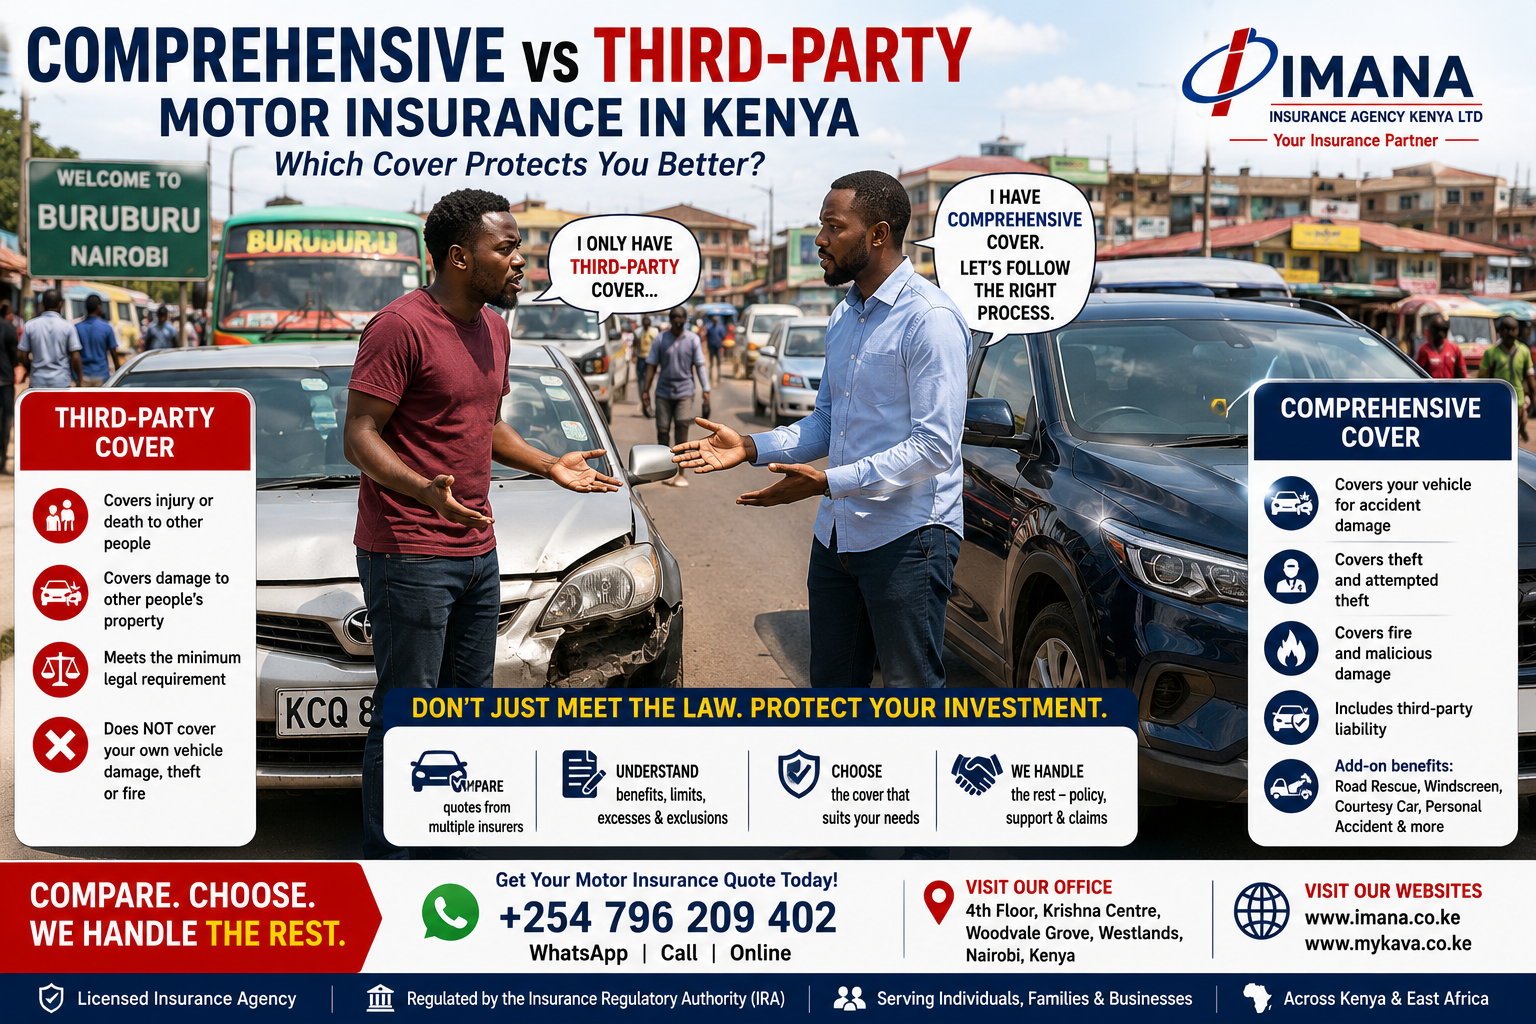
A third-party policy mainly addresses covered legal liabilities involving other people. Comprehensive motor insurance goes further by protecting the insured vehicle against specified risks such as accidental damage, fire and theft, while ordinarily retaining third-party liability protection.
The right choice depends on:
- Your vehicle’s value
- How the vehicle is used
- Your ability to pay for repairs
- Your exposure to theft and accidents
- Financing requirements
- The benefits and exclusions offered by the insurer
Before buying, compare quotations on a like-for-like basis. A low premium may look attractive today but leave you carrying most of the financial loss after an accident.
What Is Third-Party Motor Insurance?
Third-Party Only, commonly abbreviated as TPO, is the basic level of motor insurance required for vehicles operating on Kenyan roads.
Its central purpose is to protect the policyholder against specified legal liabilities arising when the insured vehicle causes injury, death or property damage to another person.
The Insurance (Motor Vehicles Third Party Risks) Act requires compliant policies to address liability arising from death or bodily injury caused by the use of a vehicle on a road, subject to the provisions and limits stated in the law. (Kenya Law)
Depending on the policy wording, third-party insurance may respond to covered claims involving:
- Injury to pedestrians
- Injury or death of occupants of another vehicle
- Damage to another person’s vehicle
- Damage to walls, gates or buildings
- Damage to roadside or public property
- Legal defence expenses authorised by the insurer
A TPO policy does not ordinarily repair or replace your own vehicle following an accident for which you are responsible.
What Does Third-Party Insurance Not Cover?
Third-party insurance generally does not cover:
- Accidental damage to your vehicle
- Theft of your vehicle
- Fire damage to your vehicle
- Windscreen damage
- Flood damage to your vehicle
- Towing and recovery for your own damage
- Theft of accessories
- Personal belongings left in the vehicle
- Your own medical expenses unless separately insured
- Mechanical or electrical breakdown
Imagine that you lose control of your car, damage another vehicle and seriously damage your own car.
A valid third-party policy may address the eligible third-party claim. However, you would ordinarily pay for the repair or replacement of your own vehicle.
That is the financial gap comprehensive insurance is intended to address.
What Is Comprehensive Motor Insurance?
Comprehensive motor insurance provides broader protection than TPO.
It normally includes the third-party liability section while adding protection for accidental loss or damage to the insured vehicle, subject to the policy terms.
A comprehensive policy may cover:
- Accidental collision damage
- Overturning
- Theft
- Fire
- Malicious damage
- Third-party bodily injury
- Third-party property damage
- Towing or recovery expenses
- Windscreen damage within an agreed limit
- Entertainment equipment within a stated limit
- Emergency medical expenses
- Personal accident benefits where included
Exact benefits differ between insurance companies. A customer should never assume that every policy marketed as comprehensive has the same extensions, limits or excesses.
Comprehensive Does Not Mean Everything Is Covered
The term comprehensive can create the impression that every vehicle-related loss will be paid.
That is not correct.
Comprehensive policies still contain conditions, warranties, excesses and exclusions. Common exclusions may include:
- Wear and tear
- Mechanical or electrical breakdown
- Gradual deterioration
- Tyre damage without other insured damage
- Driving without a valid licence
- Driving under the influence
- Undisclosed commercial or PSV use
- Using the vehicle outside the permitted territory
- Deliberate damage
- Fraud or material non-disclosure
- Unauthorised racing or speed testing
- War and certain political risks unless extended
- Loss of personal belongings beyond stated limits
- Existing damage present before insurance began
The policy schedule and wording—not the word “comprehensive”—determine the actual protection.
Key Differences Between Comprehensive and Third-Party Insurance
Protection for your own vehicle
Third party: Your own accidental damage is generally not covered.
Comprehensive: Your vehicle may be repaired or compensated following covered accidental damage, fire or theft.
Third-party liabilities
Both types normally provide the third-party protection required by law, subject to the policy conditions and applicable limits.
Theft and fire
Third party: Not normally covered.
Comprehensive: Normally included, subject to security requirements, excesses and policy conditions.
Premium
Third-party insurance generally costs less because it covers a narrower range of risks.
Comprehensive insurance costs more because the insurer accepts potential liability for damage or loss affecting both your vehicle and third parties.
Vehicle valuation
A valuation is not usually central to ordinary TPO cover because your vehicle’s own damage is not insured.
Comprehensive insurance normally requires an agreed or assessed vehicle value to help establish the sum insured and premium.
Excess
Third-party property claims may carry an excess depending on the policy.
Comprehensive policies normally contain excesses applicable to own damage, theft and other specified losses.
Financing requirements
A bank, SACCO, asset financier or leasing company may require comprehensive insurance because it has a financial interest in the vehicle.
Third-party insurance may not adequately protect the financier’s asset.
What Is Third Party, Fire and Theft Insurance?
Third Party, Fire and Theft sits between TPO and comprehensive cover.
It normally provides:
- Third-party liability
- Fire protection for the insured vehicle
- Theft protection for the insured vehicle
It does not generally cover ordinary accidental collision damage to your own vehicle.
For example, if the vehicle is stolen or destroyed by an insured fire, the policy may respond. If you reverse into a wall and damage the vehicle, your own repair costs may not be covered.
This option can be considered where a vehicle owner wants more protection than TPO but does not wish to purchase full comprehensive insurance.
Its availability depends on the insurer and vehicle class.
When Does Comprehensive Insurance Make More Sense?
Comprehensive cover may be appropriate when:
Your vehicle has a high replacement value
Replacing a valuable vehicle from personal savings may be financially difficult.
The vehicle is financed
A financier will ordinarily want its interest protected against damage, theft and total loss.
You rely on the vehicle daily
A serious accident could disrupt work, family transport or business operations.
The vehicle has a significant theft exposure
Comprehensive cover may provide theft protection, subject to security warranties and exclusions.
You cannot comfortably fund major repairs
A damaged bumper may be manageable. Structural damage, airbags, electronics and imported parts can be considerably more expensive.
The vehicle is used for business
Commercial vehicles, taxis, tour vans and fleets generate income. Their loss can affect both asset value and business operations.
You want optional extensions
Benefits such as excess protector, political violence and terrorism, road rescue and courtesy-car cover are commonly associated with comprehensive policies.
When Might Third-Party Insurance Be Considered?
TPO may be considered where:
- The vehicle has a low market value
- The owner can afford to replace or repair it
- The vehicle is used infrequently
- Comprehensive premiums are disproportionate to the vehicle’s current value
- The owner only wants to meet the minimum legal requirement
- The insurer will not offer comprehensive cover because of age or condition
Choosing third party should still be a deliberate financial decision.
Ask yourself:
If my car is stolen or badly damaged tomorrow, can I afford to replace it without insurance?
Where the answer is no, comprehensive cover may offer stronger financial protection.
How Comprehensive Motor Premiums Are Calculated
Comprehensive premiums are commonly influenced by:
- Vehicle value
- Make and model
- Year of manufacture
- Vehicle class
- Private, commercial or PSV use
- Claims history
- Driver profile
- Area of operation
- Availability of spare parts
- Repair costs
- Security features
- Optional extensions
- Applicable minimum premium
- Policy excess
An insurer may apply a percentage to the vehicle value, subject to a minimum premium and other underwriting conditions.
Two insurers can assess the same vehicle differently. That is why motorists should compare quotations instead of assuming that one rate applies across the entire market.
How Third-Party Premiums Are Calculated
TPO premiums are generally influenced by the vehicle class and liability exposure.
Relevant factors may include:
- Private or commercial use
- Passenger-carrying capacity
- PSV operations
- Taxi or ride-hailing use
- Motorcycle or boda boda use
- Goods-carrying classification
- Vehicle tonnage
- Period of insurance
- Passenger liability requirements
A private car cannot be insured correctly as a private vehicle if it is actually being used as an Uber, Bolt taxi or other passenger-carrying vehicle for hire.
The declared use must match the actual use.
Why Correct Vehicle Classification Matters
Motor insurance is priced according to usage because different activities create different risks.
Common classes include:
- Private motor
- Commercial own goods
- Commercial general cartage
- PSV taxi
- PSV matatu or bus
- Tour service vehicle
- Motorcycle private use
- Motorcycle commercial or delivery
- Boda boda
- Tuk-Tuk commercial
- Tuk-Tuk PSV
- School bus
- Tractor
- Heavy commercial vehicle
Using the wrong insurance class can affect claim settlement.
A private policy should not be treated as a shortcut for a vehicle being used commercially or to carry passengers for reward.
Understanding Motor Insurance Excess
An excess is the amount the policyholder contributes towards an approved claim.
Suppose an approved comprehensive repair claim is KSh 300,000 and the applicable excess is KSh 30,000.
Subject to the policy terms:
- The policyholder contributes KSh 30,000.
- The insurer meets the eligible balance.
Excesses may include:
- Standard own-damage excess
- Theft excess
- Young-driver excess
- Inexperienced-driver excess
- Flood excess
- Third-party property-damage excess
- Additional excess imposed by underwriting
Always compare excesses alongside the premium.
A quotation that saves KSh 5,000 in premium but increases your potential excess by KSh 50,000 may not offer better value.
What Is Excess Protector?
Excess protector is an optional extension that may reimburse or remove certain excess amounts following an eligible claim.
It does not necessarily remove every excess.
The extension may exclude:
- Young-driver excess
- Theft excess
- Claims below a stated threshold
- Certain special-perils excesses
- Breaches of policy conditions
Confirm exactly which excesses are protected before adding the benefit.
Political Violence and Terrorism Cover
Ordinary comprehensive insurance may exclude losses arising from political violence, terrorism, riots or similar events unless the appropriate extension is added.
The need for this extension depends on:
- Where the vehicle operates
- Where it is parked
- Business or travel patterns
- The insurer’s base policy wording
- Current underwriting terms
A vehicle owner should not wait until civil unrest begins before asking whether the extension exists.
Windscreen and Entertainment Limits
Comprehensive policies may include separate limits for:
- Windscreens
- Window glass
- Factory-fitted entertainment systems
- Aftermarket radios or screens
These limits are often lower than the total vehicle value.
A luxury windscreen containing cameras, sensors or heating elements may cost far more than a standard policy limit.
Compare the limit against the likely replacement cost.
Road Rescue and Courtesy-Car Benefits
Road rescue may include:
- Towing
- Recovery
- Emergency assistance
- Battery jump-start
- Tyre assistance
- Fuel delivery under specified conditions
Courtesy-car or loss-of-use benefits may provide temporary transport following an eligible claim.
These services are not identical between insurers. Compare:
- Number of allowed call-outs
- Maximum towing distance
- Geographic coverage
- Courtesy-car period
- Daily monetary limit
- Events that qualify
- Approved service providers
Does Comprehensive Insurance Cover the Driver?
Not automatically in every circumstance.
The policy’s third-party section focuses on legal liability to other people, while own-damage cover protects the vehicle.
Medical or accidental-injury benefits for the policyholder or authorised driver may require:
- Driver Personal Accident
- Personal Accident insurance
- Medical insurance
- Group Personal Accident
- WIBA, where the driver is an employee injured at work
Check whether driver and passenger personal-accident benefits are included or optional.
What Happens After an Accident Under Third-Party Cover?
Where you are responsible for an accident:
- Notify your insurer or intermediary.
- Report the accident to the police where required.
- Obtain a police abstract.
- Do not admit or negotiate liability without insurer approval.
- Forward demand letters and third-party documents immediately.
- Cooperate with the insurer’s investigation.
- Repair your own vehicle using your own funds.
The insurer assesses the third-party claim under the law and policy terms.
The claimant must provide evidence of liability and loss.
What Happens After an Accident Under Comprehensive Cover?
The general process may include:
- Notify the insurer immediately.
- Report the accident to the police where required.
- Obtain a police abstract.
- Complete a claim form.
- Submit photographs and supporting documents.
- Allow the insurer to appoint an assessor.
- Take the vehicle to an approved garage where directed.
- Pay the applicable excess.
- Authorise repairs after insurer approval.
Where another driver caused the accident, the comprehensive insurer may repair your vehicle first and later pursue recovery from the responsible party or insurer, depending on the circumstances and policy terms.
What Happens After Theft?
A comprehensive theft claim may require:
- Immediate police report
- Police abstract
- Claim form
- Vehicle logbook
- Identification documents
- KRA PIN
- All vehicle keys
- Purchase or valuation records
- Tracking information
- Financier documents
- Investigation and waiting-period compliance
Security warranties matter.
Where an insurer required an active tracking device, alarm or other security measure, failure to maintain it may affect the claim.
Total Loss and Constructive Total Loss
A vehicle may be declared a total loss where:
- It cannot be repaired safely
- Repair costs are uneconomical relative to its value
- It is stolen and not recovered
- Damage is so severe that replacement is more practical
Settlement is normally based on the policy terms, insured value, pre-loss market value and applicable deductions.
Possible deductions may include:
- Policy excess
- Outstanding premium
- Salvage value where retained
- Underinsurance
- Betterment or depreciation where applicable
- Financier’s interest
The highest figure printed on the schedule is not automatically the amount payable in every total-loss claim.
Does Comprehensive Cover Cross-Border Travel?
Ordinary Kenyan motor insurance generally applies within the territory stated in the policy.
Driving into participating regional countries may require:
- Territorial extension
- COMESA Yellow Card
- Written approval
- Additional premium
- Separate own-damage arrangements
A COMESA Yellow Card primarily provides regional third-party liability protection under the cross-border scheme; it should not automatically be treated as comprehensive own-damage cover for your vehicle. (Kenya Law)
Confirm the position before crossing the border.
Required Documents for a Motor Insurance Quote
You may be asked for:
- National ID or passport
- KRA PIN
- Vehicle logbook
- Vehicle registration number
- Make and model
- Year of manufacture
- Vehicle use
- Seating or carrying capacity
- Estimated value
- Existing policy schedule
- Claims history
- Motor valuation for comprehensive cover
- Financier details, where applicable
Commercial, PSV and specialised vehicles may require additional documentation or inspection.
Documents to Check After Buying
After payment, inspect the certificate and policy schedule carefully.
Confirm:
- Correct insured name
- Vehicle registration
- Make and model
- Cover type
- Vehicle class and usage
- Period of insurance
- Underwriting insurer
- Sum insured
- Extensions
- Excesses
- Financier’s interest
- Premium paid
Kenyan certificate rules also require action when vehicle ownership or use changes. A change of ownership or use should therefore be reported promptly to the insurer rather than assuming the existing certificate remains suitable. (Kenya Law)
Comprehensive vs Third Party: Which One Is Better?
Neither option is universally correct for every vehicle owner.
Comprehensive may be better where:
- The vehicle is valuable
- It is financed
- You depend on it for income
- Repair costs would strain your finances
- Theft exposure is significant
- You want broader benefits
Third party may be adequate where:
- The vehicle has a low value
- You can absorb your own repair or replacement loss
- The comprehensive premium is uneconomical
- You only need the legally required liability protection
The decision should reflect your ability to carry the uninsured loss.
Common Mistakes Motorists Make
Buying on premium alone
The cheapest quotation may have higher excesses or fewer extensions.
Insuring under the wrong class
Private, commercial and PSV risks must be declared correctly.
Undervaluing the vehicle
Underinsurance may reduce a claim settlement.
Ignoring exclusions
A comprehensive policy still has conditions and limits.
Failing to disclose previous claims
Claims history can influence underwriting terms.
Allowing an unauthorised driver to use the vehicle
Driver conditions should be checked before handing over the keys.
Paying without confirming the insurer
Verify the underwriting company, payment channel and official receipt.
Assuming payment automatically means cover has started
Wait for written confirmation and check the policy details.
How to Compare Comprehensive Motor Quotations
Request several suitable quotations and compare:
- Premium rate
- Minimum premium
- Vehicle value
- Standard excess
- Theft excess
- Political violence and terrorism
- Excess protector
- Windscreen limit
- Entertainment limit
- Road rescue
- Courtesy car
- Personal accident
- Garage network
- Instalment options
- Claims requirements
Every insurer should quote using the same vehicle value and risk details.
How Imana Helps You Compare Motor Insurance
Imana Insurance Agency Kenya Ltd helps motorists compare quotations from trusted insurance companies instead of relying on one insurer’s offer.
Clients can request options for:
- Private vehicles
- Commercial vehicles
- PSV taxis
- Ride-hailing cars
- Matatus and buses
- Motorcycles and boda bodas
- Tuk-Tuks
- School buses
- Tour vans
- Tractors
- Heavy commercial vehicles
- Duty-free vehicles
- Electric vehicles
The comparison can examine premiums, excesses, extensions, payment terms and claims requirements.
Imana’s motor content also educates customers on the difference between comprehensive and third-party cover and encourages motorists to compare the protection—not merely the price. (imana.co.ke)
Motor Insurance in Westlands, Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd is based at:
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
The agency serves clients around Westlands, Sarit Centre, Westgate, Parklands, Riverside, Gigiri, Lavington, Kitisuru, Nairobi CBD and throughout Kenya using digital quotation and documentation channels.
Call or WhatsApp: +254 796 209 402
Compare Motor Insurance Quotes Before Renewal
Before renewing your current policy, ask:
- Has the vehicle value changed?
- Is the use still the same?
- Are all drivers correctly covered?
- Are the excesses manageable?
- Do you need excess protector?
- Is the windscreen limit adequate?
- Do you need political violence and terrorism?
- Are instalments available?
- Is the insurer suitable for your vehicle class?
Do not renew automatically because the expiry date is close.
Use the renewal as an opportunity to reassess your risk and compare available options.
Third party protects you from specified liabilities to others. Comprehensive also helps protect the value sitting in your own parking space.
Frequently Asked Questions
Is third-party motor insurance compulsory in Kenya?
Yes. A vehicle used on a road must have insurance or security that complies with the legal requirements for third-party risks, subject to limited statutory exceptions. (Kenya Law)
Does third-party insurance repair my own car?
No. It ordinarily covers eligible liabilities involving third parties, not accidental damage to your own vehicle.
Does comprehensive insurance include third-party cover?
Comprehensive motor policies ordinarily include a third-party liability section together with own-vehicle protection, subject to the specific wording.
Does comprehensive cover mechanical breakdown?
Not normally. Mechanical and electrical breakdown are commonly excluded unless a separate extension or specialised policy applies.
Can an old vehicle get comprehensive insurance?
Possibly. Acceptance depends on the insurer, age, condition, value, inspection and availability of parts.
Do I need a valuation?
A current valuation is commonly required for comprehensive cover to establish the vehicle’s insurable value and condition.
Is Third Party, Fire and Theft the same as comprehensive?
No. It adds fire and theft protection to third-party liability but generally excludes ordinary accidental damage to your own vehicle.
Which cover is cheaper?
Third-party insurance generally has a lower premium because it offers narrower protection.
Can I pay comprehensive insurance in instalments?
Some insurers allow instalments subject to their conditions. Confirm the deposit, payment dates and consequences of default.
Can Imana compare both comprehensive and TPO quotations?
Yes. Subject to insurer availability and underwriting appetite, Imana can help compare options for different vehicle classes.
Premiums, limits, excesses, extensions, acceptance and claims are subject to the selected insurer’s underwriting requirements, certificate, policy schedule and full policy wording.