
Blog Details
Diskava. Beta. Kava
30Jul
SHA vs Private Medical Insurance Kenya | Compare Health Cover
Understand the difference between SHA and private medical insurance in Kenya. Compare contributions, benefits, hospitals, limits, waiting periods and top-up options before choosing cover.
Is SHA the Same as Private Medical Insurance?
No.
The Social Health Authority, commonly referred to as SHA, administers Kenya’s statutory social health insurance system. Private medical insurance is a separate commercial contract purchased from a licensed insurance company.
SHA is designed to provide a national healthcare-financing foundation. Private medical insurance can provide additional limits, access options and supplementary benefits based on the policy selected.
For many Kenyan households, the practical question should therefore not be:
“Should I choose SHA or private medical insurance?”
A better question is:
“What does SHA provide, where could I still face a financial gap, and which private medical plan can help address that gap?”
SHA currently administers three principal funds:
- The Primary Healthcare Fund
- The Social Health Insurance Fund
- The Emergency, Chronic and Critical Illness Fund
Together, these funds form part of Kenya’s universal-health-coverage framework. (Kenya Law)
What Is the Social Health Authority?
The Social Health Authority is the state body established under the Social Health Insurance Act, 2023, to administer Kenya’s social health insurance system.
Its mandate includes facilitating access to healthcare and providing financial-risk protection for residents through the three statutory funds. (Kenya Law)
SHA replaced the previous National Health Insurance Fund framework. The NHIF Act was repealed when the Social Health Insurance Act came into operation. (Kenya Law)
It is useful to distinguish between the terms:
- SHA is the administering authority.
- SHIF is the Social Health Insurance Fund administered by SHA.
- Primary Healthcare Fund supports eligible primary-care services.
- Emergency, Chronic and Critical Illness Fund addresses qualifying emergency, chronic and critical-care needs within the applicable framework.
People often use “SHA” and “SHIF” interchangeably in everyday conversation, but technically they do not refer to exactly the same thing.
Who Is Required to Contribute to SHA?
The Social Health Insurance Act provides for contributions from Kenyan households, qualifying non-Kenyan residents, employers, national and county governments and other prescribed contributors.
For employed persons, contributions are generally deducted through payroll. For households without salaried income, contributions are assessed through the prescribed household-income or means-testing process. Government support may apply to households determined to require financial assistance. (Kenya Law)
The applicable regulations prescribe a contribution rate of 2.75% of gross salary or wages for salaried employment, subject to a minimum monthly contribution of KSh 300. Non-salaried households are assessed according to the applicable means-testing framework. (Ministry of Health)
This means that KSh 300 is the statutory minimum—not the standard contribution payable by every household.
Must SHA Contributions Be Active?
Yes.
The Social Health Insurance Act states that access to services under the contributory framework depends on contributions being up to date and active. The Act also provides for penalties on overdue contributions and requires outstanding contributions and applicable penalties to be settled before access resumes. (Kenya Law)
Members should therefore:
- Register correctly
- Ensure dependants are captured
- Confirm contribution status
- Verify that employer deductions have been remitted
- Update personal details when circumstances change
- Check eligibility before planned treatment
SHA provides an online eligibility service through which members can check coverage status using an identification number. (SHA Eligibility)
What Does SHA Cover?
SHA benefits are delivered through empanelled and contracted healthcare providers according to the statutory benefits package, applicable tariffs, referral requirements and other operating conditions.
The benefits framework includes services under primary healthcare and the Social Health Insurance Fund, together with mechanisms for emergency, chronic and critical illness care. (Ministry of Health)
Depending on the applicable benefit package and provider level, services may include areas such as:
- Primary healthcare
- Outpatient consultations
- Inpatient treatment
- Emergency care
- Maternity services
- Surgical services
- Chronic-disease management
- Critical-care services
- Diagnostic services
- Prescribed medicines
- Rehabilitation
- Mental-health services
- Dental and optical services under applicable provisions
However, a service being recognised within the national framework does not necessarily mean every hospital, procedure, medicine or specialist expense is payable without conditions.
Payment may depend on:
- Active contribution status
- The healthcare facility’s empanelment
- Provider level
- Referral requirements
- Approved tariffs
- Benefit limits
- Medical necessity
- Pre-authorisation
- Availability within the benefits package
What Is Private Medical Insurance?
Private medical insurance is a contract between the policyholder and a licensed insurance company.
The customer pays an agreed premium, and the insurer pays eligible medical expenses according to the policy’s:
- Benefits
- Annual limits
- Sublimits
- Waiting periods
- Hospital network
- Exclusions
- Co-payments
- Claims procedures
Private medical insurance can be purchased by:
- Individuals
- Families
- Employers
- SMEs
- Corporate organisations
- Chamas and associations
- International organisations
- Expatriates
The Insurance Regulatory Authority regulates private insurance business in Kenya and publishes registers of licensed insurers and medical insurance providers. Customers should verify the insurer and intermediary before purchasing cover. (Insurance Regulatory Authority)
What Can Private Medical Insurance Cover?
Private medical plans can be structured to include:
- Inpatient hospitalisation
- Outpatient treatment
- Maternity
- Dental care
- Optical care
- Chronic illnesses
- Pre-existing conditions
- Psychiatric treatment
- Congenital conditions
- Emergency evacuation
- Road ambulance
- Last-expense benefits
- Overseas treatment
- Personal accident benefits
- International or East Africa cover
Not every policy includes all these benefits.
Some plans offer inpatient cover only. Others combine inpatient and outpatient benefits. Maternity, dental, optical and chronic-condition protection may be included, optional or restricted by sublimits.
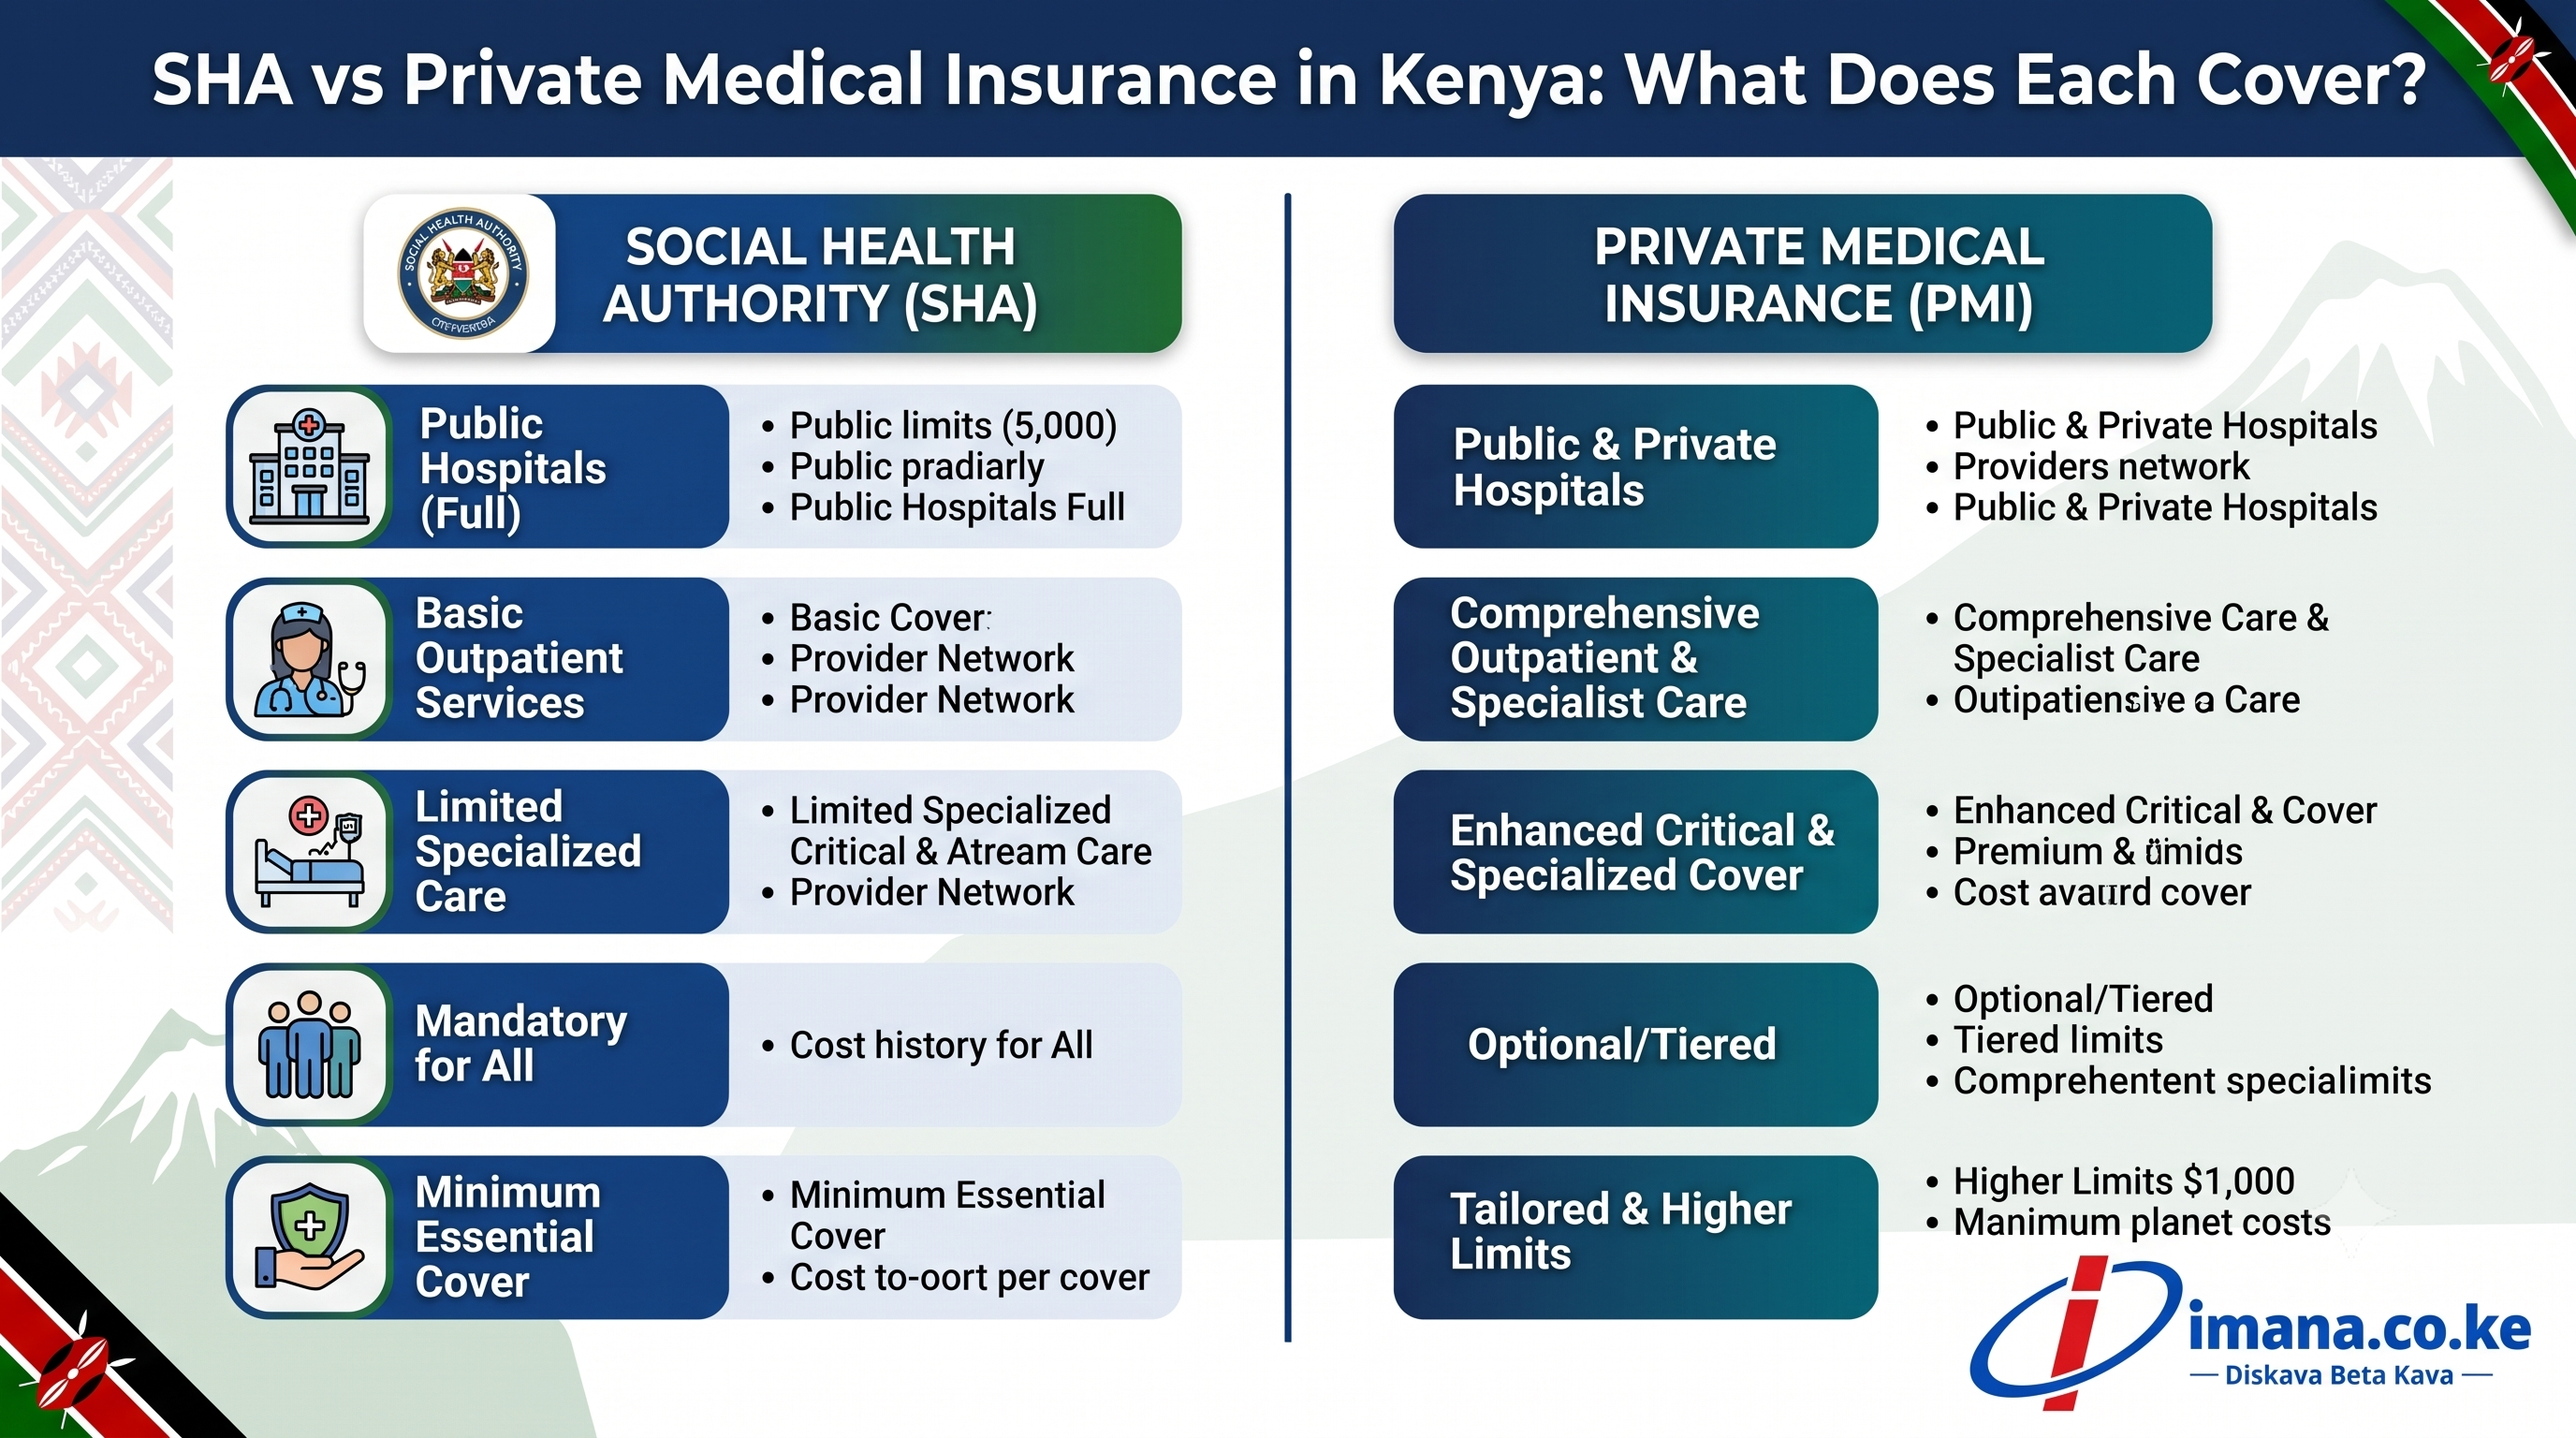
SHA vs Private Medical Insurance: The Main Differences
1. Purpose
SHA
SHA is part of Kenya’s statutory social health insurance and universal-health-coverage system. It aims to pool contributions and public resources to support healthcare access across the population.
Private medical insurance
Private insurance is an optional commercial arrangement designed around the benefit level selected by the customer or employer.
2. How the Cost Is Determined
SHA
For salaried households, the contribution is generally based on gross salary or wages. Non-salaried households are assessed using the prescribed approach, including means testing where applicable. (Kenya Law)
Private medical insurance
Premiums may depend on:
- Age
- Family size
- Inpatient limit
- Outpatient limit
- Hospital network
- Maternity benefits
- Chronic-condition exposure
- Claims history
- Group membership
- Territorial coverage
Private premiums can therefore vary substantially between customers and insurers.
3. Hospital Access
SHA
Treatment is accessed through empanelled and contracted healthcare providers within the applicable benefits framework.
Private medical insurance
Access depends on the provider panel attached to the specific plan.
A premium medical plan may provide access to a wider or higher-cost hospital network than an entry-level plan. However, no private policy should be assumed to cover every hospital.
Before purchasing, verify that the hospitals you prefer are available under the exact plan being quoted.
4. Benefit Limits
SHA
Services are payable according to the statutory benefits package, approved tariffs, eligibility requirements and fund rules.
Private medical insurance
The policy normally shows annual financial limits, such as:
- KSh 100,000 inpatient
- KSh 500,000 inpatient
- KSh 1 million inpatient
- KSh 50,000 outpatient
- Separate maternity, dental or optical sublimits
The insured member can select benefits according to affordability and underwriting availability.
5. Waiting Periods
SHA
Access depends mainly on registration, eligibility, active contributions, applicable benefit rules and provider requirements.
Private medical insurance
Waiting periods commonly apply to:
- General illness
- Maternity
- Pregnancy complications
- Pre-existing conditions
- Chronic illnesses
- Surgery
- Last-expense benefits
A person should not wait until treatment is already needed before buying private insurance.
6. Exclusions
SHA
Services are subject to the statutory package, tariffs, referral process and applicable regulations.
Private medical insurance
The policy may exclude or restrict:
- Cosmetic treatment
- Experimental procedures
- Non-prescribed supplements
- Treatment outside the panel
- Self-inflicted or deliberately caused conditions
- Undisclosed pre-existing conditions
- Services available under another statutory or insurance scheme
- Treatment beyond annual limits
- Certain specialised procedures
The exclusion section deserves as much attention as the headline benefit limits.
7. Family Structure
SHA
The system is based on household registration and the prescribed dependant framework.
Private medical insurance
A plan may use:
- Per-person limits
- Family-shared limits
- Principal-member-plus-dependants structures
- Child-only arrangements
- Group employee benefits
The best structure depends on the household’s ages, health needs and budget.
8. Claims and Treatment Approval
SHA
The healthcare provider processes services through the SHA framework, subject to eligibility, tariffs, empanelment and authorisation requirements.
Private medical insurance
Treatment may be settled through:
- Direct billing
- Provider pre-authorisation
- Reimbursement
- Cashless outpatient systems
- Emergency admission notification
The member must follow the insurer’s claims and pre-authorisation procedure.
Can Private Medical Insurance Replace SHA?
Private medical insurance should not automatically be viewed as a replacement for SHA.
SHA is part of the statutory health-financing framework, while private insurance provides benefits under a separate contract.
Some private policies are designed to supplement SHA. They may address eligible costs or benefit gaps remaining after SHA has applied its benefits and tariffs.
Other private policies may contain coordination-of-benefits provisions stating that expenses recoverable from SHA or another scheme must be claimed there first.
Before buying private medical cover, ask:
- Must I maintain active SHA membership?
- Does SHA pay first?
- Is the policy a full medical plan or an SHA top-up?
- Which costs can be claimed privately?
- What documents are required after SHA processes treatment?
- What happens when SHA declines a service?
- Are private benefits reduced by amounts paid through SHA?
The answer depends on the selected private policy.
What Is SHA Top-Up Medical Insurance?
An SHA top-up is a private insurance arrangement intended to supplement the statutory cover.
It may help with eligible expenses such as:
- Amounts above the applicable SHA tariff
- Additional inpatient limits
- Wider hospital access
- Outpatient benefits
- Maternity benefits
- Dental and optical care
- Chronic-condition treatment
- Emergency evacuation
- Last-expense benefits
However, “top-up” does not mean unlimited payment of every expense that SHA does not pay.
A top-up policy still has:
- Annual limits
- Sublimits
- Waiting periods
- Provider restrictions
- Excesses or co-payments
- Exclusions
Ask for a written benefit schedule showing exactly how the top-up interacts with SHA.
Why Might You Still Need Private Medical Insurance?
1. Higher Financial Limits
A serious illness, operation or prolonged admission can cost more than the amount payable under a basic healthcare arrangement.
Private insurance can provide an additional financial layer.
2. Broader Provider Choice
Depending on the plan, private insurance may provide access to additional private hospitals, specialists and diagnostic centres.
3. Outpatient Flexibility
Some plans offer substantial outpatient limits for:
- Consultations
- Prescribed medicine
- Diagnostic tests
- Chronic-disease management
- Follow-up treatment
4. Maternity Benefits
Private policies can provide defined maternity limits, although waiting periods normally apply.
5. Dental and Optical Benefits
These may include:
- Dental consultations
- Extractions
- Fillings
- Scaling
- Eye examinations
- Prescribed lenses
- Frames within a sublimit
6. Chronic and Pre-Existing Conditions
Selected plans provide cover after an applicable waiting period and within stated sublimits.
7. Regional or International Cover
Private insurance may extend to East Africa or other territories, subject to the policy.
8. Employer Benefits
Businesses can arrange group medical insurance as an employee benefit while maintaining statutory SHA contributions.
Does SHA Make Private Medical Insurance Unnecessary?
Not necessarily.
SHA may provide a meaningful healthcare foundation, but each person’s circumstances are different.
A healthy young adult may decide that SHA plus a modest private inpatient plan is sufficient.
A family with young children may prioritise outpatient, maternity, dental and optical benefits.
A senior citizen may require chronic-condition management and a broader inpatient limit.
An employer may want a group medical scheme to improve employee welfare and provide access to additional private facilities.
The correct decision depends on:
- Health needs
- Age
- Family composition
- Preferred hospitals
- Employment benefits
- Chronic conditions
- Maternity plans
- Budget
- Ability to meet uninsured medical expenses
How SHA and Private Insurance May Work Together
Consider a simplified example.
A patient is admitted for a covered medical procedure.
The healthcare provider may first process the applicable benefit through SHA according to:
- Eligibility
- Approved tariff
- Provider level
- Benefit package
Where the patient also has private insurance, the private policy may then address eligible additional costs, subject to its:
- Annual limit
- Provider panel
- Pre-authorisation
- Waiting periods
- Exclusions
- Coordination-of-benefits rules
The exact order and payment arrangement should be confirmed with the hospital, SHA and private insurer before planned treatment.
Do not assume that the two systems will automatically settle the entire bill between them.
Questions to Ask About SHA Before Treatment
Before visiting a hospital, confirm:
- Is my SHA membership active?
- Are my contributions up to date?
- Are my dependants correctly registered?
- Is the healthcare provider empanelled?
- Do I need a referral?
- Is pre-authorisation required?
- Which services are available at this provider level?
- What tariff applies?
- Which costs may remain payable personally?
- What identification documents should I carry?
SHA provides resources and information concerning contracted or licensed healthcare facilities, and members can check their eligibility online. (SHA Eligibility)
Questions to Ask Before Buying Private Medical Insurance
Ask the insurer or intermediary:
- What is the inpatient limit?
- Is outpatient cover included?
- Is the limit per person or shared by the family?
- Which hospitals are available?
- What are the waiting periods?
- How are pre-existing conditions handled?
- What is the maternity limit?
- Are dental and optical benefits included?
- Are co-payments charged?
- Are MRI, CT and PET scans pre-authorised?
- Does the policy require active SHA status?
- Does SHA pay first?
- Are treatment costs outside Kenya covered?
- What is excluded?
- How does emergency admission work?
A quotation without a detailed benefit schedule is not enough.
Family-Shared vs Per-Person Private Medical Cover
Family-shared benefit
One overall limit is shared among the insured family members.
For example, a family may share one KSh 500,000 inpatient limit.
Possible advantage
The annual premium may be more affordable.
Possible disadvantage
One major claim may use most of the limit, leaving less for other family members.
Per-person benefit
Each family member receives an individual limit.
For example, every insured person may have a separate KSh 500,000 inpatient limit.
Possible advantage
One member’s claim does not consume the entire family’s protection.
Possible disadvantage
The annual premium may be higher.
Compare both structures before selecting a plan.
Medical Insurance for Children
Parents should review whether a child can be insured:
- Under SHA as a registered dependant
- Under a parent’s private policy
- Through a child-only medical plan
- Under an employer-sponsored scheme
A child-only private policy may provide:
- Inpatient cover
- Outpatient care
- Dental and optical benefits
- Diagnostic tests
- Accident protection
- Congenital-condition benefits within stated limits
Waiting periods and entry-age rules vary between providers.
Medical Insurance for Parents and Senior Citizens
Adults approaching retirement may need private medical insurance that considers:
- Maximum entry age
- Maximum renewal age
- Chronic illnesses
- Pre-existing conditions
- Co-payments
- Medical examinations
- Hospital network
- Inpatient limit
- Cancer and renal treatment benefits
It is generally better to arrange cover before reaching the maximum entry age.
A policy that permits renewal to an advanced age may still require the member to join earlier and maintain continuous cover.
Medical Insurance for SMEs and Employers
Employers are still required to comply with SHA contribution obligations while considering private group medical insurance as an additional employee benefit.
A private corporate scheme may offer:
- Inpatient cover
- Outpatient benefits
- Maternity
- Dental and optical
- Chronic-condition management
- Emergency evacuation
- Last expense
- Employee assistance benefits
Group premiums depend on:
- Number of employees
- Ages
- Family structure
- Benefit limits
- Hospital network
- Claims history
- Industry
- Membership stability
Businesses should use accurate employee data when requesting quotations.
What Happens When Your Preferred Hospital Is Not Available?
Whether using SHA or private medical insurance, access depends on the provider arrangements applicable to that cover.
Where a preferred hospital is unavailable:
- Ask for another empanelled or approved provider.
- Confirm whether reimbursement is permitted.
- Check whether emergency treatment is treated differently.
- Obtain written authorisation before planned treatment.
- Do not assume the policy will reimburse treatment obtained outside the network.
Provider lists can change. Check the current status before admission—not only when purchasing the policy.
What Happens When a Medical Claim Is Declined?
First establish the reason.
Possible reasons include:
- Inactive SHA contributions
- Non-empanelled facility
- Missing referral
- Benefit not available at that provider level
- Private-policy waiting period
- Excluded treatment
- Exhausted annual limit
- Missing pre-authorisation
- Incorrect member details
- Non-disclosure
- Incomplete claim documents
Request the decision and reason in writing.
For private medical insurance disputes, customers may first use the insurer’s complaint process and then approach the Insurance Regulatory Authority where necessary. The IRA handles complaints involving disputes over liability, settlement amounts and delays in payable claims. (Insurance Regulatory Authority)
Common Mistakes to Avoid
Assuming SHA Covers Every Medical Bill
SHA benefits are subject to statutory packages, tariffs, provider levels and operating requirements.
Cancelling Private Insurance Without Reviewing the Gaps
First compare what your current private policy provides against what you would retain through SHA alone.
Buying a “Top-Up” Without Understanding It
Request a written explanation of how the plan coordinates with SHA.
Choosing Private Medical Cover on Premium Alone
A cheap plan may have low limits, long waiting periods or a restricted hospital network.
Ignoring Waiting Periods
Maternity and pre-existing-condition benefits rarely begin immediately.
Failing to Register Dependants Properly
Incorrect household or policy records can cause delays during treatment.
Waiting Until Someone Is Ill
Insurance is designed to address uncertain future events, not treatment already known to be necessary.
How to Compare SHA and Private Medical Insurance
Use the following practical process.
Step 1: Understand your SHA position
Confirm:
- Registration
- Contribution status
- Dependants
- Healthcare providers
- Applicable benefits
Step 2: Identify your likely medical needs
Consider:
- Routine outpatient visits
- Children
- Maternity
- Chronic conditions
- Senior parents
- Preferred hospitals
- Regional travel
Step 3: Estimate the gap
Ask which expenses could remain after SHA applies its tariff and benefit rules.
Step 4: Request several private quotations
Ensure every insurer quotes using the same ages, family composition and benefit limits.
Step 5: Compare the policy details
Review:
- Premium
- Inpatient limit
- Outpatient limit
- Hospital network
- Waiting periods
- Co-payments
- Maternity
- Chronic-condition benefits
- SHA coordination
- Exclusions
Step 6: Choose sustainable cover
The policy should provide meaningful protection at a premium you can maintain at renewal.
How Imana Helps You Compare Medical Insurance
Imana Insurance Agency Kenya Ltd helps individuals, families, senior citizens, employers and organisations compare private medical insurance quotations.
The comparison may examine:
- Annual premium
- Inpatient and outpatient limits
- Family-shared or per-person benefits
- Hospital networks
- Maternity
- Dental and optical
- Waiting periods
- Pre-existing conditions
- Entry and renewal ages
- SHA top-up arrangements
- Claims and pre-authorisation procedures
Imana can assist with:
- Individual medical insurance
- Family medical insurance
- Child-only medical cover
- Senior citizens’ medical insurance
- Microhealth insurance
- Maternity cover
- Group medical insurance
- Corporate medical schemes
- SHA supplementary options
Private insurers and medical insurance providers should be checked against the current IRA licensing registers before placement. (Insurance Regulatory Authority)
Request a Medical Insurance Comparison
Health insurance page:
https://imana.co.ke/insurance/health-insurance
Microhealth and child-only options:
https://imana.co.ke/mykava-product-quote
Office:
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Call or WhatsApp: +254 796 209 402
Medical Insurance in Westlands, Nairobi and Across Kenya
Imana serves clients around:
- Westlands
- Sarit Centre
- Westgate
- Parklands
- Riverside
- Spring Valley
- Lavington
- Kitisuru
- Gigiri
- Runda
- Muthaiga
- Nairobi CBD
- Kasarani
- Roysambu
- Ruiru
- Kangundo Road
- Umoja Phase 1 and 2
- Embakasi
Clients in other counties can request medical quotations and submit documents through online channels.
Frequently Asked Questions
Is SHA the same as SHIF?
No. SHA is the Social Health Authority. SHIF is the Social Health Insurance Fund administered by SHA.
How much is the SHA contribution?
For salaried households, the prescribed contribution is generally 2.75% of gross salary or wages, subject to a minimum monthly contribution of KSh 300. Non-salaried households are assessed using the applicable framework. (Ministry of Health)
Can I use SHA when my contributions are not active?
The Act requires contributions to be up to date and active before accessing services under the contributory framework. (Kenya Law)
Does private medical insurance replace SHA?
Not automatically. Private cover may supplement SHA, but coordination depends on the selected policy.
What is an SHA top-up?
It is a private insurance plan designed to address specified costs or benefits beyond the applicable SHA protection, subject to the policy’s limits and exclusions.
Can I have SHA and private medical insurance together?
Yes. Many individuals and employers maintain statutory SHA membership alongside private medical cover.
Does SHA cover private hospitals?
Access depends on whether the facility is empanelled and contracted and whether the required service is available under the applicable benefits and provider level.
Is private medical insurance compulsory?
Private medical insurance is generally optional. SHA contribution obligations arise under the statutory framework.
Can private insurance cover pre-existing conditions?
Some policies provide defined benefits after a waiting period and within stated sublimits. Others exclude particular conditions.
Which is better: SHA or private insurance?
They serve different purposes. SHA provides the statutory foundation, while private insurance can provide additional benefits, limits and provider options.
Can Imana compare medical quotations?
Yes. Imana can help clients compare suitable private plans and SHA supplementary options, subject to insurer availability and underwriting requirements.
The Bottom Line
SHA and private medical insurance should not always be treated as competitors.
SHA provides Kenya’s statutory healthcare-financing foundation. Private medical insurance can add another layer of protection through higher limits, wider provider choices and benefits tailored to individuals, families or employees.
The smart approach is:
Understand SHA. Identify the gaps. Compare private quotations. Choose additional cover that fits your needs and budget.
Visit: www.imana.co.ke
Compare medical insurance: https://imana.co.ke/insurance/health-insurance
Call or WhatsApp: +254 796 209 402
SHA can form the foundation. The right private medical policy can strengthen the protection around it.
SHA benefits, contribution requirements, tariffs and provider arrangements are governed by applicable laws, regulations and operational procedures and may change. Private medical premiums, benefits, waiting periods, exclusions and claims are subject to the selected insurer’s underwriting requirements and policy wording. Confirm current terms before seeking treatment or purchasing cover.