
Blog Details
Diskava. Beta. Kava
16Jul
MyKava Corporate Medical Insurance in Kenya: Affordable Health Cover for Employees and Their Dependants
MyKava Corporate Medical Insurance in Kenya | Staff Health Cover
Protect your employees with MyKava Corporate Medical Insurance in Kenya. Get flexible inpatient, outpatient, dental and optical cover for staff and dependants.
A healthy workforce is the backbone of every successful business.
Employees perform better when they know they can access medical care without worrying about overwhelming hospital bills. Medical insurance also shows employees that their employer values their health, families and long-term well-being.
MyKava Corporate Medical Insurance provides flexible and affordable medical cover for SMEs, companies, institutions and other organisations in Kenya. The cover can be structured for employees alone or extended to include eligible dependants.
Whether your organisation has a small team or a growing workforce, Imana Insurance Agency Kenya Ltd can help you compare suitable medical insurance options and identify a plan that fits your benefits strategy and budget.
What Is Corporate Medical Insurance?
Corporate medical insurance is a health insurance arrangement purchased by an employer to cover employees and, depending on the selected plan, their spouses and children.
Instead of every employee purchasing an individual medical insurance policy, the employer arranges one structured group plan for the organisation.
Corporate medical insurance may provide access to:
- Inpatient treatment
- Outpatient consultations
- Diagnostic tests
- Prescribed medication
- Specialist consultations
- Dental treatment
- Optical care
- Emergency medical services
- Regional medical treatment
The specific benefits, limits, exclusions, waiting periods and provider network depend on the selected plan and policy terms.
Why Businesses in Kenya Need Employee Medical Insurance
Healthcare costs can rise unexpectedly. A single illness, accident or hospital admission can place serious financial pressure on an employee and their family.
When employees lack adequate medical cover, they may delay treatment, borrow money or miss work for extended periods. This can affect their health, productivity and overall morale.
Corporate medical insurance helps employers create a more stable and supportive working environment.
1. It improves employee retention
Good employees are difficult and expensive to replace. A strong medical insurance benefit can make your organisation more attractive to both current and prospective employees.
Workers are more likely to remain loyal to employers who actively support their health and well-being.
2. It supports productivity
Employees who can access medical attention early are less likely to allow minor health conditions to become serious.
Timely treatment can reduce prolonged absenteeism and help employees return to work sooner.
3. It strengthens employee morale
Medical insurance communicates care.
It tells employees that the organisation sees them as people, not just as workers. This can improve trust, motivation and workplace culture.
4. It protects employees from unexpected medical costs
Hospital bills can quickly consume savings and household income.
Corporate medical cover reduces the financial burden associated with covered treatment, subject to the policy terms and available limits.
5. It strengthens your employee benefits package
Salary remains important, but employees increasingly consider the full value of a job offer.
Medical insurance can help a company compete for skilled professionals without relying only on salary increases.
MyKava Corporate Medical Insurance Benefits
MyKava Corporate Medical Insurance offers various benefit options that employers can consider when structuring medical cover for their teams.
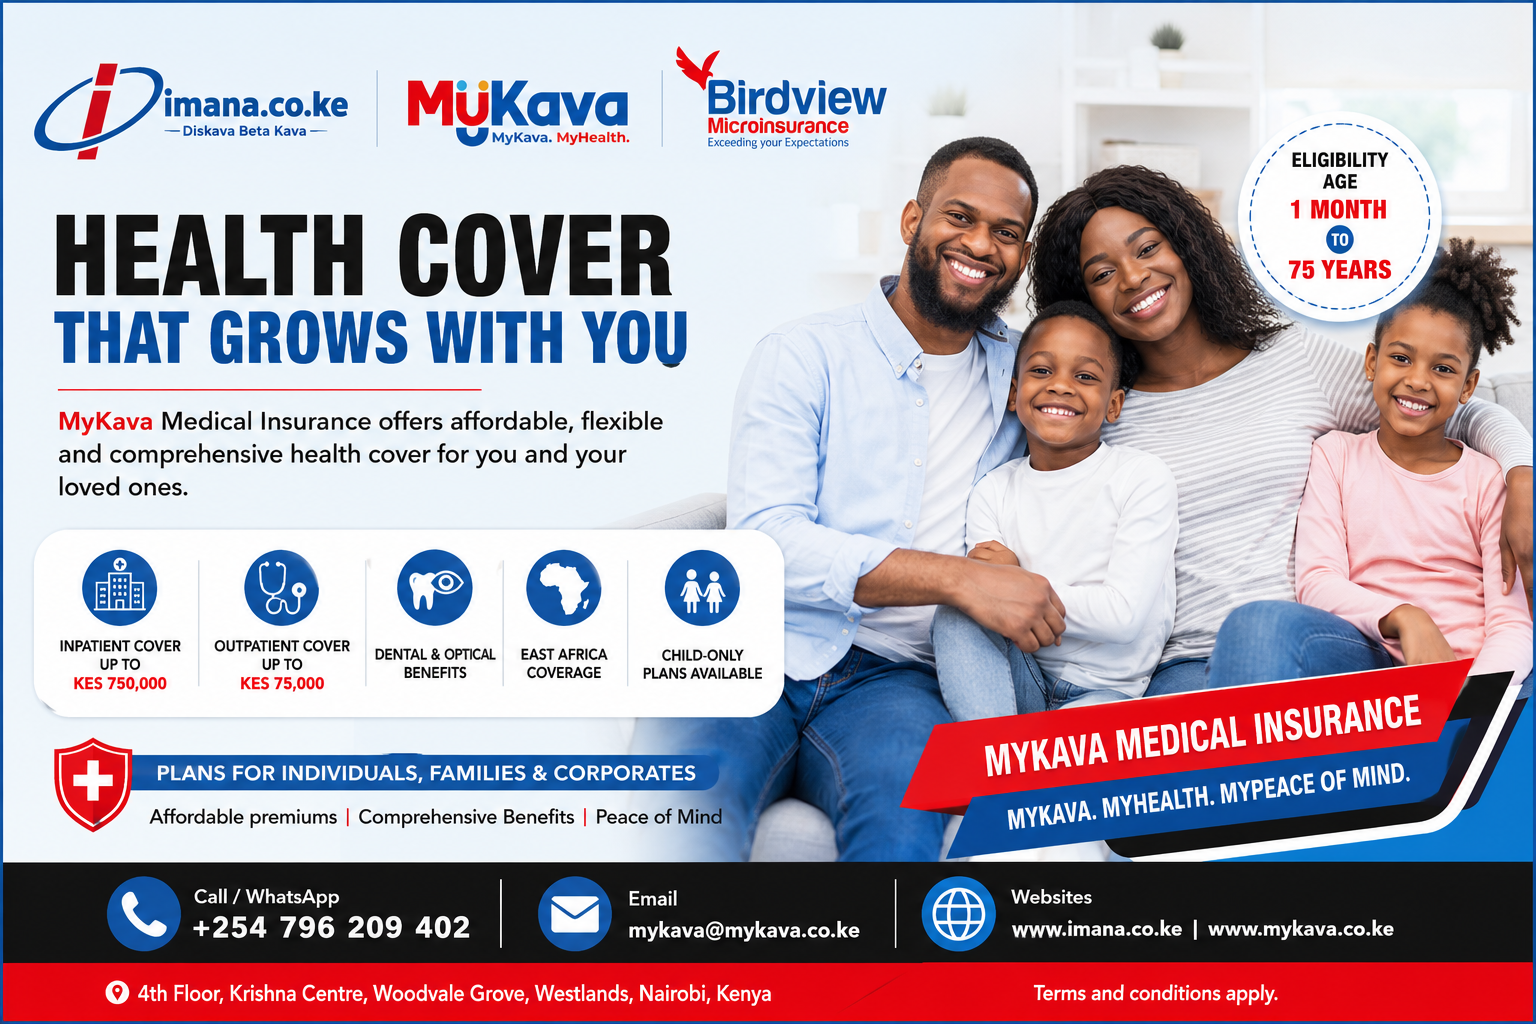
Inpatient cover of up to KES 750,000
Inpatient insurance helps cover eligible medical expenses when an insured member is admitted to a hospital.
Depending on the selected plan, inpatient treatment may include:
- Hospital accommodation
- Doctor and specialist fees
- Surgery
- Theatre charges
- Diagnostic tests
- Prescribed medication
- Intensive care
- Emergency treatment
Available inpatient limits include options of up to KES 750,000 per insured person, depending on the plan selected.
Outpatient cover of up to KES 75,000
Outpatient cover supports medical treatment that does not require hospital admission.
It may include:
- General consultations
- Specialist consultations
- Laboratory tests
- Diagnostic procedures
- Prescribed medication
- Follow-up treatment
Available outpatient limits may go up to KES 75,000 per insured person, subject to the chosen benefit option.
Cover for employees and dependants
Employers may choose to cover employees only or extend protection to eligible dependants.
Dependants may include:
- Spouses
- Children
- Other eligible family members, depending on underwriting and policy rules
Including dependants can make the medical scheme more meaningful because family health concerns often affect an employee’s emotional well-being, finances and concentration at work.
Child-only medical plans
MyKava Medical Insurance also allows child-only arrangements, subject to policy terms.
This can benefit organisations or groups seeking medical protection for children without necessarily placing every child under a standard family package.
Dental and optical benefits
Dental and optical benefits may be included or selected as additional benefits, depending on the plan.
Dental benefits may help with eligible services such as consultations, extractions and other routine treatments.
Optical benefits may help with eye consultations, prescribed lenses and frames, subject to the applicable limits and exclusions.
East Africa medical coverage
The cover may provide access to eligible medical treatment across East Africa, depending on the selected plan and provider network.
This can be valuable for companies whose employees travel or work within Kenya and neighbouring countries.
Who Is Eligible for MyKava Medical Insurance?
MyKava Medical Insurance is available to eligible members aged between 1 month and 75 years, subject to underwriting, policy terms and the insurer’s acceptance criteria.
This broad eligibility range makes the cover suitable for:
- Young employees
- Employees with children
- Middle-aged professionals
- Senior employees
- Spouses and dependants
- Business owners and directors
Employers should disclose accurate employee and dependant information during quotation and enrolment. Age, group size, benefit selection and medical history may affect pricing and acceptance.
Who Can Purchase MyKava Corporate Medical Insurance?
The plan is suitable for different types of organisations, including:
- Small and medium-sized enterprises
- Large companies
- Professional firms
- Schools and educational institutions
- Churches and faith-based organisations
- NGOs
- SACCOs
- Associations
- Startups
- Family-owned businesses
- Staff welfare groups
Even a growing business with a relatively small team can explore corporate medical insurance options.
You do not need to wait until your organisation has hundreds of employees before considering medical cover.
Can SMEs Afford Corporate Medical Insurance?
Many small business owners assume employee medical insurance is only available to large corporations. That is not always the case.
The cost of corporate medical insurance depends on several factors, including:
- Number of employees
- Ages of employees and dependants
- Inpatient limit selected
- Outpatient limit selected
- Dental and optical benefits
- Maternity benefits, where applicable
- Geographical area of cover
- Provider network
- Claims history
- Industry and occupational risk
- Whether the scheme covers employees only or families
An intermediary can help the business compare available structures and identify a balance between affordability and meaningful protection.
The cheapest plan is not always the best plan. Employers should examine the limits, exclusions, waiting periods, hospitals and claims procedures before making a decision.
How Much Does Corporate Medical Insurance Cost in Kenya?
There is no single standard price for corporate medical insurance.
Premiums are calculated based on the profile and requirements of each organisation. Two companies with the same number of employees may receive different quotations because their age distribution, benefit limits and dependant structures are different.
To obtain an accurate quotation, the employer may be asked to provide a staff census containing:
- Employee names or identification numbers
- Dates of birth or ages
- Gender
- Relationship of each dependant
- Preferred benefit limits
- Existing medical scheme information
- Previous claims experience, where applicable
Providing complete and accurate information helps insurers prepare realistic quotations.
What Employers Should Compare Before Buying Staff Medical Cover
Do not compare corporate medical insurance using price alone.
A low premium may come with restricted hospital access, low limits or broad exclusions.
Employers should compare the following:
Benefit limits
Check the inpatient, outpatient, dental, optical and any other selected limits.
Hospital network
Confirm whether the preferred hospitals, clinics and specialists are included in the provider network.
Waiting periods
Some treatments or benefits may have waiting periods before members can claim.
Exclusions
Review services and conditions that are not covered.
Pre-existing and chronic conditions
Confirm how the insurer handles ongoing medical conditions, long-term medication and chronic illness.
Claims and approval process
Understand how members access treatment, obtain approvals and submit reimbursement claims.
Regional coverage
Companies with travelling employees should confirm whether treatment is available outside Kenya or within East Africa.
Customer support
A good intermediary should remain available after the policy is issued to support enrolment, approvals, claims and renewals.
Why Work With Imana Insurance Agency Kenya Ltd?
Imana Insurance Agency Kenya Ltd works with trusted insurance providers to help businesses compare medical insurance options.
Our role is not simply to issue a policy. We help clients understand the differences between quotations and choose a plan that responds to their workforce needs.
We can assist with:
- Reviewing employee medical insurance requirements
- Requesting quotations from suitable insurers
- Comparing benefits and premiums
- Explaining exclusions and waiting periods
- Supporting employee enrolment
- Assisting with policy documentation
- Following up on claims and approvals
- Supporting annual renewals
Insurance should make sense before you buy it—not after a medical emergency occurs.
How to Get a MyKava Corporate Medical Insurance Quote
To request a corporate medical insurance quotation, prepare basic information about your organisation and workforce.
You may need to provide:
- Company or organisation name
- Nature of business
- Number of employees
- Number of dependants
- Ages or dates of birth
- Preferred inpatient limit
- Preferred outpatient limit
- Additional benefits required
- Current insurer, where applicable
- Renewal date, where applicable
Once this information is available, Imana Insurance Agency Kenya Ltd can help you compare suitable options.
Frequently Asked Questions
What is the entry age for MyKava Medical Insurance?
Eligible members may join from 1 month old up to 75 years, subject to policy terms and underwriting requirements.
Can a company cover employees only?
Yes. An employer may request an employee-only plan or extend cover to eligible dependants.
Can small businesses buy corporate medical insurance?
Yes. SMEs and growing businesses can explore group medical insurance options based on their team size, budget and preferred benefits.
Does the cover include outpatient treatment?
Yes. Outpatient benefit options are available, with limits of up to KES 75,000, depending on the selected plan.
What is the maximum inpatient limit?
Available inpatient options may go up to KES 750,000 per insured person, subject to the selected plan.
Are dental and optical benefits included?
Dental and optical benefits may be included or selected as part of the medical insurance package, depending on the quotation and plan structure.
Does the plan cover treatment outside Kenya?
East Africa coverage may be available, subject to the selected plan, territorial limits and provider network.
Can children be insured separately?
Child-only plans are available, subject to eligibility rules and policy terms.
Protect Your Team and Strengthen Your Business
Employees carry the daily ambitions of a company. When their health is protected, they can focus on building, serving, creating and growing.
A corporate medical insurance plan is more than another workplace expense. It is an investment in people, productivity and business continuity.
Let Imana Insurance Agency Kenya Ltd help you compare available medical insurance options and design a practical cover for your employees and their dependants.
Request a Corporate Medical Insurance Quote
Call or WhatsApp: +254 796 209 402
Website: www.imana.co.ke
MyKava: www.mykava.co.ke
Location: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
MyKava Medical Insurance—protecting your team through every stage of life.
Terms, conditions, exclusions, waiting periods and underwriting requirements apply.