
Blog Details
Diskava. Beta. Kava
02Aug
Landlord Insurance in Kenya | Buildings, Rent and Liability Cover
Learn how Landlord Insurance in Kenya protects rental buildings, fixtures, rental income and legal liability against fire, flood, burglary, tenant damage and other insured risks.
What Would Happen If Your Rental Property Could Not Be Occupied?
A rental property can provide stable income for many years, but it also exposes the owner to significant financial risks.
A fire can damage several apartments. A burst water pipe can destroy ceilings and electrical systems. A tenant or visitor may suffer an injury in a common area. Burglars may steal equipment from a furnished unit. Flooding may make a building temporarily uninhabitable.
The landlord may then face:
- Repair and rebuilding expenses
- Lost rental income
- Tenant complaints
- Alternative-accommodation demands
- Legal claims
- Loan repayments without rental income
- Debris-removal expenses
- Replacement of fixtures and equipment
- Professional fees
- Delayed occupation after repairs
Landlord Insurance is designed to protect rental-property owners against selected physical, financial and liability risks.
A rental building is not only a property asset. It is also an income-producing business that needs protection against both physical damage and interrupted rent.
What Is Landlord Insurance?
Landlord Insurance is an insurance arrangement designed for property that is rented to tenants.
It may combine several sections, including:
- Building Insurance
- Fire and Allied Perils
- Landlord’s Contents Insurance
- Loss of Rent
- Property Owners’ Liability
- Burglary Insurance
- Accidental Damage
- Machinery Breakdown
- Political Violence and Terrorism
- Fidelity Guarantee
- Money Insurance
- Employer-related protection
The appropriate cover depends on whether the property is:
- A residential apartment
- A block of flats
- A maisonette
- A furnished rental
- A commercial building
- A shopping centre
- An office building
- A warehouse
- Student accommodation
- A serviced apartment
- An Airbnb or short-term rental
- A mixed residential and commercial development
A domestic home policy may not be suitable where the property is primarily occupied by paying tenants.
The insurer should be told exactly how the building is used.
Who Needs Landlord Insurance in Kenya?
Landlord Insurance may be suitable for:
- Individual rental-property owners
- Apartment-block owners
- Property-investment companies
- Real-estate developers
- Commercial landlords
- Shopping-centre owners
- Owners of student hostels
- Warehouse owners
- Property-management companies
- Housing cooperatives
- Family property-holding companies
- Owners of furnished rentals
- Airbnb and serviced-apartment operators
- Banks or financiers with an interest in the building
A landlord should not assume that the tenant’s insurance protects the landlord’s building.
Similarly, a tenant should not assume that the landlord’s building policy protects the tenant’s belongings.
What Can Landlord Insurance Cover?
1. The Rental Building
Building Insurance protects the physical structure against specified insured risks.
The insured property may include:
- Walls
- Roof
- Floors
- Ceilings
- Doors and windows
- Permanent electrical wiring
- Plumbing systems
- Built-in cupboards
- Gates and fences
- Water tanks
- Fixed sanitary fittings
- Permanent lifts and machinery
- Landlord-owned fixtures
The land itself is not normally insured as part of the building value.
The sum insured should generally reflect the cost of rebuilding the structure—not the property’s selling price.
2. Fire and Allied Perils
A landlord’s policy may protect against fire and selected additional events such as:
- Lightning
- Explosion
- Storm
- Flood
- Earthquake
- Impact damage
- Malicious damage
- Burst water pipes
- Falling trees
- Other listed risks
The selected policy schedule must show which risks are included.
A policy described simply as “Fire Insurance” may not automatically include flood, earthquake, malicious damage or burst pipes.
3. Loss of Rent
A serious insured event may make a property temporarily uninhabitable.
During repairs, the landlord may lose rental income while still meeting:
- Mortgage repayments
- Property rates
- Security expenses
- Maintenance contracts
- Management fees
- Insurance premiums
- Staff salaries
Loss of Rent Insurance may protect eligible rental income following physical damage caused by an insured peril.
Example
A fire damages six apartments in a rental block.
Building Insurance may pay eligible repair expenses.
Loss of Rent Insurance may help replace the rent that would have been received while the affected units are undergoing repair, subject to the selected indemnity period and policy terms.
Loss of rent does not ordinarily cover:
- A tenant refusing to pay
- A vacant apartment with no tenant
- Ordinary market decline
- Poor property management
- A tenant leaving voluntarily
- Rent arrears unrelated to insured physical damage
4. Landlord’s Contents Insurance
Where the landlord provides furniture or equipment, the contents should be insured separately.
Landlord-owned contents may include:
- Beds
- Sofas
- Tables
- Curtains
- Refrigerators
- Cookers
- Televisions
- Washing machines
- Office furniture
- Security equipment
- Gym equipment
- Common-area furniture
Contents should be valued at their current replacement cost.
A building policy does not automatically protect movable furniture and appliances.
5. Property Owners’ Liability
A landlord may face a legal claim where a tenant, visitor or member of the public suffers accidental injury or property damage connected to the building.
Examples include:
- A visitor falling on a defective staircase
- A balcony rail giving way
- A loose tile causing injury
- A water tank damaging neighbouring property
- A gate injuring a pedestrian
- A ceiling collapsing
- Water leaking into an adjoining apartment
- Poorly maintained common areas causing an accident
Property Owners’ Liability Insurance may cover eligible:
- Compensation
- Legal defence expenses
- Claimant’s approved legal costs
- Investigation expenses
The landlord must still maintain the premises properly.
Insurance does not remove the duty to repair unsafe structures.
6. Burglary Insurance
Burglary cover may protect landlord-owned contents where property is stolen following forcible or violent entry into or exit from the insured premises.
It may be relevant to:
- Furnished apartments
- Serviced residences
- Building-management offices
- Common-area equipment
- Maintenance stores
- Security equipment
The policy may require:
- Functional locks
- Security guards
- CCTV
- Alarms
- Secure windows
- Police reporting
- An inventory of insured property
Unexplained disappearance or theft without evidence of entry may be excluded.
7. Malicious Damage
Tenants or third parties may deliberately damage:
- Doors
- Windows
- Walls
- Plumbing
- Electrical fittings
- Furniture
- Appliances
Malicious Damage Insurance may cover eligible deliberate physical damage, subject to the policy.
However, ordinary wear, poor housekeeping, unauthorised alterations and gradual deterioration may not qualify.
Damage deliberately caused by a tenant may require a specific tenant-malicious-damage extension.
8. Accidental Damage
Accidental Damage may cover sudden, unintended physical loss beyond the standard named perils.
Examples may include:
- A heavy object damaging a tiled floor
- Accidental damage to fixed glass
- A tenant accidentally damaging landlord-owned fittings
- Accidental impact to a gate or wall
The protection depends on the policy wording and may carry a separate excess.
9. Machinery Breakdown
Larger rental developments may depend on:
- Lifts
- Water pumps
- Generators
- Boilers
- Air-conditioning equipment
- Borehole machinery
- Sewage-treatment equipment
- Access-control systems
Machinery Breakdown Insurance may protect against sudden and unforeseen internal mechanical or electrical failure.
Wear and tear, poor maintenance and gradual deterioration are commonly excluded.
10. Electronic Equipment Insurance
Electronic Equipment Insurance may protect:
- CCTV systems
- Computers
- Access-control equipment
- Intercom systems
- Servers
- Security-monitoring equipment
- Property-management devices
Cyber incidents and physical electronic damage should be considered separately.
11. Political Violence and Terrorism
Ordinary property policies may exclude damage arising from:
- Political violence
- Riots
- Civil commotion
- Terrorism
- Certain malicious acts
A landlord can request an extension covering qualifying property damage and, where available, the resulting loss of rent.
12. Glass Insurance
Commercial buildings may have expensive:
- Shopfront glass
- Display windows
- Glass doors
- Internal partitions
- Large office windows
Glass Insurance may cover accidental breakage, replacement and associated costs, subject to the selected limits.
Landlord Insurance vs Home Insurance
These policies may protect similar physical property, but their intended use is different.
Home Insurance
Home Insurance is generally designed for an owner-occupied private residence.
It may protect:
- The home
- Household contents
- Personal belongings
- Domestic liability
- Domestic employees
Landlord Insurance
Landlord Insurance recognises that the property is rented for income.
It may include:
- Rental building protection
- Landlord-owned contents
- Loss of rent
- Property Owners’ Liability
- Tenant-related risks
- Multiple units
- Commercial occupancy
A property should not be presented as owner-occupied when it is actually rented to tenants.
Incorrectly declaring the use may affect a claim.
Landlord Insurance vs Tenant Insurance
The landlord and tenant have different insurable interests.
The landlord normally insures:
- The building
- Permanent fixtures
- Landlord-owned contents
- Loss of rent
- Property Owners’ Liability
- Common areas
The tenant may insure:
- Personal furniture
- Electronics
- Clothing
- Business stock
- Equipment
- Tenant improvements
- Personal or business liability
A tenant’s belongings are not automatically protected by the landlord’s policy.
Lease agreements should clearly state each party’s insurance responsibilities.
Insurance for Residential Rental Properties
Residential landlords may own:
- Bedsitters
- Single rooms
- Apartments
- Maisonettes
- Townhouses
- Gated-community homes
- Student housing
- Staff accommodation
Suitable covers may include:
- Building Insurance
- Fire and Allied Perils
- Loss of Rent
- Property Owners’ Liability
- Landlord’s Contents
- Burglary
- Political Violence
- Domestic-employees WIBA where applicable
The insurer should know:
- Number of units
- Occupancy type
- Construction materials
- Security arrangements
- Whether units are furnished
- Whether cooking is permitted
- Whether commercial activities take place
Insurance for Commercial Landlords
Commercial landlords may rent property to:
- Shops
- Restaurants
- Offices
- Clinics
- Schools
- Warehouses
- Workshops
- Supermarkets
- Salons
- Financial institutions
Commercial property creates additional risks, including:
- Higher visitor traffic
- Business equipment
- Flammable stock
- Machinery
- Cooking operations
- Public Liability
- Loss of rental income
- Glass damage
- Signboards
- Basement parking
Every tenant’s business activity should be disclosed.
A building occupied by offices presents a different insurance exposure from one containing restaurants, workshops or chemical storage.
Insurance for Apartment Blocks and Gated Communities
Apartment developments may require cover for:
- Building structures
- Common areas
- Lifts
- Gates
- Clubhouses
- Swimming pools
- Gyms
- Boreholes
- Water tanks
- Parking areas
- Boundary walls
- Security equipment
- Property Owners’ Liability
- Employees
- Loss of service-charge income
The policy should clarify whether it is arranged by:
- Individual unit owner
- Developer
- Management company
- Residents’ association
- Body corporate
- Landlord
Duplicated or incomplete insurance can arise where different parties insure overlapping sections without coordinating values.
Insurance for Furnished Apartments and Airbnb Properties
Short-term rentals create different exposures from ordinary long-term tenancies.
These may include:
- Frequent changes of occupants
- Guest-related damage
- Theft of appliances
- Public Liability
- Loss of booking income
- Online booking risks
- Employee injuries
- Food or hospitality services
An ordinary landlord policy may require an endorsement or specialist hospitality arrangement where the property operates as:
- Airbnb
- Serviced apartment
- Holiday home
- Guest house
- Short-term corporate accommodation
The actual business use must be declared.
Insurance for Student Accommodation
Student hostels and rental developments may face:
- High occupancy
- Cooking risks
- Electrical overloading
- Theft
- Fire
- Public Liability
- Malicious damage
- Water damage
- Frequent tenant turnover
The insurer may request:
- Number of rooms
- Maximum occupants
- Fire equipment
- Emergency exits
- Security controls
- Building approvals
- Management arrangements
The landlord should not insure student accommodation using ordinary single-family residential information.
How Should a Rental Building Be Valued?
The building should generally be insured for its reinstatement or rebuilding cost.
This may include:
- Construction materials
- Labour
- Demolition
- Debris removal
- Architects’ fees
- Engineers’ fees
- Quantity-surveyor fees
- Statutory charges
- Inflation during reconstruction
It should not ordinarily include the value of the land.
Market value vs rebuilding value
The market value is the amount the property may sell for.
It may include:
- Land value
- Location
- Rental demand
- Investment value
- Neighbourhood development
The rebuilding value is the estimated cost of reconstructing the insured building after serious damage.
A building can have:
- High market value but lower rebuilding cost
- Low market value but high rebuilding cost
Insurance should use the correct valuation basis.
What Is Underinsurance?
Underinsurance occurs where the insured value is lower than the correct rebuilding or replacement value.
Suppose a rental building would cost KSh 50 million to rebuild but is insured for KSh 25 million.
If the policy contains an average condition, even a partial claim may be reduced because only half of the true value was insured.
Underinsurance may arise because the landlord:
- Uses the purchase price
- Excludes professional fees
- Fails to consider inflation
- Does not update values after renovations
- Insures only the outstanding loan
- Uses an outdated valuation
A professional property valuation can help establish the correct sum insured.
What Is an Indemnity Period?
The indemnity period is the maximum duration during which Loss of Rent or Business Interruption benefits may be payable after insured damage.
Common periods may include:
- Six months
- Twelve months
- Eighteen months
- Twenty-four months
- Thirty-six months
The landlord should consider how long it may take to:
- Demolish unsafe sections
- Obtain approvals
- Rebuild
- Replace lifts and equipment
- Reconnect utilities
- Obtain occupation approval
- Find replacement tenants
Selecting a short indemnity period may leave the owner without rental-income protection before the property is fully restored.
Does Landlord Insurance Cover Rent Arrears?
Ordinary Loss of Rent Insurance generally applies after insured physical damage makes the premises uninhabitable.
It does not normally cover rent that is unpaid because:
- The tenant loses employment
- The tenant’s business fails
- The tenant refuses to pay
- The tenant disappears
- The landlord and tenant have a dispute
- The unit is vacant
Rent-guarantee or legal-expenses insurance may be available separately in some markets, but availability and conditions should be confirmed.
Landlords should maintain:
- Written lease agreements
- Tenant identification
- Security deposits
- Payment records
- References
- Proper arrears-management procedures
Does Landlord Insurance Cover Eviction Costs?
Not ordinarily.
Eviction, rent recovery and tenancy disputes are legal and contractual matters.
Some legal-expenses or rent-protection solutions may cover selected costs, but these are not standard benefits under every property policy.
The landlord should seek appropriate legal advice and follow lawful tenancy procedures.
Does the Policy Cover Damage Caused by Tenants?
It depends on the cause and policy terms.
The policy may consider:
- Accidental damage
- Malicious damage
- Fire caused accidentally
- Water damage
- Theft following forcible entry
It may exclude:
- Normal wear and tear
- Gradual deterioration
- Poor cleaning
- Minor marks
- Unauthorised alterations
- Deliberate tenant damage without the relevant extension
- Damage known before the policy began
The landlord should:
- Conduct entry inspections
- Photograph the property
- Use an inventory
- Record the condition at checkout
- Maintain a security deposit
- Report serious damage promptly
Does Landlord Insurance Cover Vacant Property?
Vacant or unoccupied buildings create higher risks of:
- Theft
- Vandalism
- Fire
- Water damage
- Squatting
- Undetected leaks
- Delayed incident discovery
Many policies restrict cover after the property remains unoccupied for a stated period.
The landlord should notify the insurer where:
- A unit remains vacant for an extended period
- The building is awaiting renovation
- Construction has stopped
- Tenants have moved out
- The property is awaiting sale
The insurer may require:
- Security guards
- Regular inspections
- Utility controls
- Boarding of openings
- Removal of combustible materials
- Higher excesses
- Restricted cover
Does Landlord Insurance Cover Wear and Tear?
No, not ordinarily.
Landlord Insurance is intended for sudden and unforeseen insured events.
It does not normally pay for routine maintenance such as:
- Old paint
- Worn flooring
- Rusted pipes
- Ageing roofs
- Cracked sealant
- Gradually failing wiring
- Damaged fixtures from prolonged use
- Pest infestation
- Corrosion
Property owners remain responsible for regular maintenance.
Common Landlord Insurance Exclusions
Policies may exclude or restrict:
- Wear and tear
- Gradual deterioration
- Poor maintenance
- Existing damage
- Undeclared commercial use
- Unoccupied property
- Illegal activities
- Defective design
- Faulty workmanship
- Vermin
- Mould
- Pollution
- War
- Political violence unless extended
- Tenant theft without evidence
- Rent arrears
- Contractual penalties
- Deliberate acts by the insured
The full wording should be reviewed before purchasing cover.
How Much Does Landlord Insurance Cost in Kenya?
There is no universal premium.
The cost may depend on:
- Building value
- Location
- Construction type
- Occupancy
- Number of tenants
- Commercial activities
- Claims history
- Fire protection
- Security
- Loss-of-rent limit
- Liability limit
- Political-violence extension
- Flood exposure
- Policy excess
- Indemnity period
A small residential rental cannot be priced in the same way as a shopping centre, warehouse or multi-storey apartment block.
A current written quotation is required.
Information Required for a Landlord Insurance Quotation
Property details
- Physical address
- Type of building
- Number of units
- Year of construction
- Construction materials
- Number of floors
- Building value
- Contents value
- Occupancy level
Tenant details
- Residential or commercial tenants
- Tenant business activities
- Short-term or long-term occupation
- Student accommodation
- Restaurants or hazardous activities
- Vacant units
Rental information
- Monthly rental income
- Annual rental income
- Service-charge income
- Required indemnity period
- Existing mortgage
Safety and security
- Fire extinguishers
- Fire alarms
- Emergency exits
- Security guards
- CCTV
- Perimeter wall
- Access control
- Water-storage systems
- Electrical inspection
Claims information
- Previous fires
- Flood losses
- Burglary
- Liability claims
- Water damage
- Structural incidents
Accurate information allows the insurer to understand the real exposure.
Documents That May Be Required
The insurer may request:
- Title deed or ownership evidence
- Lease or management agreement
- Property valuation report
- Building plans
- Occupancy certificate
- Rental schedule
- Tenant schedule
- Photographs
- Previous policy
- Claims history
- KRA PIN
- Identification or company documents
- Fire-safety records
- Mortgage documents
The exact requirements depend on the property and insurer.
What Should a Landlord Do After Property Damage?
1. Protect people
Assist tenants, visitors and employees.
Contact emergency services where necessary.
2. Prevent further damage
Where safe:
- Turn off electricity
- Shut off water
- Secure openings
- Move undamaged property
- Arrange temporary security
3. Notify the insurer or intermediary
Report the incident immediately.
4. Take photographs and videos
Capture:
- Cause of damage
- Affected rooms
- Building exterior
- Damaged fixtures
- Water levels
- Fire damage
- Neighbouring property damage
5. Report to authorities
Police, fire-service or other reports may be required depending on the incident.
6. Preserve evidence
Do not dispose of damaged property before inspection unless necessary for safety.
7. Allow assessment
The insurer may appoint:
- Loss adjuster
- Engineer
- Quantity surveyor
- Investigator
- Valuer
8. Obtain repair quotations
Do not begin major repairs without insurer approval, except emergency measures needed to prevent further loss.
Documents Required for a Landlord Insurance Claim
Depending on the loss, the insurer may request:
- Claim form
- Policy schedule
- Ownership evidence
- Property valuation
- Police abstract
- Fire-brigade report
- Photographs
- Repair quotations
- Engineer’s report
- Rental schedule
- Lease agreements
- Proof of rental income
- Tenant statements
- Inventory
- Purchase receipts
- Bank statements
- Mortgage details
Loss-of-rent claims require evidence of actual income that would have been earned.
Common Mistakes Landlords Make
Insuring the property at market value
Insurance should generally use rebuilding cost rather than selling price.
Ignoring loss of rent
Repairing the building does not replace months of lost income.
Failing to disclose tenant activities
A restaurant, workshop or warehouse may materially increase the risk.
Using ordinary home insurance
Rental use should be declared.
Ignoring common-area liability
Landlords may be responsible for stairs, lifts, parking areas, gates and walkways.
Failing to insure furniture
Building cover does not automatically include movable contents.
Keeping outdated values
Inflation and renovations can cause underinsurance.
Ignoring vacant units
Long-term vacancy may restrict protection.
Failing to maintain the building
Insurance does not pay for gradual deterioration.
Choosing the cheapest quotation
A low premium may exclude flood, loss of rent, political violence or tenant damage.
How Landlords Can Reduce Property Risks
Maintain the building
Inspect:
- Roofs
- Electrical wiring
- Plumbing
- Balconies
- Staircases
- Lifts
- Fire equipment
- Drainage
- Boundary walls
Use written leases
The lease should address:
- Property use
- Maintenance duties
- Alterations
- Insurance responsibilities
- Prohibited activities
- Subletting
- Incident reporting
Screen tenants
Confirm:
- Identity
- Intended use
- Business activity
- References
- Occupancy levels
Maintain inventories
For furnished premises, record:
- Item descriptions
- Serial numbers
- Photographs
- Condition
- Replacement values
Install fire and security controls
Consider:
- Smoke detectors
- Extinguishers
- Alarms
- CCTV
- Security lighting
- Access control
- Emergency signage
Keep rental records
Maintain:
- Lease agreements
- Rent statements
- Bank records
- Tenant schedules
- Service-charge records
These are important during a Loss of Rent claim.
How to Compare Landlord Insurance Quotations
Give each insurer the same:
- Building value
- Contents value
- Rental income
- Occupancy details
- Tenant activities
- Claims history
- Required liability limit
- Required extensions
Then compare:
- Premium
- Covered perils
- Flood
- Earthquake
- Malicious damage
- Tenant damage
- Loss of rent
- Indemnity period
- Property Owners’ Liability
- Burglary
- Glass
- Machinery Breakdown
- Political Violence and Terrorism
- Excesses
- Unoccupancy conditions
- Warranties
- Exclusions
A professional comparison should identify what is missing—not merely which quotation is cheapest.
How Imana Helps Landlords Compare Property Insurance
Imana Insurance Agency Kenya Ltd helps residential and commercial landlords compare property-insurance quotations from suitable licensed insurers.
The process may include:
- Reviewing the type and use of the property.
- Establishing the building and contents values.
- Reviewing rental income.
- Identifying tenant and liability exposures.
- Selecting a suitable indemnity period.
- Comparing covered perils and extensions.
- Reviewing premiums, excesses and exclusions.
- Coordinating inspection and policy issuance.
- Managing policy amendments and renewals.
- Supporting claim notification.
Related solutions may include:
- Fire and Allied Perils
- Loss of Rent
- Public Liability
- Burglary
- Money Insurance
- Fidelity Guarantee
- Machinery Breakdown
- Electronic Equipment
- WIBA
- Political Violence and Terrorism
- Home Insurance
- Airbnb and Hospitality Insurance
- Commercial Property Insurance
Landlord Insurance in Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Imana supports landlords and property managers in:
- Westlands
- Kilimani
- Kileleshwa
- Lavington
- Parklands
- Riverside
- Gigiri
- Runda
- Karen
- Nairobi CBD
- Kiambu
- Machakos
- Kajiado
- Mombasa
- Nakuru
- Kisumu
- Other parts of Kenya
Website: www.imana.co.ke
Call or WhatsApp: +254 796 209 402
Protect the building. Protect the rental income. Protect yourself against liability. Let Imana handle the insurance comparison.
Frequently Asked Questions
What is Landlord Insurance?
It is insurance designed to protect rental-property owners against specified building damage, loss of rental income, contents loss and legal liability.
Is Landlord Insurance compulsory in Kenya?
It is not automatically compulsory for every landlord, but a bank, financier, lease, management agreement or commercial contract may require it.
Does Landlord Insurance cover tenants’ belongings?
Not ordinarily. Tenants should arrange their own contents insurance.
Does it cover unpaid rent?
Ordinary Loss of Rent Insurance normally applies after insured physical damage. It does not generally cover rent arrears caused by a tenant’s inability or refusal to pay.
Can furnished apartments be insured?
Yes. Landlord-owned furniture and appliances should be declared under the contents section.
Does the policy cover tenant damage?
It may cover specified accidental or malicious damage where the relevant extension is included. Wear and tear is generally excluded.
Can an Airbnb property use Landlord Insurance?
Possibly, but short-term rental use must be disclosed. A specialist hospitality or Airbnb package may be more suitable.
Does it cover an empty building?
Cover may be restricted after the property remains vacant for a stated period. Notify the insurer.
What value should I use for the building?
Use a professional estimate of the rebuilding cost, excluding land value.
What is Loss of Rent Insurance?
It protects eligible rental income lost while the property is uninhabitable following insured physical damage.
Does the policy cover injuries to tenants?
Property Owners’ Liability may cover eligible legal claims involving accidental injury arising from the insured premises.
Can one policy cover several rental properties?
Yes, subject to each location, value, use and rental income being declared.
Can Imana compare Landlord Insurance quotations?
Yes. Imana can compare property benefits, rental-income protection, liability limits, premiums, excesses and exclusions from suitable insurers.
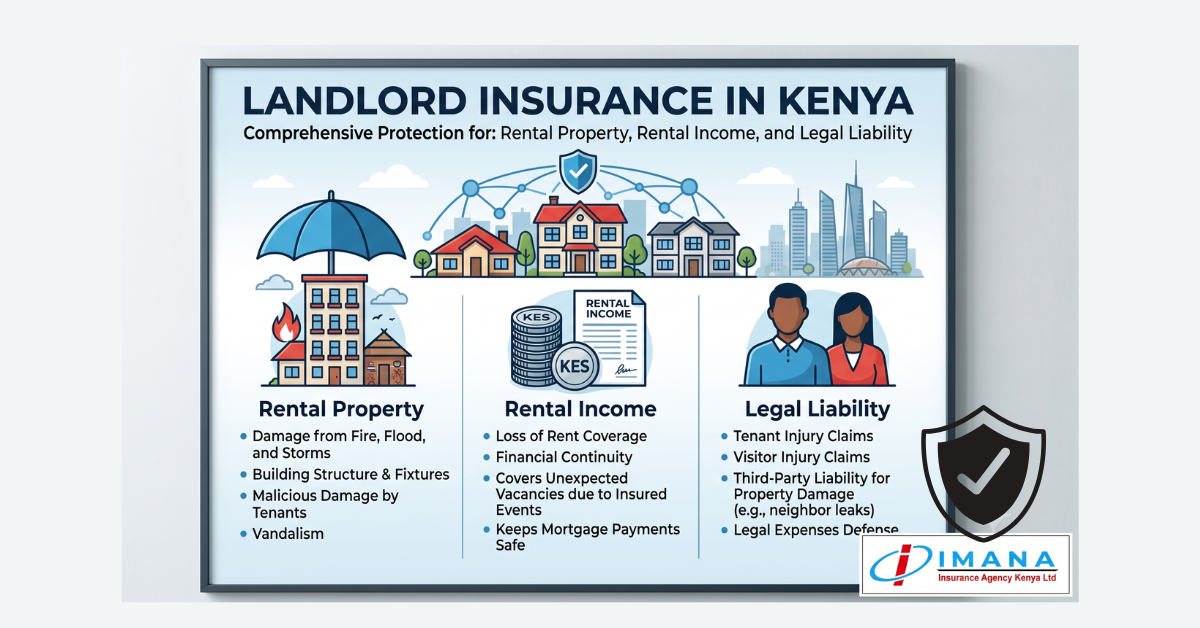
The Bottom Line
Landlords face three major financial risks:
- Damage to the building
- Loss of rental income
- Legal liability involving tenants, visitors or neighbouring property
A suitable Landlord Insurance policy should address these exposures using accurate building values and clear information about how the property is used.
Before purchasing cover:
- Obtain an appropriate building valuation.
- Exclude land value from the sum insured.
- Declare every tenant activity.
- Insure landlord-owned contents.
- Include realistic Loss of Rent protection.
- Select an adequate liability limit.
- Review vacancy conditions.
- Compare excesses and exclusions.
- Maintain the property properly.
- Keep leases and rental records.
A rental property should continue protecting your financial future—not become a financial burden after one serious incident.
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call or WhatsApp: +254 796 209 402
Website: www.imana.co.ke
Protect the property. Preserve the income. Manage the liability. Let Imana handle the insurance.
Landlord Insurance premiums, insured perils, loss-of-rent benefits, liability limits, excesses, vacancy conditions and exclusions vary between insurers. This article provides general information and does not replace a property valuation, legal advice, a current quotation or the complete policy wording.