
Blog Details
Diskava. Beta. Kava
29Jul
Imana Afya Medical Cover Kenya | Inpatient, Maternity & Outpatient Insurance
Get Imana Afya Medical Cover for individuals, families, groups and companies in Kenya. Enjoy inpatient cover up to KSh 500,000, maternity up to KSh 75,000 and optional outpatient benefits.
Affordable Medical Insurance for Individuals, Families and Businesses
Medical bills rarely arrive at a convenient time.
An unexpected hospital admission, pregnancy complication, chronic illness or emergency procedure can quickly affect a family’s savings or disrupt a business’s finances. Medical insurance provides a structured way to prepare for these expenses before treatment becomes necessary.
Imana Afya Medical Cover is an affordable health insurance solution designed for:
- Individuals
- Couples and families
- Organised groups
- Employers and corporate organisations
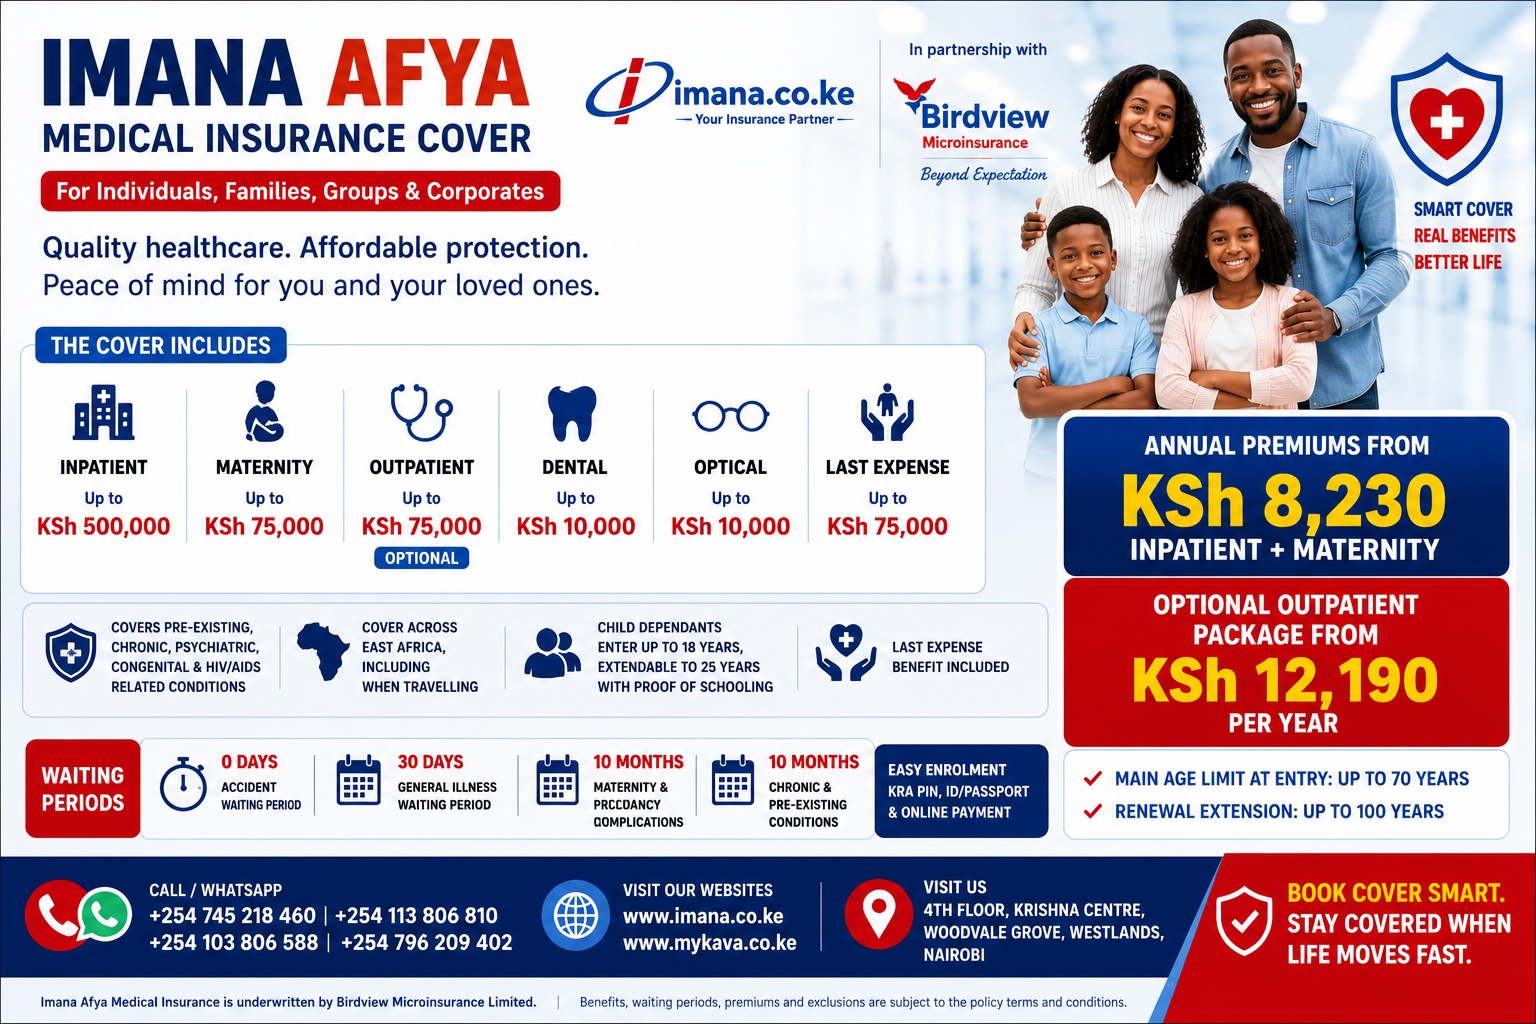
The cover combines inpatient, maternity, outpatient, dental, optical and last-expense benefits, with annual premiums starting from KSh 8,230 for the inpatient and maternity option. An optional outpatient package starts from KSh 12,190 annually, depending on the selected membership structure and applicable policy terms.
What Does Imana Afya Medical Insurance Cover?
Imana Afya provides a clear benefit structure intended to address both hospital admission and everyday healthcare needs.
Inpatient Cover of Up to KSh 500,000
The plan provides an inpatient limit of up to:
KSh 500,000 per insured member
Inpatient insurance applies when an insured person is admitted to hospital for covered treatment.
Subject to the policy wording, inpatient benefits may help meet eligible costs associated with:
- Hospital accommodation
- Doctors’ and specialists’ fees
- Theatre charges
- Surgical procedures
- Prescribed medication
- Diagnostic tests
- Nursing care
- Treatment arising from covered illnesses or accidents
The KSh 500,000 limit represents the maximum inpatient benefit available under the presented option, subject to any applicable sublimits, waiting periods and exclusions.
Maternity Cover of Up to KSh 75,000
Imana Afya includes a maternity benefit of up to:
KSh 75,000
The maternity benefit may assist with eligible costs arising from childbirth and pregnancy-related hospital treatment, subject to the applicable waiting period and policy conditions.
Depending on the policy wording, maternity benefits may include:
- Normal delivery
- Caesarean-section delivery
- Pregnancy complications
- Hospital accommodation
- Medical procedures related to delivery
Anyone planning to start or grow a family should purchase maternity insurance early. Maternity benefits normally have a waiting period, meaning cover bought after pregnancy has already begun may not apply to that pregnancy.
Optional Outpatient Cover of Up to KSh 75,000
Clients can add an outpatient benefit of up to:
KSh 75,000
Outpatient insurance covers eligible treatment where the patient visits a hospital, clinic or medical provider without being admitted overnight.
The outpatient option may help with covered expenses such as:
- General consultations
- Specialist consultations
- Prescribed medication
- Laboratory tests
- Diagnostic procedures
- Follow-up appointments
- Management of certain chronic conditions
The outpatient package is optional and is priced separately from the inpatient and maternity option.
According to the premium guide, outpatient cover starts from KSh 12,190 annually for a principal member. The applicable premium for a member with dependants may differ according to the selected family structure.
Dental Cover of Up to KSh 10,000
The medical plan includes dental benefits of up to:
KSh 10,000
Dental benefits may include eligible treatment such as:
- Dental consultations
- Extractions
- Fillings
- Scaling
- Treatment of gum conditions
- Dental X-rays
- Prescribed dental medication
Dental treatment remains subject to the benefit limit, provider requirements and policy exclusions.
Optical Cover of Up to KSh 10,000
Imana Afya also provides an optical benefit of up to:
KSh 10,000
The benefit may assist with eligible costs relating to:
- Eye examinations
- Optometrist consultations
- Prescribed lenses
- Optical prescriptions
- Approved frames
- Treatment of covered eye conditions
Clients should confirm whether the dental and optical limits operate independently or under a combined benefit structure before purchasing the policy.
Last Expense Benefit of Up to KSh 75,000
The policy includes a last-expense benefit of up to:
KSh 75,000
Last-expense insurance provides financial support to the insured member’s nominated beneficiaries following the member’s death, subject to the policy conditions.
This benefit may help a family meet urgent funeral and related expenses during a difficult period.
It should not be confused with a full life insurance policy. The amount payable is limited to the last-expense benefit stated in the policy schedule.
Cover for Pre-Existing and Chronic Conditions
A significant feature of Imana Afya is the inclusion of benefits relating to certain:
- Pre-existing medical conditions
- Chronic illnesses
- Psychiatric conditions
- Congenital conditions
- HIV/AIDS-related conditions
These conditions are covered subject to the applicable waiting periods, benefit limits, exclusions and policy definitions.
A pre-existing condition generally refers to an illness, symptom, diagnosis or medical condition that existed before the insurance policy started.
Applicants should disclose medical information accurately when completing the application. Failure to disclose relevant information may affect treatment approval or claim settlement.
East Africa Medical Coverage
Imana Afya provides territorial cover within East Africa, including when an insured member travels within the region.
This may be valuable for:
- People who travel regularly within East Africa
- Families with children studying in neighbouring countries
- Regional business travellers
- Employees working across different East African countries
- Individuals who divide their time between Kenya and another regional country
Territorial cover does not necessarily mean that every medical provider operates on a direct-payment basis. Before seeking treatment outside Kenya, members should confirm the applicable hospital network, approval process and reimbursement requirements.
Who Is Eligible to Join?
The main entry age for adults is up to:
70 years
Existing members may qualify for renewal extensions up to:
100 years
The renewal extension is subject to continuous cover and the insurer’s policy terms.
The distinction between entry and renewal age matters.
A person who is older than the maximum entry age may not qualify to join as a new member. However, someone who joined earlier may continue renewing beyond the entry age, subject to the applicable conditions.
Child Dependants
Children may enter the plan as dependants up to age 18.
Dependant status may be extended up to age 25 where the child remains in recognised education and proof of schooling is provided.
This makes the cover suitable for families with:
- Young children
- Teenagers
- University or college students
- Dependants in full-time education
Parents should confirm the documents required when adding or renewing an older dependant.
How Much Does Imana Afya Medical Cover Cost?
The annual premium depends on whether the applicant is joining alone or including dependants.
Inpatient and Maternity Package
The package provides:
- Inpatient cover of KSh 500,000
- Maternity cover of KSh 75,000
Indicative annual premiums are:
- Principal member only: KSh 8,230
- Principal member plus one dependant: KSh 12,345
- Principal member plus two dependants: KSh 13,826
- Principal member plus three dependants: KSh 15,308
- Principal member plus four dependants: KSh 16,789
- Principal member plus five dependants: KSh 18,271
Optional Outpatient Package
The outpatient option provides:
- Outpatient cover of KSh 75,000
- Dental benefit of KSh 10,000
- Optical benefit of KSh 10,000
The indicative annual premium starts from:
- Principal member only: KSh 12,190
- Principal member with dependants: KSh 21,940, based on the membership combinations shown in the presentation
These premiums are indicative and annual. Final pricing remains subject to the insurer’s acceptance, membership details and policy terms.
Is the Outpatient Premium Included in the KSh 8,230?
No.
The KSh 8,230 starting premium applies to the inpatient and maternity package for a principal member.
The outpatient, dental and optical option is selected separately and starts from KSh 12,190 annually.
A client who wants both inpatient and outpatient benefits should request a complete quotation showing the total annual premium for the chosen membership structure.
Medical Cover for Individuals
An individual can purchase Imana Afya without waiting to join an employer-sponsored medical scheme.
Individual cover may suit:
- Self-employed professionals
- Freelancers
- Small-business owners
- Consultants
- People between jobs
- Young adults leaving a parent’s medical scheme
- Retirees within the eligible entry age
- Individuals whose employer does not provide medical insurance
Taking out an individual policy gives the member control over the selected benefits and renewal arrangements.
Family Medical Insurance
Families can use the membership structure to include a principal member and eligible dependants.
Before selecting a family plan, consider:
- The number of dependants
- The age of each member
- Expected outpatient usage
- Maternity requirements
- Chronic medical needs
- Preferred hospitals
- Dental and optical requirements
- Applicable waiting periods
- The total annual premium
A lower premium may appear attractive, but the selected benefit limits should still be sufficient for the family’s likely healthcare needs.
Group and Corporate Medical Insurance
Imana Afya is also available for groups and corporate clients.
It may be suitable for:
- SMEs
- Professional firms
- Schools
- Associations
- Chamas
- NGOs
- Community organisations
- Companies seeking affordable employee medical benefits
Group medical insurance can help employers improve employee welfare, support staff retention and reduce the financial disruption caused by unexpected medical expenses.
A group quotation will depend on:
- Number of members
- Number of dependants
- Age distribution
- Selected benefit structure
- Industry or occupation
- Claims experience, where applicable
- Additional benefit requirements
Businesses should prepare accurate member data before requesting quotations.
What Documents Are Required?
The presentation provides a simplified enrolment process.
Applicants may be required to provide:
- KRA PIN
- National identity card or passport copy
- Dependant information
- Proof of schooling for eligible older dependants
- Completed application information
- Premium-payment confirmation
Additional information may be requested depending on the applicant, membership category and underwriting requirements.
What Should You Check Before Buying?
Before paying for the medical policy, review the following carefully.
Waiting periods
Ask when benefits for general illness, maternity, chronic conditions and pre-existing conditions become active.
Hospital network
Confirm whether your preferred hospitals, clinics, doctors and pharmacies are included.
Pre-authorisation
Some procedures, diagnostic tests and planned admissions may require approval before treatment.
Benefit sublimits
The overall inpatient limit may not apply equally to every treatment category.
Exclusions
Review treatments, conditions and expenses that the policy does not cover.
Claims procedure
Understand what to do during an emergency, planned admission or outpatient visit.
Membership structure
Confirm that every dependant is correctly listed and eligible.
Written confirmation
Do not begin using the policy until cover has been confirmed in writing.
How Imana Makes Medical Insurance Easier
Imana Insurance Agency Kenya Ltd helps individuals, families and employers understand the policy before purchasing it.
The team can assist clients to:
- Review the available benefit structure
- Confirm the appropriate family composition
- Understand the inpatient and outpatient options
- Explain maternity and dependant conditions
- Review applicable waiting periods
- Organise enrolment documents
- Complete the application
- Obtain written confirmation of cover
- Receive support during renewals and claims enquiries
Medical insurance should not be selected from a premium figure alone. Clients should understand what the policy covers, when each benefit becomes available and what conditions apply.
Imana Afya Medical Insurance in Westlands, Nairobi
Imana Insurance Agency Kenya Ltd serves clients from its office at:
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
The office is accessible to individuals and businesses around:
- Westlands
- Sarit Centre
- Westgate
- Parklands
- Riverside
- Spring Valley
- Gigiri
- Runda
- Lavington
- Kitisuru
- Muthaiga
- Nairobi CBD
Clients outside Nairobi can request quotations, submit documents and receive assistance through online and mobile channels.
Request an Imana Afya Medical Insurance Quote
Do not wait until someone needs hospital treatment before arranging medical insurance.
Review the benefits, understand the waiting periods and select cover while you still have time to make a calm decision.
Apply online:
Websites:
Office: 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call/WhatsApp: +254 796 209 402
Compare medical insurance quotations, understand the benefits and choose protection that fits your family or organisation.
Frequently Asked Questions
What is the maximum inpatient limit under Imana Afya?
The presented plan provides inpatient cover of up to KSh 500,000.
Does Imana Afya include maternity insurance?
Yes. The plan includes a maternity benefit of up to KSh 75,000, subject to the applicable waiting period and policy conditions.
Is outpatient cover included in the KSh 8,230 premium?
No. The KSh 8,230 starting premium relates to the inpatient and maternity package. Outpatient cover is an optional, separately priced benefit.
What is the maximum outpatient limit?
The optional outpatient benefit is up to KSh 75,000.
Are dental and optical benefits included?
The optional outpatient package provides dental and optical benefits of up to KSh 10,000 each, subject to the policy terms.
Does the policy cover pre-existing conditions?
Certain pre-existing, chronic, psychiatric, congenital and HIV/AIDS-related conditions may be covered after the applicable waiting periods and within the policy limits.
What is the maximum joining age?
New adult members may join up to age 70.
Can the policy continue after age 70?
Existing members may qualify for renewal extensions up to age 100, subject to continuous cover and policy conditions.
Can children be included?
Yes. Child dependants can enter up to age 18, with possible extension to age 25 for those in recognised education and supported by proof of schooling.
Does the cover apply outside Kenya?
The plan provides East Africa territorial cover, subject to its hospital, authorisation and reimbursement conditions.
Can companies purchase Imana Afya for employees?
Yes. The cover is available for groups and corporate organisations, subject to quotation and membership requirements.
Are the premiums final?
The amounts shown are indicative annual premiums. Final premiums and acceptance terms are subject to confirmation by the insurer.
Premiums, benefits, waiting periods, provider access, exclusions and claims are subject to the insurer’s underwriting requirements, policy schedule and full policy wording. Applicants should obtain written confirmation of cover before seeking treatment.