
Blog Details
Diskava. Beta. Kava
30Jul
How to Compare Insurance Quotations in Kenya | Complete Guide
Learn how to compare insurance quotations in Kenya by reviewing premiums, benefits, exclusions, excesses, waiting periods and claims terms. Get multiple quotes through Imana Insurance Agency Kenya Ltd.
Why Comparing Insurance Quotations Matters
Buying insurance without comparing quotations is like buying a vehicle after seeing only one model.
You may still get a suitable policy, but you will not know whether another insurance company could offer better benefits, a more manageable excess, more flexible payment terms or a lower premium for similar protection.
Insurance companies assess risks differently. Two insurers reviewing the same vehicle, family, business or construction project may offer different:
- Premiums
- Policy limits
- Excesses
- Benefits
- Exclusions
- Payment arrangements
- Claims conditions
That is why customers should compare insurance quotations in Kenya before paying.
However, comparison does not mean choosing the lowest price automatically. The purpose is to identify the policy that provides the most suitable protection at a fair and sustainable cost.
The Insurance Regulatory Authority maintains a public registry of licensed insurers, agents, brokers and other insurance entities. Customers should verify the insurer and intermediary before purchasing any cover. (Insurance Regulatory Authority)
What Is an Insurance Quotation?
An insurance quotation is an insurer’s proposed price and preliminary terms for covering a particular risk.
The quotation is normally based on information provided by the customer, such as:
- The item or person being insured
- The required type of cover
- The value or limit requested
- Previous claims
- Age and occupation
- Vehicle usage
- Business activities
- Number of employees
- Travel destination
- Construction value
- Medical-benefit requirements
A quotation is not always the final insurance contract.
Cover normally becomes effective after:
- The customer accepts the quotation.
- The insurer approves the risk.
- The required premium is paid.
- The insurer issues written confirmation, a policy schedule or certificate.
Do not assume you are insured simply because a quotation has been issued.
Why Insurance Quotations Differ Between Companies
Insurance premiums are based on risk.
Each insurer uses its own underwriting guidelines, claims experience, target market, reinsurance arrangements and pricing strategy.
One insurer may be highly competitive for private motor insurance but less competitive for commercial vehicles. Another may offer stronger medical benefits, while a third may specialise in engineering, marine or liability risks.
The quotation may also change because of:
- The policyholder’s claims history
- The age or value of the insured property
- The selected limit
- The level of excess
- Optional extensions
- Location
- Occupation or industry
- Risk-management controls
- Number of people insured
- Hospital or garage network
- Policy duration
A lower price does not necessarily mean that one insurer is better than another. It may mean the policy has narrower benefits or that the insurer views that particular risk more favourably.
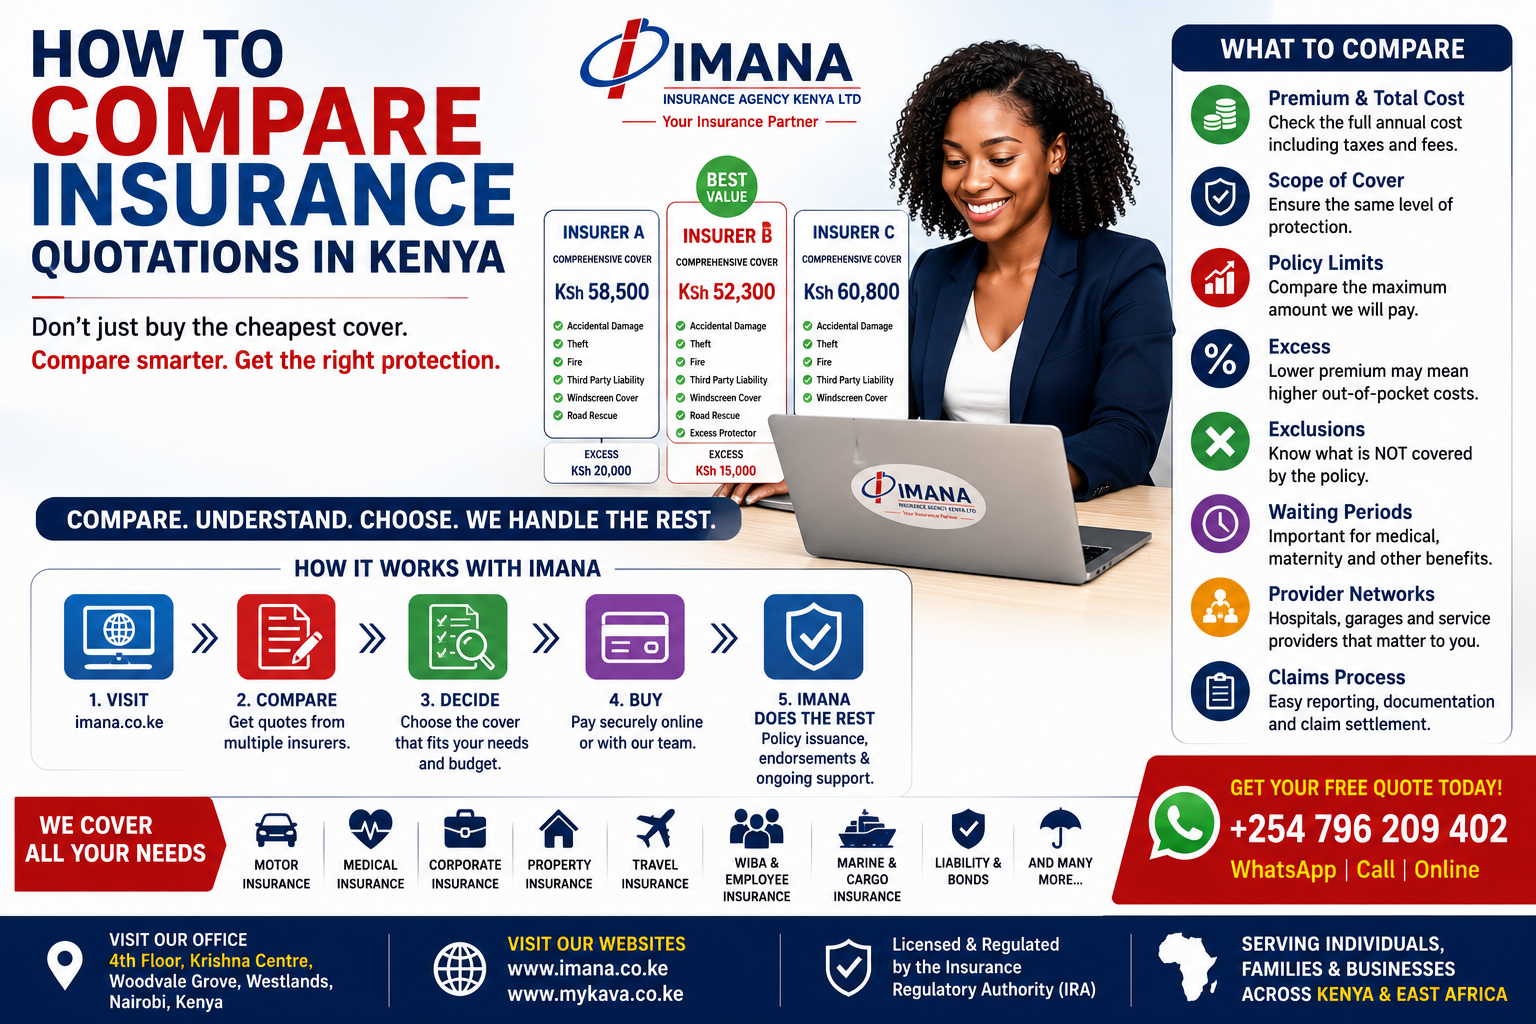
The Right Way to Compare Insurance Quotes
A proper comparison should evaluate the entire policy offer—not just the annual premium.
1. Confirm That the Quotations Use the Same Information
Before comparing prices, ensure every insurer received the same risk details.
For motor insurance, all insurers should quote using the same:
- Vehicle value
- Cover type
- Usage
- Year of manufacture
- Vehicle class
- Optional extensions
For medical insurance, compare quotations using the same:
- Ages
- Family composition
- Inpatient limit
- Outpatient limit
- Maternity requirement
- Dental and optical benefits
- Hospital-network preference
For business insurance, use consistent:
- Asset values
- Payroll
- Turnover
- Employee numbers
- Liability limits
- Project values
- Business activities
A quotation based on incomplete or different information cannot be compared fairly.
2. Compare the Scope of Cover
The scope of cover explains which risks are insured.
For example, motor insurance may be offered as:
- Third-Party Only
- Third Party, Fire and Theft
- Comprehensive
Medical insurance may be:
- Inpatient only
- Outpatient only
- Inpatient plus outpatient
- Individual
- Family-shared
- Per-person
- Corporate or group cover
Property insurance may cover:
- Fire only
- Fire and allied perils
- Burglary
- All risks
- Business interruption
- Public liability
Confirm that every quotation offers the same general level of protection.
3. Examine the Premium
The premium is the amount charged for the insurance.
When reviewing the premium, check:
- Total annual amount
- Taxes and levies
- Policy fees
- Instalment charges
- Minimum premium
- Deposit required
- Payment deadlines
- Whether optional benefits are included
A quotation may appear cheaper because an extension has been removed or because the payment shown is only the first instalment.
Always ask for the total annual cost.
4. Compare Policy Limits
The policy limit is the maximum amount the insurer may pay under a particular section.
For medical insurance, review:
- Overall inpatient limit
- Outpatient limit
- Maternity limit
- Dental limit
- Optical limit
- Chronic-condition limit
- Last-expense benefit
For liability insurance, review:
- Limit per claim
- Annual aggregate
- Legal defence costs
- Third-party property-damage limit
For property insurance, confirm:
- Building value
- Contents value
- Stock value
- Business-interruption limit
- Debris-removal limit
Two policies may have the same premium while offering very different limits.
5. Understand the Excess
An excess is the portion of an insured claim that the policyholder must pay.
For example, where a policy has an excess of KSh 20,000 and an approved claim is KSh 100,000, the policyholder may be required to meet the first KSh 20,000, subject to the policy terms.
Excesses may be:
- Fixed amounts
- Percentages
- Subject to minimum amounts
- Different for theft, flood or young drivers
- Applied to every claim
A low premium combined with a very high excess may be difficult to use during a claim.
Ask whether an excess protector can be added where available.
6. Read the Exclusions
Exclusions describe circumstances the insurer will not cover.
Common exclusions may include:
- Wear and tear
- Deliberate acts
- Undisclosed business use
- Unlicensed drivers
- Pre-existing damage
- Mechanical breakdown
- Certain medical treatments
- War and terrorism
- Fraud or non-disclosure
- Contractual penalties
- Gradual deterioration
Insurance product documents and policy wordings are part of Kenya’s regulated insurance-product framework. The Insurance Products Guidelines emphasise product documentation and transparency within the product-approval process. (Kenya Law)
A policy with many restrictive exclusions may offer less practical protection even where the premium is attractive.
7. Check Waiting Periods
Waiting periods are particularly important in medical, maternity, life and last-expense insurance.
A waiting period is the time between the policy’s effective date and the date when a specified benefit becomes available.
Waiting periods may apply to:
- General illness
- Maternity
- Pregnancy complications
- Surgery
- Chronic illnesses
- Pre-existing conditions
- Last-expense benefits
Never assume all benefits begin immediately.
Ask the insurer or intermediary to explain each waiting period in writing.
8. Review Provider Networks
Some policies restrict customers to approved providers.
These may include:
- Hospitals
- Clinics
- Pharmacies
- Motor garages
- Repair centres
- Medical specialists
- Roadside-rescue providers
For medical insurance, confirm that your preferred hospitals are available under the exact plan—not merely listed somewhere on the insurer’s general network.
For motor insurance, check whether repairs must be completed at an approved garage.
A strong benefit limit may be less valuable where the provider network is inconvenient or highly restricted.
9. Compare Optional Extensions
Optional extensions can significantly improve a policy.
Motor-insurance additions may include:
- Excess protector
- Political violence and terrorism
- Windscreen cover
- Road rescue
- Courtesy car
- Personal accident
- COMESA Yellow Card
Corporate-insurance extensions may include:
- Loss of profits
- Additional legal liability
- Debris removal
- Cross liability
- Employee dishonesty
- Cyber protection
Medical options may include:
- Maternity
- Dental
- Optical
- Chronic-condition benefits
- Overseas treatment
- Last expense
Confirm whether each extension is included in the premium or priced separately.
10. Examine the Claims Process
Insurance becomes most important when a claim occurs.
Before buying, ask:
- How do I report a claim?
- Is there a 24-hour contact?
- Which documents are required?
- How does pre-authorisation work?
- Who appoints the assessor?
- Can I choose my repairer?
- How are reimbursements handled?
- What is the expected communication process?
- Which deadlines must I observe?
Do not rely entirely on informal statements such as “this company pays claims quickly.”
Ask for the actual process and policy requirements.
11. Verify the Insurance Company and Intermediary
Before paying, verify that the insurer and the insurance intermediary are currently licensed.
The IRA’s 2026 registry includes licensed insurers and intermediaries, while its online entities registry allows users to search by category. (Insurance Regulatory Authority)
Also confirm:
- Official company name
- Policy underwriter
- Payment account
- Agency or broker name
- Official receipt
- Policy or certificate number
- Period of insurance
Avoid sending money to an individual’s personal number unless it is an officially authorised and verifiable payment channel.
12. Consider Financial Sustainability
The best policy is not useful if you cannot maintain it.
Consider whether you can afford:
- The initial premium
- Future renewals
- Policy excess
- Medical co-payments
- Instalment commitments
- Items excluded from cover
Choosing an extremely high medical limit or comprehensive package may sound attractive, but the policy must remain affordable over time.
Consistent cover is often better than purchasing an expensive plan that you cannot renew.
How to Compare Motor Insurance Quotations in Kenya
Motor quotations should be compared using the same vehicle details and value.
Check:
- Cover type
- Annual premium
- Minimum premium
- Vehicle value
- Standard excess
- Theft excess
- Young-driver excess
- Windscreen limit
- Political-violence cover
- Road rescue
- Courtesy car
- Authorised garages
- Instalment terms
Comprehensive insurance protects your own vehicle against covered damage, while Third-Party Only generally addresses legal liability to other people.
Do not choose Third-Party Only simply because it is cheaper if you cannot afford to repair or replace your own vehicle after an accident.
Request a motor quotation:
https://imana.co.ke/motor-quote
How to Compare Medical Insurance Quotations
Medical-insurance quotations can be difficult to compare because every insurer structures benefits differently.
Review:
- Inpatient limit
- Outpatient limit
- Maternity
- Dental and optical benefits
- Chronic-condition cover
- Pre-existing-condition terms
- Entry age
- Renewal age
- Hospital panel
- Co-payments
- Waiting periods
- Family-shared or per-person benefits
- Territorial scope
The cheapest medical policy may have a small hospital network, restrictive sublimits or long waiting periods.
Compare medical insurance:
https://imana.co.ke/insurance/health-insurance
How to Compare Corporate Insurance Quotations
Businesses should first create an accurate schedule of their risks.
This may include:
- Vehicles
- Property
- Stock
- Equipment
- Payroll
- Employees
- Contracts
- Revenue
- Liability exposures
- Goods in transit
- Cyber systems
When comparing corporate quotations, ensure insurers use the same declared values and limits.
Review:
- WIBA rates
- Liability limits
- Property excesses
- Business-interruption periods
- Claims conditions
- Risk-improvement requirements
- Policy warranties
- Payment terms
A business should not renew insurance automatically without checking whether its assets, payroll and operations have changed.
Corporate quotation page:
https://imana.co.ke/insurance/corporate-insurance
Common Mistakes When Comparing Insurance Quotes
Choosing the Cheapest Policy Automatically
A low premium may reflect reduced cover, higher excesses or more restrictive benefits.
Failing to Compare Like for Like
Do not compare comprehensive cover against Third-Party Only or a KSh 500,000 medical plan against a KSh 100,000 plan.
Ignoring Exclusions
A benefit advertised in large print may be limited by exclusions in the policy wording.
Providing Inaccurate Information
Incorrect vehicle use, health information, payroll or property values can affect the validity of the quotation and future claims.
Paying Before Checking the Underwriter
Always confirm which insurance company will issue the policy.
Relying on Verbal Promises
Important benefits and extensions should appear in the written quotation or policy.
Ignoring the Excess
The premium may be affordable, but the excess may be difficult to pay after a claim.
Not Checking the Policy Schedule
After purchase, check that names, registration numbers, sums insured, dates and policy classes are correct.
Why Compare Quotes Through an Insurance Intermediary?
Approaching one insurance company normally produces one company’s quotation.
An insurance intermediary can help customers obtain and review options from several insurers, subject to the insurers’ underwriting appetite.
The intermediary may assist with:
- Collecting risk information
- Requesting quotations
- Presenting comparisons
- Explaining policy terms
- Organising documents
- Coordinating payment and issuance
- Processing endorsements
- Renewal assistance
- Claims guidance
The insurance company remains responsible for underwriting the policy and assessing valid claims.
How Imana Makes Insurance Comparison Easier
Imana Insurance Agency Kenya Ltd is a digital-first insurance intermediary based in Westlands, Nairobi.
The agency helps individuals, families, motorists and businesses compare quotations for:
- Motor insurance
- Medical insurance
- Travel insurance
- WIBA
- Corporate insurance
- Property insurance
- Professional indemnity
- Marine insurance
- Contractors All Risks
- Bonds
- Personal accident
- Other specialist covers
Imana’s website provides quotation access for motor, medical, life, corporate and other products. (imana.co.ke)
The process is straightforward:
- Visit www.imana.co.ke.
- Submit the required information.
- Receive suitable quotation options.
- Compare premiums and terms.
- Select the preferred cover.
- Pay through an approved channel.
- Receive policy confirmation and continuing support.
You compare. You decide. You buy. Imana coordinates the rest.
Insurance Comparison Services in Westlands, Nairobi
Imana Insurance Agency Kenya Ltd is located at:
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
The office is convenient for customers around:
- Sarit Centre
- Westgate
- Parklands
- Riverside
- Spring Valley
- Lavington
- Kitisuru
- Gigiri
- Runda
- Muthaiga
- Nairobi CBD
Clients outside Nairobi can submit quotation requests and documents through digital channels.
Call or WhatsApp: +254 796 209 402
Website: www.imana.co.ke
Compare Insurance Quotations Today
Insurance is not just a certificate, card or policy schedule.
It is a financial promise that must match the risk you want to protect.
Before buying:
- Compare the cover
- Compare the limits
- Compare the excess
- Compare exclusions
- Understand the claims process
- Verify the insurer
- Choose a premium you can sustain
Do not buy blindly because a quotation is cheap or because a salesperson says the offer expires today.
Take time to understand what you are paying for.
The right insurance quotation is not necessarily the lowest. It is the option that gives you suitable protection, clear terms and dependable value.
Frequently Asked Questions
How many insurance quotations should I compare?
Comparing at least three suitable quotations can help reveal differences in price and benefits, although availability depends on the type of risk.
Is the cheapest insurance quotation the best?
Not necessarily. It may have lower limits, higher excesses, restrictive exclusions or fewer benefits.
Does requesting an insurance quotation mean I am covered?
No. Cover normally begins after acceptance, payment, underwriting approval and written confirmation.
Can I compare insurance quotations online in Kenya?
Yes. Online agencies such as Imana allow customers to submit details and receive quotation options digitally.
What should I compare in motor-insurance quotes?
Compare the premium, cover type, vehicle value, excesses, extensions, garage network and payment terms.
What should I compare in medical-insurance quotes?
Compare inpatient and outpatient limits, hospital networks, waiting periods, maternity, chronic-condition benefits and co-payments.
Can I change insurers at renewal?
Yes, subject to the new insurer’s acceptance. Ensure there is no gap in cover and confirm how previous medical or professional-indemnity continuity will be treated.
How can I verify an insurer in Kenya?
Use the Insurance Regulatory Authority’s current licensed-entities registry. (Insurance Regulatory Authority)
Does Imana compare insurance quotations?
Yes. Imana helps customers compare suitable quotations from different insurers, depending on product availability and underwriting requirements.
Insurance quotations, premiums, benefits, exclusions and claims are subject to the selected insurer’s underwriting requirements, policy schedule and complete policy wording. Customers should verify insurers and intermediaries through the Insurance Regulatory Authority before purchasing cover.