
Blog Details
Diskava. Beta. Kava
05Sep
PSV Insurance Quotes Kenya | Taxi, Matatu and Bus Guide
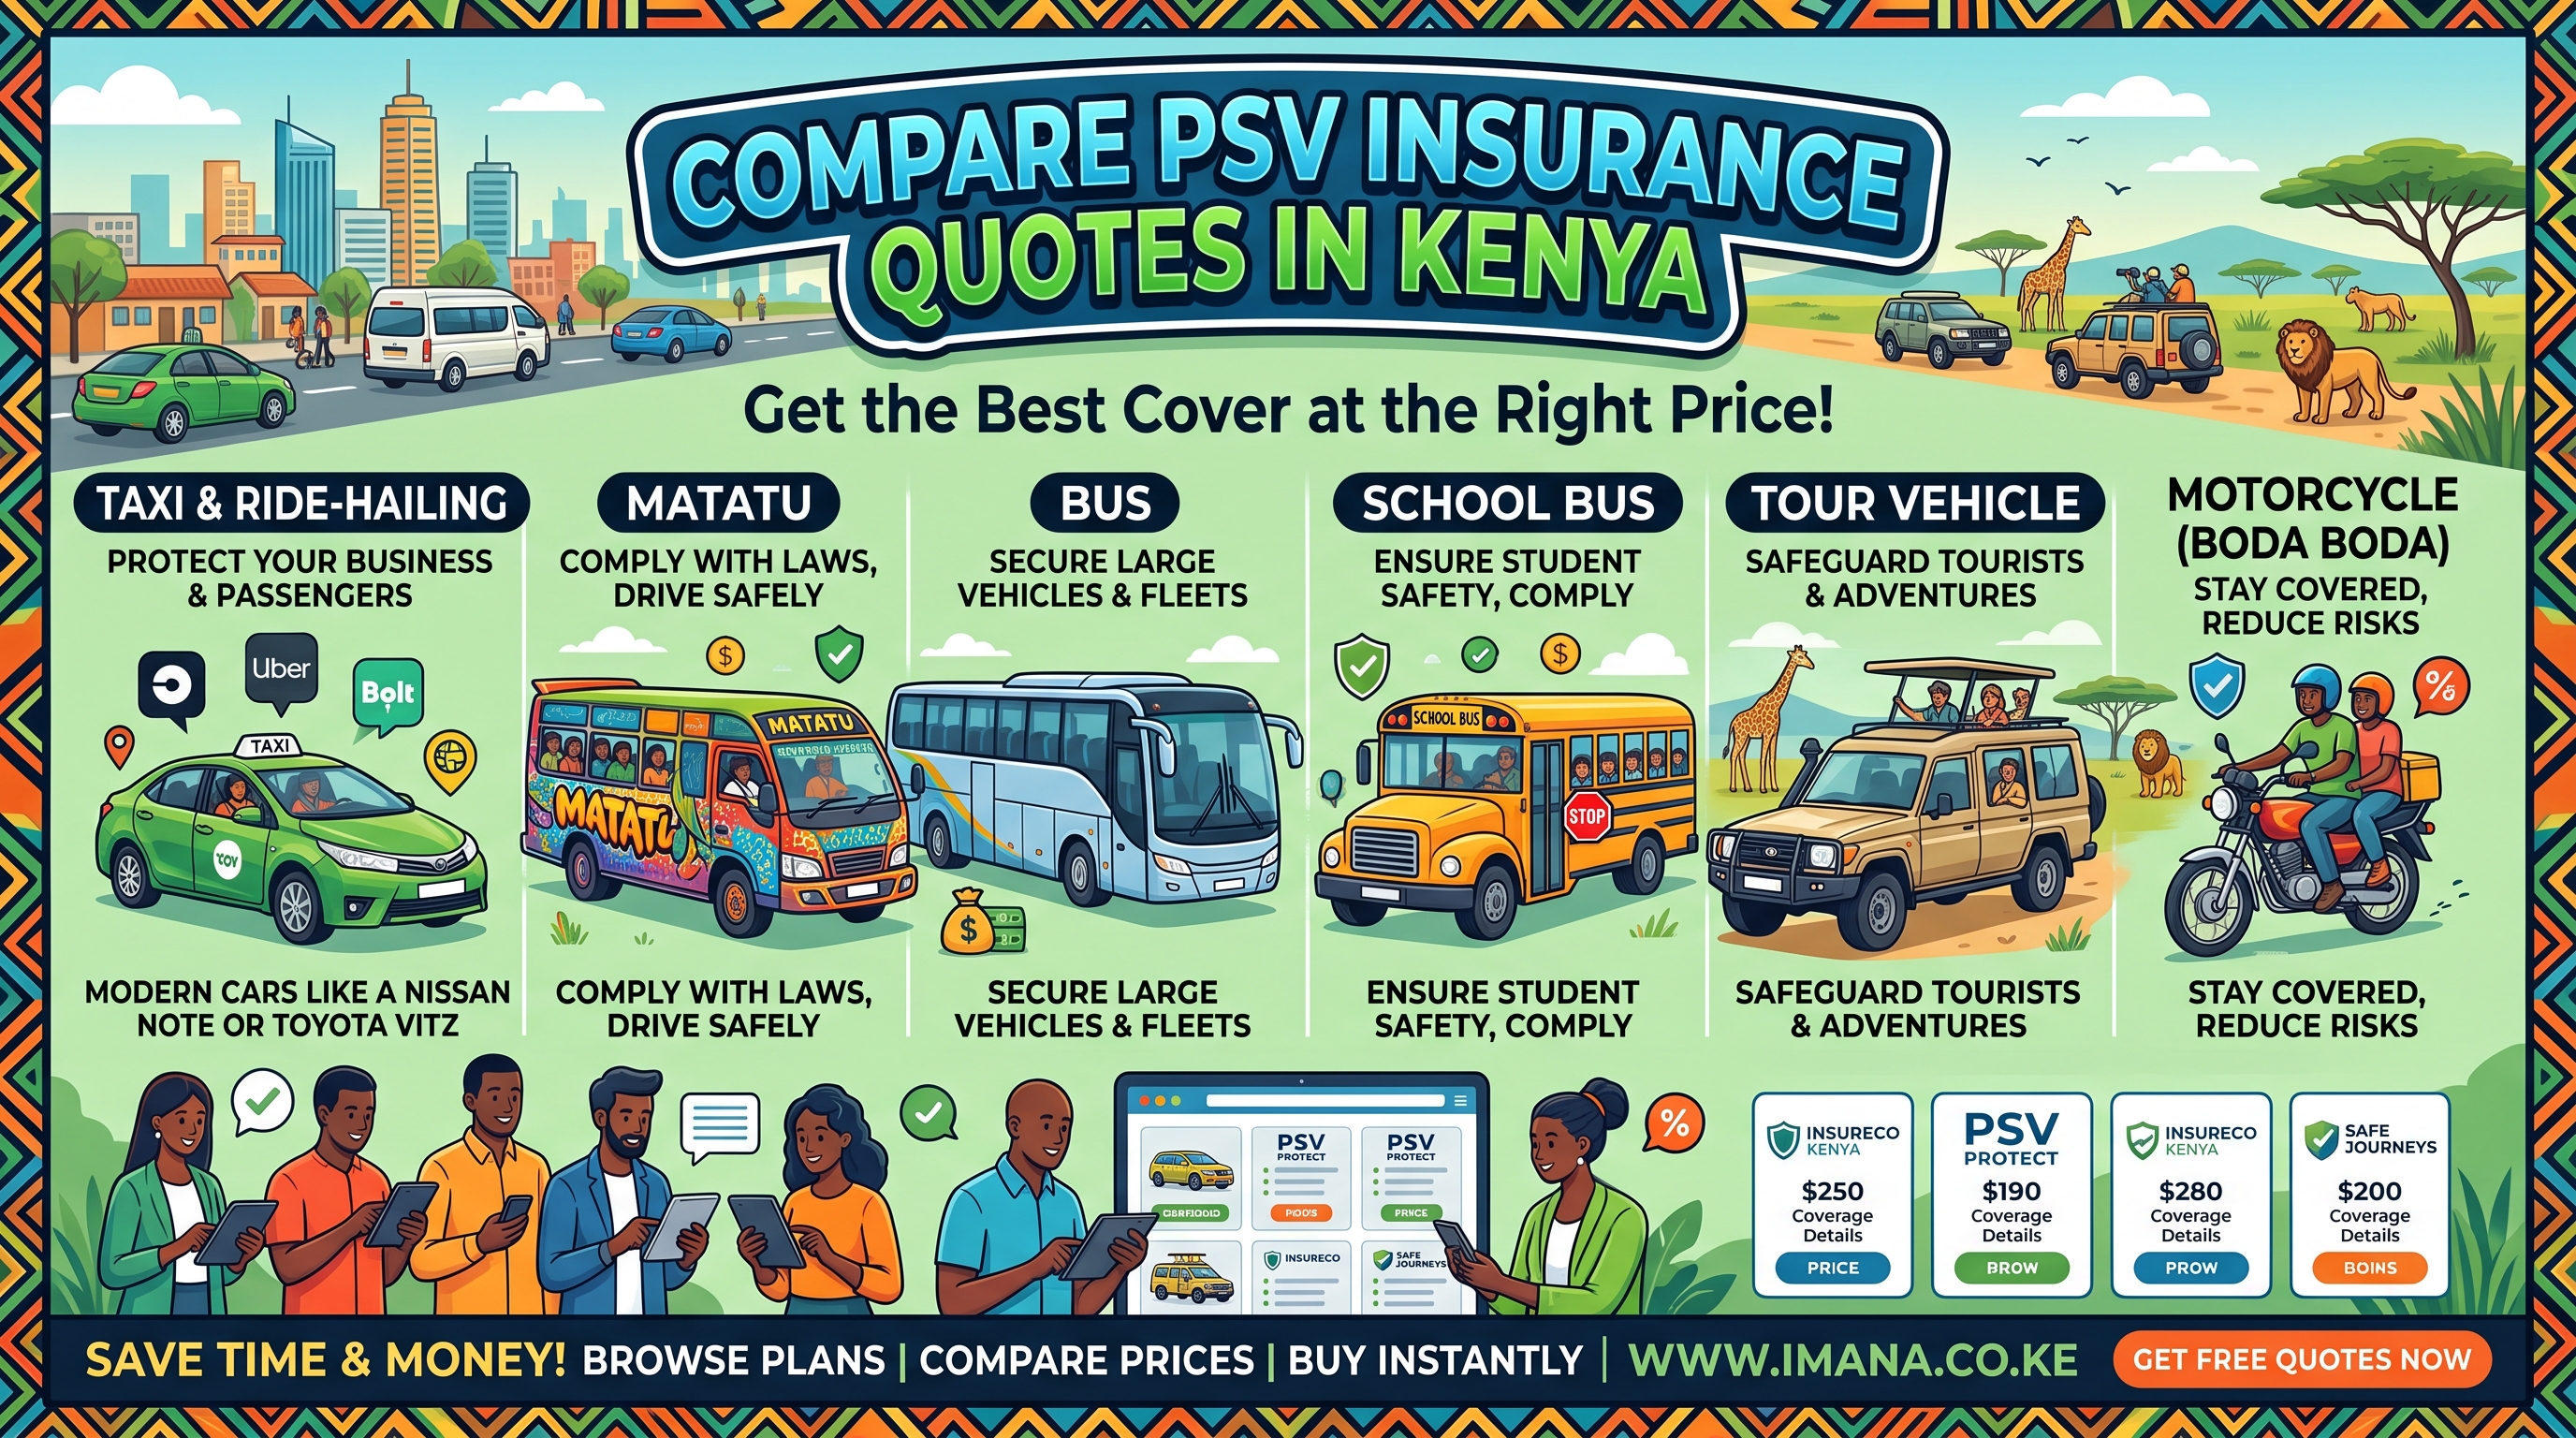
Compare PSV insurance quotes in Kenya for taxis, ride-hailing cars, matatus, buses, school buses and tour vehicles. Review prices, capacity and claims terms.
Where Can I Compare PSV Insurance Quotes in Kenya?
You can compare PSV insurance quotes in Kenya through Imana Insurance Agency Kenya Ltd, a Westlands-based insurance intermediary that works with licensed Kenyan insurers.
Imana helps taxi and ride-hailing drivers, matatu owners, bus companies, schools and tour operators compare available quotations based on the vehicle’s actual use, seating capacity, value and required level of cover.
To receive a meaningful comparison, share:
- Vehicle registration number, make, model and year
- Logbook details
- Exact use: taxi, ride-hailing, matatu, bus, school bus or tour vehicle
- Licensed seating capacity
- Current vehicle value for Comprehensive cover
- Operating area or route where required
- Claims history
- Preferred cover period
- Required extensions or benefits
Start with Imana’s PSV Insurance guide and quotation page.
Why PSV Insurance Must Match the Vehicle’s Actual Use
A PSV policy is not private car insurance with a different sticker. It is specialist motor cover for a vehicle carrying passengers for hire, reward or organised transport—and that creates a different risk from a privately used car.
PSVs often spend longer hours on the road, carry more people and operate under commercial pressure. A serious accident can involve several passengers, other road users, property damage and extensive vehicle repairs at the same time.
That is why a private motor certificate is not an appropriate substitute for PSV insurance when a vehicle is used for paid passenger transport. The policy must correctly describe what the vehicle does.
A cheap quotation under the wrong class is not a bargain. It is a potential claims dispute waiting for the worst possible day.
What Types of PSV Insurance Quotes Can You Compare?
“PSV” is not one uniform insurance product. The quotation changes according to the vehicle category, capacity and operating model.
PSV taxi insurance
PSV taxi insurance is intended for vehicles used to carry paying passengers. This may include conventional taxis and vehicles operating through ride-hailing platforms.
When comparing taxi quotations, disclose whether the vehicle is used for:
- Street or rank taxi work
- App-based ride-hailing through platforms such as Uber, Bolt, Little or Faras
- Airport transfers
- Corporate transport
- Hotel transfers
- Other paid passenger services
Insurers may consider the vehicle’s value, age, claims history, operating area and whether the cover is Third Party or Comprehensive.
Ride-hailing insurance for Uber, Bolt and similar platforms
A car used for ride-hailing should be declared according to its commercial passenger use. Do not insure it as a private family car simply because it is a saloon or SUV.
Compare quotations for the correct PSV taxi class and check:
- Whether app-based passenger transport is accepted
- Passenger-liability terms
- Driver requirements
- Theft and security conditions
- Vehicle-age limits
- Comprehensive inspection or valuation requirements
- Excesses applying to accidental damage or theft
The platform name does not determine the insurance contract. The insurer’s accepted class and policy wording do.
Matatu insurance
Matatu insurance is designed for vehicles licensed to carry fare-paying passengers on public routes. Capacity is central to the quotation because a 14-seater and a larger matatu do not present identical passenger exposure.
When comparing matatu insurance, review:
- Licensed seating capacity
- Passenger-liability basis
- Route or area of operation where requested
- Third-party property-damage terms
- Driver and conductor requirements
- Short-term versus annual availability
- Claims excesses and documentation
- Comprehensive vehicle value and valuation
Never reduce the declared seating capacity to obtain a lower price. The certificate, logbook and licensing information should tell the same story.
Bus insurance
Bus insurance applies to larger passenger vehicles and may vary according to capacity and use. A public-route bus, staff bus, institutional bus and long-distance coach may require different underwriting treatment.
Insurers may ask about:
- Number of passenger seats
- Operating route and distance
- Night operations
- Driver experience
- Vehicle age and maintenance
- Claims record
- Fleet size
- Passenger and third-party exposure
Fleet operators should compare more than the headline premium. Claims reporting, repair arrangements, excesses and the insurer’s appetite for the full fleet can materially affect value.
School bus insurance
School buses transport children, teachers and authorised staff. The policy should reflect institutional use and the vehicle’s licensed capacity.
Schools should compare:
- Passenger-liability protection
- Permitted drivers
- Territorial and use restrictions
- Vehicle inspection and valuation requirements
- Accidental-damage excesses
- Emergency-assistance benefits
- Claims procedures involving injured passengers
The school should also maintain driver vetting, servicing, inspections and road-safety controls. Insurance transfers specified financial risks; it does not replace safe transport management.
Motor PSV insurance also does not replace WIBA cover for employed drivers and attendants or Student Personal Accident cover for learners. Each policy responds to a different exposure and should be reviewed separately.
Tour vehicle insurance
Tour vans, safari vehicles and tourist-transfer vehicles may carry passengers across long distances and sometimes into neighbouring countries. Their quotations can be influenced by vehicle value, modifications, passenger capacity, terrain, operating territory and cross-border travel.
If a tour vehicle will leave Kenya, disclose the intended countries before travelling. Ordinary Kenyan motor insurance should not be assumed to provide the regional third-party protection required in every destination.
For cross-border journeys, review Imana’s COMESA Yellow Card guide.
Why Passenger Exposure Changes the Quote
Passenger exposure refers to the potential liability created by the people carried in the vehicle.
A five-seat taxi and a 51-seat bus do not carry the same possible severity of loss. In a major accident, several passengers may suffer injuries at once. Seating capacity, frequency of trips, route, vehicle type and operating hours therefore matter.
When comparing quotations, ask:
- How is passenger liability addressed?
- Is the quotation based on the correct licensed capacity?
- Are crew members treated separately?
- Are any passenger categories excluded?
- What reporting and evidence will be required after an injury?
- Does the policy contain capacity-related warranties or conditions?
Passenger exposure is not a small line on the quotation. It is one of the central reasons PSV insurance is priced and underwritten differently from private motor cover.
Why Seating Capacity Matters
Seating capacity helps insurers measure passenger exposure and place the vehicle in the correct rating class.
The declared capacity should agree with the logbook, vehicle inspection and operating licence. If a vehicle has been modified, the insurer should be told before cover is issued.
Overloading can also create legal, safety and claims complications. A valid policy is not permission to carry more passengers than the vehicle is licensed to transport.
When comparing quotes, make sure every insurer uses the same capacity. A lower quotation based on the wrong number of seats is not directly comparable with a correctly rated option.
Third Party vs Comprehensive PSV Insurance
Before comparing prices, confirm that the quotations provide the same level of cover.
Third Party PSV insurance
Third Party cover addresses specified legal liabilities for injury, death or property damage caused to other people, subject to the law and policy wording.
It does not normally pay for accidental damage, fire or theft affecting the insured PSV itself.
Third Party may be considered by owners of older or lower-value vehicles who can absorb the cost of repairing or replacing their own vehicle. However, it leaves the operator carrying a large part of the business risk.
Third Party, Fire and Theft
Where available, Third Party, Fire and Theft adds specified protection for fire and theft of the insured vehicle to the third-party cover.
It does not normally provide the same accidental-damage protection as Comprehensive insurance.
Comprehensive PSV insurance
Comprehensive PSV insurance generally combines third-party liability with protection against accidental damage, fire and theft affecting the insured vehicle, subject to exclusions, excesses and policy conditions.
It may be more suitable where the PSV is financed, valuable, essential to cash flow or difficult for the owner to replace after a total loss.
When comparing Comprehensive quotes, check:
- Insured vehicle value
- Valuation requirements
- Accidental-damage excess
- Theft excess and security conditions
- Windscreen limit
- Towing or road-rescue benefit
- Political Violence and Terrorism extension
- Excess Protector availability
- Authorised repair arrangements
- Loss-of-use or courtesy-vehicle terms, where offered
“Comprehensive” does not mean every incident is automatically covered. Read the schedule, endorsements and exclusions.
How Are PSV Insurance Quotations Calculated?
Insurers may consider:
- PSV category: Taxi, ride-hailing, matatu, bus, school bus and tour vehicle are not rated identically.
- Seating capacity: More passenger seats generally mean greater potential passenger exposure.
- Cover type: Third Party costs less than Comprehensive because it does not insure accidental damage to the PSV itself.
- Vehicle value: Comprehensive premiums are linked to the accepted insured value.
- Vehicle age and model: Repair costs, parts availability and insurer age limits may affect terms.
- Route and operating territory: Urban, long-distance, rural and cross-border operations can present different risks.
- Claims history: Previous losses may influence the premium, excess or acceptance.
- Driver and fleet controls: Licensing, experience, tracking, maintenance and safety procedures may be considered.
- Policy period: Annual and short-term options have different total cost structures.
- Extensions: PVT, Excess Protector, towing and other benefits may add to the premium.
The same PSV can therefore receive different quotations from different insurers. Compare each option on a consistent declaration.
Current PSV Insurance Quotation Examples in Kenya
PSV pricing changes by insurer, capacity, use, policy period, claims experience and prevailing taxes or levies. The following are indicative market examples for planning only, not guaranteed quotations:
- One-month PSV taxi Third Party: from approximately KSh 2,000 where short-term cover is available.
- Annual PSV taxi Third Party: from approximately KSh 7,574, subject to insurer terms.
- Matatu Third Party: some current market quotations begin from approximately KSh 7,900, depending on seating capacity and policy period.
- Bus and school bus: quoted according to capacity, use and insurer appetite rather than one universal price.
- Comprehensive PSV: calculated using the vehicle’s accepted value and the insurer’s rate, with excesses and extensions added as applicable.
Prices advertised online can become outdated quickly. Ask for a written quotation that identifies the exact vehicle category, seating capacity, cover period and total amount payable.
For broader benchmarks and updated motor pricing commentary, see the Imana Motor Insurance Price Guide.
Are Short-Term PSV Insurance Options Available?
Short-term PSV Third Party cover may be available from some insurers for certain vehicle classes. Availability is not automatic and underwriting rules can change.
Before buying short-term cover, confirm:
- Start and expiry dates
- Exact vehicle class
- Seating capacity
- Total premium
- Renewal procedure
- Whether consecutive short-term policies are permitted
- Whether annual cover offers better overall value
Short-term insurance can help with immediate cash flow, but repeatedly buying monthly cover may cost more over a full year than an annual policy.
It can be useful when an operator is starting a new contract or needs an interim period before arranging annual cover, but only where the selected insurer accepts that class and period.
What Claims Terms Should PSV Owners Compare?
The cheapest premium can become expensive if the claims conditions are poorly understood.
Review:
- Notification deadlines
- Required police documents
- Passenger and witness information
- Driver’s licence and PSV credentials
- Vehicle inspection and valuation requirements
- Approved repairer arrangements
- Accidental-damage and theft excesses
- Towing authorisation
- Theft-security warranties
- Exclusions involving unlicensed drivers, unauthorised use or overloading
- Documentation required for passenger-injury claims
Do not admit liability or privately settle a serious accident without guidance. Preserve evidence, assist injured people, report the incident to the police where required and notify the insurer or intermediary promptly.
After an accident:
- Protect passengers and call emergency services where necessary.
- Report the incident to the police and obtain the required police documents.
- Notify Imana or the insurer without avoidable delay.
- Take photographs and record passenger, witness and third-party details.
- Preserve medical records, receipts and other supporting evidence.
- For Comprehensive claims, do not begin unauthorised repairs before assessment where the policy requires approval.
For a structured reporting process, use Imana’s Claims Centre.
Documents Required for a PSV Insurance Quote
Requirements vary, but you may be asked for:
- Vehicle logbook
- National ID or passport
- KRA PIN
- Contact details and email address
- Vehicle registration, make, model and year
- Licensed seating capacity
- PSV licence or other operating documents where applicable
- Driver details where required
- Vehicle value for Comprehensive cover
- Valuation or inspection report
- Existing policy and claims history for renewals
- Route or territorial information for specified operations
Additional information may be required for fleets, school buses, tour operators or vehicles with modifications.
How to Compare PSV Quotes Properly
Use one accurate vehicle declaration for every insurer, then compare:
Correct vehicle class
Confirm that taxi, ride-hailing, matatu, bus, school bus or tour use is stated correctly.
Correct seating capacity
Every quotation should use the same licensed capacity.
Same cover period
Do not compare a monthly quotation with an annual quotation without calculating the full-year cost and checking availability conditions.
Same level of cover
Third Party and Comprehensive are fundamentally different products. Compare like with like.
Passenger-liability terms
Check how passengers are treated and whether the policy contains material limits, warranties or exclusions.
Total payable premium
Confirm whether quoted figures include applicable taxes, levies and selected extensions.
Claims conditions
Review excesses, documentation, repair arrangements and notification requirements before paying.
Insurer appetite and support
Not every insurer writes every PSV class at all times. An intermediary can identify available markets and help explain the differences.
Why Compare PSV Insurance Through Imana?
Imana Insurance Agency Kenya Ltd is a Westlands-based insurance intermediary helping individuals, families and businesses compare insurance quotations from licensed Kenyan insurers across Motor, Medical, WIBA, PSV, Travel, Motorcycle, Corporate and other insurance classes.
For PSV owners and operators, Imana can help:
- Identify the correct PSV classification
- Request comparable quotations from available insurers
- Explain Third Party and Comprehensive options
- Review capacity, passenger exposure and policy period
- Arrange documentation, valuation or inspection where required
- Support digital policy processing after all requirements are met
- Assist with claims communication and follow-up
Imana is based at the 4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi, while digital processes allow the agency to serve PSV operators across Kenya.
Explore the wider range of Motor Insurance options.
Frequently Asked Questions About PSV Insurance in Kenya
Where can I compare PSV insurance quotes in Kenya?
You can request and compare available PSV quotations through Imana Insurance Agency Kenya Ltd. Share the logbook, exact PSV use, licensed seating capacity, preferred cover period and vehicle value where Comprehensive cover is required.
Can an Uber or Bolt vehicle use private motor insurance?
A vehicle carrying passengers for payment should be declared according to its actual use. Ride-hailing commonly requires the appropriate PSV taxi classification, subject to insurer underwriting.
Does PSV Third Party insurance repair my vehicle?
No. Third Party cover does not normally pay for accidental damage to your own PSV. Comprehensive insurance is designed to provide broader vehicle protection, subject to terms.
Is short-term PSV insurance available?
Some insurers may offer short-term Third Party cover for selected PSV categories. Availability, premium and conditions should be confirmed through a current written quotation.
Why does seating capacity affect the premium?
Capacity changes the number of passengers potentially exposed in an accident and helps determine the correct rating class.
Is a school bus insured the same way as a matatu?
Not necessarily. Both carry passengers, but their use, operating environment and underwriting classification can differ. The quotation should state the correct institutional or PSV use.
Does Comprehensive PSV insurance include PVT and Excess Protector?
Not automatically. These may be included, optional, separately priced or unavailable depending on the insurer.
Does a Kenyan PSV policy cover travel to Uganda or Tanzania?
Do not assume it does. Disclose cross-border travel and arrange the required territorial extension or COMESA Yellow Card before departure.
Can I compare PSV quotations at renewal?
Yes. Renewal is the right time to review vehicle value, capacity, claims history, insurer options, excesses and changing business use.
Request and Compare PSV Insurance Quotes
The right PSV policy begins with the truth about the vehicle: what it carries, where it operates, how many passengers it is licensed for and what financial risk the owner can absorb.
Compare the same class, capacity, cover period, benefits, excesses and claims terms. Do not buy a certificate that merely looks affordable today but leaves the business exposed tomorrow.
Visit www.imana.co.ke or www.mykava.co.ke to begin.
Compare the premium. Compare the passenger protection. Keep your PSV business moving with better information.
Disclaimer: Quotation examples are indicative only and are not binding offers. Premiums, benefits, insurer appetite, taxes, levies and underwriting requirements can change. Obtain a current written quotation and review the applicable policy wording before purchasing cover.