
Blog Details
Diskava. Beta. Kava
09Sep
Rejected Insurance Claims in Kenya: How to Challenge Them
Learn how to challenge a rejected insurance claim in Kenya by reviewing the policy, gathering evidence, appealing internally and escalating to IRA.
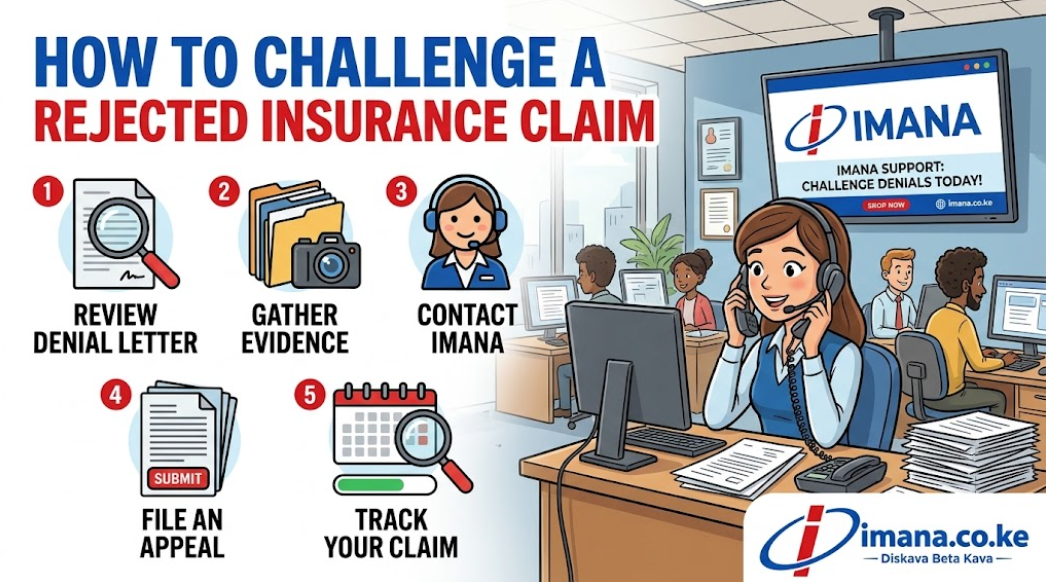
How to Challenge a Rejected Insurance Claim in Kenya
Receiving a claim-rejection letter can feel final. Sometimes it is justified by the policy. Sometimes it results from missing documents, incorrect information, an overlooked endorsement or a misunderstanding about what happened.
A rejected claim should never be ignored—but it should not be challenged emotionally or blindly either.
The strongest response begins with three things:
- A written explanation from the insurer
- The complete insurance policy
- Evidence addressing the precise reason given
This guide explains how individuals, families and businesses can review and challenge rejected insurance claims in Kenya, including escalation through the insurer, an insurance intermediary and the Insurance Regulatory Authority.
Quick answer: Ask the insurer to provide its decision and the policy clause supporting it in writing. Review the policy schedule, wording, endorsements, exclusions and premium records. Gather evidence answering the insurer’s stated reason, submit a structured internal appeal and escalate unresolved complaints to the Insurance Regulatory Authority where appropriate.
Imana Insurance Agency Kenya Ltd assists customers with claims documentation, communication and follow-up. However, an intermediary cannot guarantee that a rejected claim will be overturned.
For claims assistance, use the Imana Claims Request Page.
What is a rejected insurance claim?
A rejected insurance claim is a claim that an insurer has refused to pay, either wholly or partly.
The insurer may conclude that:
- The event was not covered
- An exclusion applies
- The policy was inactive
- Premium had not been paid as required
- A policy condition was breached
- Material information was not disclosed
- The documents did not establish the loss
- The amount claimed was not supported
- The claim was fraudulent or materially misleading
A rejection does not necessarily mean the insurer is accusing the claimant of fraud. It may simply mean the insurer believes the claim falls outside the insurance contract.
The claimant is entitled to ask for the decision and reasons in writing.
What is the difference between a delayed, declined and repudiated claim?
These terms are sometimes used interchangeably, but they can describe different stages.
Delayed claim
A delayed claim remains open but has not been settled within the expected period.
Delay may result from:
- Missing documents
- Continuing investigations
- Outstanding medical reports
- Police investigations
- Assessment or valuation disputes
- Repair delays
- Questions about ownership
- Unconfirmed premium payments
- Dependants who have not been identified
- Information required from a third party
A delayed claim has not necessarily been rejected.
Declined claim
A declined claim is one the insurer has decided not to pay because it believes the policy does not respond.
The insurer should explain the reason and identify the applicable policy provision.
Repudiated claim
Repudiation is a more formal denial of liability under the policy.
An insurer may repudiate a claim where it believes there was:
- Material non-disclosure
- Misrepresentation
- Fraud
- Breach of a fundamental policy condition
- Loss outside the insured risk
- Use of the insured property for an unauthorised purpose
Whether the term used is “declined,” “rejected” or “repudiated,” ask whether the decision is final and obtain the complete reasons in writing.
First step: request a written explanation
Do not rely only on a telephone call, WhatsApp message or statement from a service representative.
Write to the insurer and request:
- The final claim decision
- Every reason for the rejection
- The specific policy clause relied upon
- The facts used to reach the decision
- A copy of any assessment report that may be disclosed
- Details of missing or disputed documents
- The insurer’s internal appeal process
- The deadline for submitting an appeal
The Insurance Act provides that where a claim assessment has been conducted, a copy of the assessment report should be made available as provided under the Act. The Act also allows an insurance customer to lodge a written complaint with the Commissioner against a regulated entity.
A vague response such as “the claim does not meet our requirements” is not enough to prepare a meaningful appeal. Ask the insurer to connect its decision to the policy wording and evidence.
Review the complete insurance policy
An insurance policy is more than the certificate or one-page schedule.
Request and review:
- Proposal or application form
- Policy schedule
- Full policy wording
- Endorsements
- Extensions
- Exclusions
- Excesses and deductibles
- Premium-payment terms
- Renewal correspondence
- Valuation documents
- Benefit schedule
- Claim-notification conditions
- Any amendments issued during the policy period
The schedule identifies the insured person, property, vehicle, business or benefit. The policy wording provides the standard terms. Endorsements can add, remove or change those terms.
A claimant should not challenge a rejection without first understanding the clause the insurer says was breached.
Check whether an exclusion genuinely applies
An exclusion describes an event, circumstance, activity or type of loss that the policy does not cover.
Common exclusions can include:
- Wear and tear
- Mechanical or electrical breakdown
- Illegal activity
- Intentional loss
- Undeclared commercial use
- Driving without a valid licence
- Treatment received during a waiting period
- War or terrorism without the relevant extension
- Unattended theft under specified circumstances
- Gradual deterioration
- Contractual liability not covered by the policy
- Property outside the insured location
- Loss outside the territorial limits
Read the exact wording carefully.
Ask:
- Was the exclusion part of the policy when it was issued?
- Does it apply to the particular cause of loss?
- Is there an endorsement that restores the cover?
- Did the insurer rely on the correct facts?
- Was the exclusion clearly communicated?
- Is the exclusion being interpreted too broadly?
- Does only part of the claim fall within the exclusion?
An excluded item does not automatically invalidate every other part of the claim.
Check the policy’s insured event
A claim must involve an event insured by the policy.
For example:
- Comprehensive motor insurance may cover accidental damage, but third-party-only insurance generally does not repair the policyholder’s own vehicle.
- Fire insurance may cover fire damage but not every type of electrical or machinery breakdown.
- Medical insurance may cover hospital treatment but exclude treatment received during a waiting period.
- Travel insurance may cover unforeseen cancellation but not a decision to abandon travel voluntarily.
- WIBA responds to qualifying occupational injury or disease, not every illness affecting an employee.
A strong appeal explains why the facts meet the policy’s definition of an insured event.
Look for missing or overlooked evidence
Some claims are rejected because the insurer believes the loss has not been proved.
Relevant evidence may include:
- Police abstract
- Occurrence Book number
- Photographs and videos
- CCTV footage
- Witness statements
- Medical reports
- Discharge summary
- Receipts and invoices
- Repair estimates
- Valuation reports
- Proof of ownership
- Vehicle logbook
- Purchase receipts
- Employment and payroll records
- Fire brigade report
- Investigator’s report
- Stock records
- Import documents
- Travel itinerary
- Written correspondence
- Bank or M-Pesa payment confirmation
Match the evidence to the insurer’s reason.
If the insurer says ownership was not established, provide ownership records. If it disputes the cause of loss, provide expert, police or witness evidence. If it says notification was late, explain when the loss was discovered and why notification could not reasonably have been made earlier.
Sending a large pile of unrelated documents can hide the strongest evidence. Organise the appeal clearly.
What if documents are missing?
Do not fabricate or alter a missing document.
Instead:
- Explain why it is unavailable.
- Ask whether an acceptable alternative exists.
- Obtain a certified or official replacement where possible.
- Provide independent evidence supporting the same fact.
- Document the steps taken to recover the missing record.
For example, a lost receipt may sometimes be supported by a supplier’s duplicate invoice, bank transaction and written confirmation of payment. Whether that evidence is accepted depends on the claim and policy.
How should non-disclosure disputes be challenged?
Non-disclosure means relevant information was not given to the insurer when the policy was arranged, renewed or amended.
Examples may include:
- Previous claims
- A pre-existing medical condition
- Commercial use of a private vehicle
- Hazardous business activities
- Existing damage
- Multiple regular drivers
- Building occupancy
- Storage of hazardous materials
- Changes affecting the insured risk
If the insurer relies on non-disclosure, ask:
- What information was allegedly withheld?
- Where and when was the question asked?
- How was the question worded?
- What answer was provided?
- Why was the information material to the risk?
- Would disclosure have resulted in different terms or premium?
- Did the insurer or its representative already possess the information?
- Is the alleged non-disclosure connected to the claim?
- Was the application completed by another person?
- Was the policyholder given an opportunity to check the answers?
Provide copies of application forms, emails, WhatsApp messages and documents supplied when the cover was arranged.
Never claim that information was disclosed without supporting evidence. Equally, do not accept a non-disclosure allegation without asking the insurer to identify the question, answer and information in dispute.
How should a premium-payment dispute be handled?
An insurer may reject a claim by stating that premium had not been paid or that the cover was not active.
Collect:
- M-Pesa confirmation
- Bank deposit slip
- Card-payment receipt
- Official insurer receipt
- Premium statement
- Debit note
- Cover confirmation
- Insurance certificate
- Renewal correspondence
- Instalment agreement
- Communications with the intermediary
Check:
- The payment date and time
- Amount paid
- Recipient account
- Policy number
- Cover commencement date
- Outstanding balance
- Whether an instalment arrangement existed
- Whether the insurer acknowledged the payment
- Whether the policy was cancelled
- Whether a cancellation notice was issued
Payment to an unauthorised person or personal account can create a serious dispute. Customers should use officially communicated insurer or intermediary payment channels and retain confirmation.
A certificate or quotation alone may not prove that every premium condition was satisfied. Conversely, an insurer should properly account for payments received through its authorised channels.
Build a clear insurance-claim appeal
A useful appeal should contain:
The claim details
Include:
- Policyholder’s name
- Policy number
- Claim number
- Date of loss
- Insured property or benefit
- Date of the rejection letter
The insurer’s stated reason
Quote or summarise the rejection reason accurately. Do not exaggerate or replace it with what you think the insurer meant.
The disputed policy interpretation
Identify the clause and explain why you believe it does not apply—or why another clause or endorsement supports the claim.
The supporting evidence
List each document and explain what it proves.
The outcome requested
Ask for a specific result, such as:
- Reopening the claim
- Reviewing new evidence
- Reconsidering the interpretation
- Conducting a fresh assessment
- Paying the undisputed portion
- Providing a detailed settlement calculation
- Issuing a final written decision
Keep the language firm, factual and professional.
Use the insurer’s internal complaints process
Before escalating externally, submit the matter through the insurer’s formal complaints procedure.
Address the complaint to the insurer’s:
- Claims department
- Complaints officer
- Customer-experience team
- Legal or compliance department
- Senior claims manager
Request:
- A complaint reference number
- Confirmation of receipt
- The expected response period
- The name or office handling the review
- A final written response
Keep a dated record of every email, letter, telephone call and document submitted.
If the complaint concerns a medical administrator, investigator, assessor, garage or other service provider, copy the insurer because the policy relationship is ultimately with the insurer.
What is the role of an insurance intermediary?
An insurance intermediary can help a customer:
- Notify the insurer
- Obtain claim forms
- Understand document requirements
- Follow up on outstanding information
- Clarify policy wording
- Organise supporting evidence
- Request a written claim decision
- Submit an internal complaint
- Escalate an unresolved service issue
- Maintain communication between the parties
The intermediary may also hold useful records, including:
- Quotation comparisons
- Proposal documents
- Policy instructions
- Payment confirmations
- Cover-placement correspondence
- Renewal records
- Disclosures provided during placement
An intermediary should present the customer’s case honestly. It should not hide material information, alter evidence or pressure an insurer to pay a claim outside the contract.
The IRA confirms that individuals, brokers and agents may ask the Authority to intervene in disputes affecting policyholder rights and interests.
What an intermediary cannot promise
An insurance intermediary cannot honestly promise that:
- Every claim will be paid
- A rejected claim will be overturned
- An insurer will ignore an exclusion
- Missing evidence will not matter
- Fraud or material misrepresentation will be excused
- A particular settlement amount is guaranteed
- A claim will be completed by a specific date
- The intermediary can overrule the insurer or regulator
The insurer decides whether the policy responds. Courts, tribunals, regulators or other authorised bodies may determine disputes within their respective powers.
The intermediary’s value lies in documentation, explanation, advocacy, follow-up and helping the customer navigate the correct process.
Escalating a rejected claim to the Insurance Regulatory Authority
If the insurer’s internal complaints process does not resolve the dispute, the claimant may approach the Insurance Regulatory Authority.
The IRA handles complaints involving issues such as:
- Disagreement about liability
- Disagreement about the settlement offered
- Delay in settling a payable claim
- Claim denial
- Conduct by a regulated insurer or intermediary
The Authority’s online complaint form specifically includes claim delay, claim denial and agent-handling complaints.
Before lodging the complaint, prepare:
- Completed IRA complaint form
- Policy schedule and wording
- Claim form
- Claim correspondence
- Rejection letter
- Internal appeal
- Insurer’s final response
- Supporting evidence
- Identification documents
- A clear summary of the remedy sought
The IRA advises complainants to provide all relevant information and correspondence and to retain copies. Complaints initiated by telephone or email should be confirmed in writing using the appropriate complaint form.
You can use the IRA complaint portal or check the Authority’s current complaint contacts.
Regulatory escalation does not guarantee payment. The evidence and policy terms remain central.
When might legal advice be necessary?
Consider obtaining independent legal advice where:
- The claim involves a substantial amount
- The policy wording is technically complex
- Fraud or dishonesty has been alleged
- The insurer has cancelled or avoided the policy
- A third party has filed a lawsuit
- A statutory notice must be issued
- Liability is disputed
- An arbitration clause applies
- The limitation period may be approaching
- The insurer’s final position remains unacceptable
- The claim involves serious injury or death
- Several insurers or policies are involved
- Business interruption or consequential loss is disputed
An intermediary can support the insurance process but should not replace an advocate where formal legal representation or legal interpretation is required.
Are there time limits for challenging an insurance claim?
Yes. Several different time limits may apply.
These can arise from:
- The policy’s notification condition
- The insurer’s internal appeal procedure
- An arbitration clause
- Regulatory complaint procedures
- Third-party liability legislation
- The Limitation of Actions Act
- A statute governing the particular claim
- A court or tribunal process
Under Kenya’s Limitation of Actions Act, an action founded on contract generally may not be brought more than six years after the cause of action accrued. Tort claims generally have a different limitation period.
This general rule should not be treated as permission to wait. A policy may require notification, supporting documents, arbitration or another step much earlier. Determining when a cause of action accrued can also require legal analysis.
Act immediately after receiving a rejection. If a deadline is unclear, seek legal advice.
Why record-keeping matters
Insurance disputes are often decided by documents created before anyone realised there would be a dispute.
Keep:
- The original quotation
- Proposal form
- Policy schedule
- Policy wording
- Endorsements
- Payment evidence
- Renewal notices
- Disclosure correspondence
- Photographs
- Medical or expert reports
- Police documents
- Claim forms
- Assessment reports
- Rejection letters
- Appeal correspondence
- Notes of telephone calls
- Complaint reference numbers
- Proof of document delivery
For telephone conversations, record the date, time, number called, person spoken to and key points discussed. Follow important calls with an email confirming what was said.
Do not edit original photographs, receipts, reports or messages. Preserve the original versions.
Common mistakes when challenging a rejected claim
Avoid:
- Responding only through angry social-media posts
- Making threats before understanding the rejection
- Submitting false or altered evidence
- Ignoring the policy wording
- Missing appeal deadlines
- Sending documents without a clear explanation
- Relying entirely on verbal communication
- Concealing facts that may later emerge
- Authorising repairs or disposal of property prematurely
- Assuming the intermediary controls the insurer’s decision
- Delaying until evidence or witnesses disappear
Public pressure cannot replace evidence, contractual analysis or the proper complaint process.
Rejected-claim review checklist
Before submitting an appeal, confirm that you have:
- Obtained the rejection in writing
- Identified every reason given
- Requested the relevant policy clause
- Collected the complete policy documents
- Checked endorsements and extensions
- Reviewed exclusions
- Verified premium payments
- Compared the decision with the evidence
- Collected missing documents
- Prepared a chronological summary
- Stated the outcome requested
- Checked applicable deadlines
- Kept copies of everything
- Considered professional or legal advice
Frequently asked questions
Can every rejected insurance claim be challenged?
A customer may ask for a decision to be reviewed, but not every rejection will be overturned. Some claims genuinely fall outside the policy.
Should the insurer provide a written reason?
Request a written decision identifying the reasons and policy provisions relied upon. A written response allows the claimant to prepare a focused appeal.
Can missing documents be submitted after rejection?
Possibly. Ask the insurer whether the claim can be reopened or reviewed after the missing documents are provided.
Does late notification automatically invalidate a claim?
Not necessarily in every situation, but it can seriously affect the claim. The wording, length of delay, explanation and effect on the insurer’s investigation may all matter.
What if the insurer says the premium was not paid?
Provide official receipts, M-Pesa or bank records, policy statements and correspondence confirming the cover or payment arrangement.
Can an intermediary force an insurer to pay?
No. An intermediary can support and advocate for the customer but cannot override the policy or compel an insurer to admit liability.
Can IRA order every rejected claim to be paid?
IRA can receive and handle complaints against regulated insurance entities. Escalation does not guarantee that the claim will be accepted.
Should a claimant accept a partial settlement?
Ask for a written calculation and understand whether accepting the payment affects the remaining dispute. Obtain legal advice where the consequences are unclear.
Can a claim proceed to court?
Some disputes may require litigation, arbitration or another formal process. Check the policy and obtain legal advice before choosing the forum.
How Imana assists customers with disputed claims
Imana Insurance Agency Kenya Ltd can help customers by:
- Obtaining claim forms and requirements
- Reviewing whether documents are complete
- Following up with the insurer
- Requesting written reasons for a decision
- Helping organise an internal appeal
- Clarifying policy provisions
- Tracking complaint references
- Supporting communication during escalation
- Reviewing cover weaknesses before renewal
- Comparing alternative insurance quotations
Imana cannot guarantee claim payment or overturn the insurer’s decision. Its role is to help the customer follow a clear, documented and credible process.
Read the Insurance Claims Knowledge Centre and Imana’s guide on Why Insurance Claims Are Delayed or Declined in Kenya.
Protect the next claim before the loss happens
The best time to understand a policy is before signing it.
When comparing insurance quotations, review:
- What is covered
- Major exclusions
- Excesses and deductibles
- Disclosure requirements
- Premium-payment terms
- Claim-notification deadlines
- Document requirements
- Territorial limits
- Valuation provisions
- Complaint and dispute procedures
- Insurer claims-support capacity
A low premium can become very expensive if the policy does not match the actual risk.
Use ImanaInsurance.com to request and compare insurance quotations. Visit Imana.co.ke for Kenyan insurance authority guides and product information. Explore MyKava.co.ke for travel and insurance comparison options.
Get claims and insurance quotation assistance
Contact:
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands, Nairobi
Call/WhatsApp: +254 796 209 402
Websites:
- www.imanainsurance.com — quotation comparison and customer enquiries
- www.imana.co.ke — insurance authority guides and product information
- www.mykava.co.ke — travel and insurance comparison
Imana Insurance Agency Kenya Ltd is a Westlands-based insurance intermediary helping individuals, families and businesses compare insurance quotations from licensed Kenyan insurers across Motor, Medical, WIBA, PSV, Travel, Motorcycle, Cyber, SME/Corporate and other insurance classes.
Author: Raymond Momanyi
Founder & CEO, Imana Insurance Agency Kenya Ltd
Disclaimer: This article provides general information and does not constitute legal advice or guarantee that an insurer will reverse a claim decision. Policy terms, facts, statutory deadlines and dispute procedures differ. Obtain independent legal advice where necessary.