
Blog Details
Diskava. Beta. Kava
02Aug
Bid Bonds and Performance Bonds in Kenya Explained
Understand how Bid Bonds and Performance Bonds work in Kenya, who needs them, their differences, application requirements, costs, validity periods and common tender mistakes.
What Is the Difference Between a Bid Bond and a Performance Bond?
Businesses bidding for tenders in Kenya may be asked to provide financial security at different stages of the procurement process.
The two securities most frequently requested are:
- Bid Bond, also called a Tender Security
- Performance Bond, also called a Performance Security
Although both are guarantees, they serve different purposes.
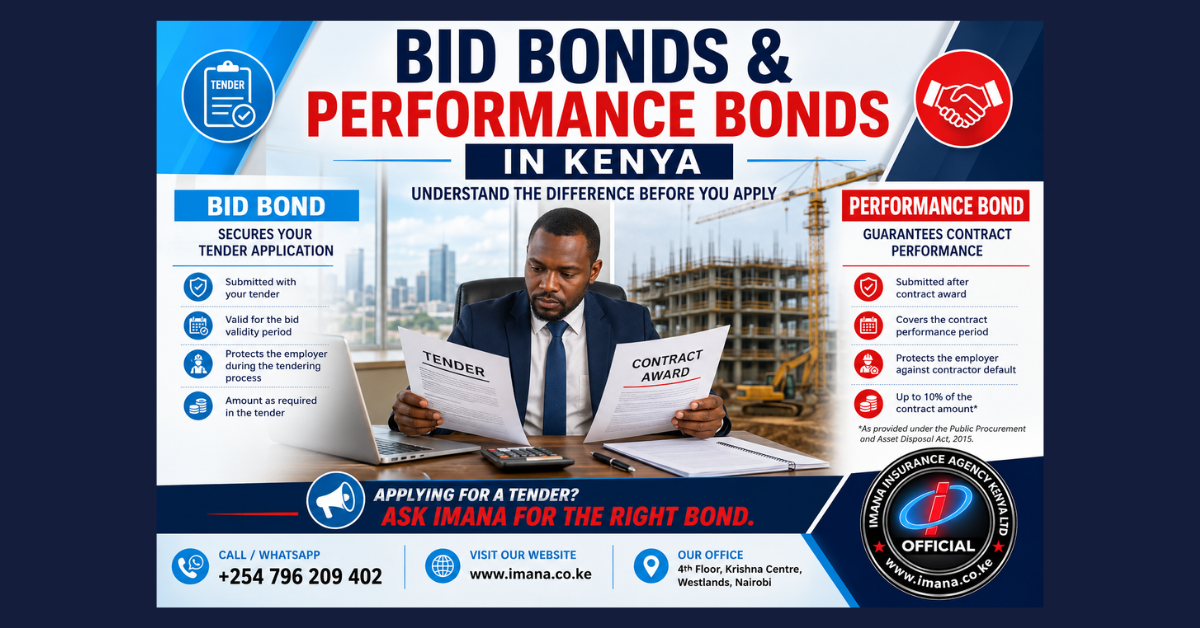
A Bid Bond is normally submitted together with the tender. It assures the procuring entity that the bidder will honour its tender obligations if selected.
A Performance Bond is normally submitted by the successful bidder before signing or beginning the contract. It guarantees that the contractor will perform the contract according to the agreed terms.
The Bid Bond protects the tendering process. The Performance Bond protects the contract after the tender has been awarded.
Businesses should carefully read the tender document because the required:
- Bond amount
- Format
- Issuer
- Validity period
- Beneficiary
- Submission method
- Claim wording
must match the tender instructions.
A valid bond issued using the wrong format or expiry date can still cause a bid to be rejected.
What Is a Bid Bond?
A Bid Bond is a guarantee submitted by a bidder as part of a tender application.
It gives the procuring entity financial protection against specified actions by the bidder during the tender process.
Under Kenya’s public procurement framework, a tender security may be provided in forms including:
- Cash
- Bank guarantee
- Guarantee from an insurance company registered and licensed by the Insurance Regulatory Authority and listed by the Public Procurement Regulatory Authority
- Guarantee from a financial institution approved and licensed by the Central Bank of Kenya (Kenya Law)
The tender document determines the acceptable forms for that particular procurement.
A bidder should not assume that every procuring entity accepts insurance bonds merely because they are legally recognised. The specific tender instructions must be followed.
Other names used for a Bid Bond
The following terms may refer to a similar requirement:
- Tender Security
- Tender Bond
- Bid Security
- Bid Guarantee
- Tender Guarantee
The precise wording in the tender document should be used when requesting the guarantee.
Why Is a Bid Bond Required?
A procuring entity may spend considerable time and resources:
- Advertising the tender
- Receiving bids
- Evaluating submissions
- Conducting due diligence
- Issuing the award
- Preparing the contract
The Bid Bond helps discourage bidders from submitting offers they are unwilling or unable to honour.
It assures the procuring entity that the bidder is serious about participating and accepting the award under the tender conditions.
The Public Procurement Regulatory Authority’s standard tender documents describe tender security as protection against bidder conduct that could justify forfeiture of the security. (Public Procurement Regulatory Authority)
When Can a Bid Bond Be Forfeited?
The exact triggers depend on the tender document and applicable procurement rules.
A Bid Bond may potentially be called where the bidder:
- Withdraws or materially modifies the bid during the validity period
- Refuses to accept an award made according to the tender
- Fails to sign the contract after being selected
- Fails to provide the required Performance Bond
- Fails to comply with another obligation stated in the bond wording
- Engages in conduct that triggers forfeiture under the tender conditions
The bidder should read the bond wording carefully because the insurer’s obligation follows the guarantee—not an informal understanding between the bidder and procuring entity.
A business should never submit a tender merely to test the market where it is not prepared to accept and perform the contract.
When Is a Bid Bond Released?
Tender security may normally be released when the bidder’s obligation ends.
This may happen after:
- The tender process is terminated
- The bid validity period expires without an award
- The successful bidder signs the contract and provides the required Performance Security
- Unsuccessful bidders are formally released
- Another release event stated in the tender documents occurs
Kenya’s Public Procurement and Asset Disposal Act allows immediate release of tender security in specified circumstances, including termination of the procurement proceedings. (Kenya Law)
The bidder should retain written evidence confirming that the procuring entity no longer requires the guarantee.
What Is a Performance Bond?
A Performance Bond is a guarantee provided by the successful bidder to secure proper performance of the awarded contract.
It gives the employer or procuring entity financial protection where the contractor fails to perform according to the contract.
The bond may apply to contracts involving:
- Construction works
- Supply of goods
- Installation projects
- Maintenance contracts
- Cleaning services
- Security services
- Technology implementation
- Engineering works
- Equipment supply
- Other contractual obligations
Under Kenya’s Public Procurement and Asset Disposal Act, a successful tenderer may be required to provide Performance Security of not more than 10% of the contract amount before signing the contract, subject to the Act and regulations. (Kenya Law)
The actual percentage is stated in the tender and contract documents.
Do not automatically request a 10% bond. Use the exact percentage and amount required by the procuring entity.
Why Is a Performance Bond Required?
Winning a tender does not guarantee that the contract will be completed successfully.
A contractor may:
- Abandon the project
- Fail to deliver goods
- Miss important deadlines
- Supply products that do not meet specifications
- Perform defective work
- Become financially unable to continue
- Fail to correct contractual defaults
The Performance Bond provides the procuring entity with financial recourse if a covered contractual default occurs.
It does not physically complete the project. Instead, the bond may provide payment up to the guaranteed amount when a valid demand is made under its terms.
When Can a Performance Bond Be Called?
The beneficiary may make a demand where the contractor fails to meet obligations covered by the guarantee.
Possible triggers include:
- Abandonment of the contract
- Failure to deliver agreed goods
- Failure to complete works
- Material breach of contract
- Failure to correct defective work
- Failure to meet agreed specifications
- Termination caused by contractor default
- Another event stated in the bond wording
Whether payment is due depends on the form of guarantee.
Some Performance Bonds are written as on-demand guarantees, meaning the issuer may be required to pay upon receipt of a compliant written demand without first obtaining a court judgment against the contractor.
Others may contain conditions requiring evidence of default.
The applicant should understand the wording before signing the insurer’s indemnity.
Bid Bond vs Performance Bond
Purpose
Bid Bond: Protects the procuring entity during the tendering stage.
Performance Bond: Protects the procuring entity after the contract has been awarded.
Applicant
Bid Bond: Any bidder required to submit tender security.
Performance Bond: The successful bidder or appointed contractor.
Time of submission
Bid Bond: Submitted with the tender.
Performance Bond: Submitted after award but before contract signing or commencement, according to the tender conditions.
Amount
Bid Bond: Usually a fixed amount or percentage stated in the tender document.
Performance Bond: Commonly a percentage of the contract value, subject to the tender and applicable procurement rules.
Validity period
Bid Bond: Normally covers the bid-validity period plus any additional period required by the tender.
Performance Bond: Usually covers the contract-performance period and may extend beyond completion where required.
Main risk protected
Bid Bond: Bidder withdrawing or failing to honour tender commitments.
Performance Bond: Contractor failing to perform the awarded contract.
Are Bid Bonds and Performance Bonds Insurance Policies?
They are issued within the insurance market, but they do not operate like ordinary property or motor insurance.
In conventional insurance:
- The policyholder transfers an insured risk to the insurer.
- The insurer pays an eligible loss according to the policy.
- The insured does not ordinarily repay a valid claim.
In a guarantee bond:
- The contractor is expected to perform the obligation.
- The insurer guarantees the contractor’s performance to the beneficiary.
- If the insurer pays a valid demand, it may seek reimbursement from the contractor under an indemnity agreement.
This means the contractor may remain financially responsible after the insurer pays the beneficiary.
A bond is not protection against the consequences of failing to perform. It is a credit guarantee supporting the contractor’s obligation.
Parties Involved in an Insurance Bond
1. The Principal
The principal is the bidder or contractor whose obligation is being guaranteed.
2. The Beneficiary
The beneficiary is the procuring entity, employer or client receiving the guarantee.
It may be:
- Government ministry
- County government
- State corporation
- Private company
- NGO
- School
- Hospital
- Property developer
- Other contracting organisation
3. The Guarantor
The guarantor is the insurer, bank or approved financial institution issuing the bond.
4. The Insurance Intermediary
A licensed insurance agent or broker may help the applicant:
- Review the tender requirement
- Gather documents
- Obtain quotations
- Coordinate underwriting
- Arrange execution
- Deliver the bond
- Process extensions or cancellations
Who Needs Bid Bonds in Kenya?
Bid Bonds may be required from businesses participating in tenders involving:
- Government procurement
- County projects
- Construction works
- Goods supply
- Cleaning services
- Security services
- ICT systems
- Medical supplies
- Equipment installation
- Road works
- Water projects
- Consultancy or professional services where applicable
- Private-sector procurement
The tender document should clearly state whether security is required.
Some tenders may provide exemptions or alternative declarations for specified categories of bidders.
Never assume that your business is exempt merely because it is:
- Small
- Newly registered
- Youth-owned
- Woman-owned
- Owned by a person with a disability
- Registered under AGPO
Confirm the tender’s exact preference, reservation and security conditions.
Who Needs Performance Bonds?
Performance Bonds may be required from contractors and suppliers who have been awarded contracts.
They are common among:
- Building contractors
- Road contractors
- Electrical contractors
- Mechanical contractors
- Suppliers
- Equipment installers
- Technology companies
- Cleaning companies
- Security firms
- Logistics providers
- Project-management firms
- Maintenance companies
The successful bidder should begin arranging the bond immediately after receiving the notification of award.
Waiting until the final contract-signing day can cause:
- Missed deadlines
- Loss of the award
- Forfeiture of the Bid Bond
- Project delays
- Additional costs
Who Can Issue Bid Bonds in Kenya?
For public procurement, an insurance Bid Bond should come from a company that is:
- Licensed by the Insurance Regulatory Authority
- Accepted or listed by the Public Procurement Regulatory Authority
- Permitted by the specific tender document
PPRA publishes a list of insurance companies authorised to issue Bid Securities. Applicants should check the current list rather than relying on an old tender, advertisement or previous transaction. (Public Procurement Regulatory Authority)
The insurer must also be willing to underwrite the applicant.
Being on an approved list does not mean every insurer will accept every bond application.
Documents Required for a Bid Bond
Requirements vary by insurer, but applicants may be asked for:
- Completed bond proposal form
- Tender document
- Tender number
- Bid Bond format
- Required bond amount
- Bid closing date
- Bond validity period
- Company registration certificate
- Company KRA PIN
- Directors’ identification and KRA PINs
- CR12 or current company-search information
- Business permits
- Company profile
- Financial statements or bank statements
- Previous contract experience
- Signed indemnity
- Collateral or counter-guarantee where required
The bidder should provide the complete page containing the bond instructions—not merely a WhatsApp message showing the amount.
Documents Required for a Performance Bond
Performance Bond underwriting is usually more detailed because the insurer is guaranteeing contract performance.
The applicant may need:
- Notification of award
- Signed contract or draft contract
- Tender document
- Performance Bond format
- Contract amount
- Required bond percentage
- Project commencement and completion dates
- Bill of quantities
- Work programme
- Company registration documents
- Directors’ details
- Audited financial statements
- Bank statements
- Previous completed contracts
- Current projects
- Contractor registration documents
- Technical-team details
- Equipment schedule
- Cash-flow projection
- Indemnity agreement
- Collateral where required
The insurer may also assess whether the applicant has:
- Technical capability
- Financial capacity
- Experience
- Equipment
- Qualified personnel
- Adequate working capital
- A realistic completion programme
How to Apply for a Bid Bond
Step 1: Read the tender instructions
Confirm:
- Exact amount
- Required format
- Acceptable issuer
- Beneficiary
- Validity period
- Closing date
- Whether the original or electronic bond is required
Step 2: Submit the tender documents to the intermediary
Provide the relevant pages early enough for review.
Step 3: Complete the insurer’s proposal form
Give accurate company, director and tender details.
Step 4: Provide underwriting documents
Submit all requested financial and business records.
Step 5: Review the quotation
Confirm:
- Bond amount
- Premium and levies
- Issuing insurer
- Validity period
- Collateral requirement
- Indemnity terms
Step 6: Pay through an approved channel
Keep the official payment confirmation.
Step 7: Review the issued bond
Check every detail before including it in the tender.
Step 8: Submit it exactly as instructed
Failure to submit the original, upload the correct document or include it in the required tender section may result in disqualification.
How to Apply for a Performance Bond
Step 1: Provide the award letter immediately
Do not wait until the contract-signing deadline.
Step 2: Submit the complete contract information
The insurer needs to understand the obligation being guaranteed.
Step 3: Complete financial and technical assessment
Performance Bonds require proper credit underwriting.
Step 4: Agree on collateral or security
Depending on the applicant and contract, the insurer may require:
- Cash collateral
- Bank guarantee
- Property security
- Directors’ indemnity
- Corporate indemnity
- Other acceptable security
Step 5: Pay the required premium and charges
Confirm whether pricing is:
- Annual
- For the full bond period
- Renewable
- Subject to additional charges for extensions
Step 6: Review the wording
Ensure that it matches the employer’s required format.
Step 7: Submit before the deadline
The contract may not be signed or activated until the Performance Bond is accepted.
How Much Does a Bid Bond Cost in Kenya?
There is no universal premium.
The cost may depend on:
- Bond amount
- Validity period
- Insurer
- Applicant’s financial position
- Tender type
- Previous bond experience
- Collateral
- Claims history
- Minimum insurer premium
- Applicable levies and fees
A Bid Bond premium is normally much lower than the guaranteed amount.
For example, a KSh 500,000 guarantee does not mean the applicant pays KSh 500,000 as the insurance premium.
The quotation should clearly distinguish:
- Guaranteed amount
- Insurance premium
- Levies
- Administrative charges
- Total payable
How Much Does a Performance Bond Cost?
Performance Bond pricing may depend on:
- Contract value
- Guaranteed percentage
- Contract duration
- Type of work
- Contractor’s experience
- Financial statements
- Current workload
- Project complexity
- Employer
- Collateral
- Claims history
- Bond wording
A contractor with strong financial records, adequate collateral and successful project experience may receive different terms from a new business with limited capital.
Obtain a written quotation after submitting the contract documents.
How Long Does Bond Processing Take?
A straightforward Bid Bond can sometimes be processed quickly when:
- The tender format is clear
- Documents are complete
- The applicant is already known to the insurer
- No collateral issues arise
- The insurer accepts the risk
Performance Bonds may take longer because the insurer must assess:
- Contract
- Financial capacity
- Technical experience
- Security
- Project risks
Businesses should not wait until the tender-closing or contract-signing date.
Urgency does not remove the insurer’s underwriting requirements.
Common Reasons a Bond Application Is Declined
An insurer may decline or postpone an application because of:
- Weak financial position
- Insufficient working capital
- Lack of relevant experience
- Excessive existing commitments
- Adverse claims history
- Incomplete documents
- Unclear contract terms
- High-risk project
- Unacceptable bond wording
- Inadequate collateral
- Unrealistic project schedule
- Previous contractual defaults
- Concerns about the employer or beneficiary
A declined insurance application does not necessarily mean the business cannot obtain a bond elsewhere, but every insurer will conduct its own assessment.
Common Tender Bond Mistakes
Using the wrong beneficiary
The beneficiary’s name must match the tender document exactly.
Providing the wrong amount
Even a small difference may make the tender non-responsive.
Using an incorrect validity period
The bond must remain valid for the required period.
Submitting the wrong format
A general guarantee may not satisfy a prescribed tender format.
Using an unaccepted insurer
Check both the PPRA list and the tender conditions.
Altering the bond after issuance
Do not edit dates, amounts or wording using PDF software.
Submitting a copy where an original is required
Follow the tender’s submission instructions.
Applying too late
The insurer may be unable to complete underwriting before the deadline.
Confusing the Bid Bond with the Performance Bond
They apply at different procurement stages.
Assuming the tender award guarantees Performance Bond approval
The insurer must still assess the contract and contractor.
How to Verify a Bid Bond
A procuring entity may contact the issuing insurer to verify:
- Bond number
- Applicant
- Beneficiary
- Amount
- Validity period
- Authenticity
- Issuing branch or office
Applicants should therefore:
- Use a licensed intermediary
- Pay through approved channels
- Obtain an insurer-issued receipt
- Avoid edited or unofficial documents
- Confirm that the bond is entered in the insurer’s system
- Keep the intermediary and insurer contacts available
A false bond can lead to disqualification and serious legal or procurement consequences.
Can a Bond Be Extended?
Yes, subject to the insurer’s approval.
A Bid Bond may require extension where:
- Tender evaluation takes longer
- The procuring entity extends bid validity
- Contract award is delayed
A Performance Bond may require extension where:
- The project period is extended
- Completion is delayed
- The defects period continues
- The employer requires additional validity
The applicant should provide the extension request before the existing bond expires.
The insurer may require:
- Written beneficiary request
- Updated contract programme
- Current project status
- Additional premium
- Revised indemnity or collateral
An extension is not automatic.
How Is a Performance Bond Released?
The contractor should obtain formal release after fulfilling the secured obligations.
Release may require:
- Completion certificate
- Taking-over certificate
- Beneficiary’s discharge letter
- Final acceptance
- Confirmation that defects obligations have ended
- Return of the original bond
- Another document specified in the contract
Do not assume that the bond automatically ends merely because the contractor has finished physical work.
Its expiry and release depend on the written guarantee and contract.
Performance Bond vs Advance Payment Bond
These guarantees serve different purposes.
Performance Bond
Guarantees performance of the contract.
Advance Payment Bond
Guarantees repayment or proper application of money advanced to the contractor before work or delivery.
If the employer pays an advance, it may require a guarantee equal to the advance amount.
A project can require both:
- Performance Bond
- Advance Payment Bond
Performance Bond vs Retention Bond
A contract may allow the contractor to replace retained funds with a Retention Bond.
Retention money
The employer keeps part of each payment until completion or the end of the defects period.
Retention Bond
The contractor receives the retained funds while the insurer or bank guarantees the corresponding obligation.
This can improve the contractor’s cash flow, subject to underwriting.
Performance Bond vs Contractors All Risks Insurance
These are not substitutes.
Performance Bond
Protects the employer against the contractor’s failure to perform.
Contractors All Risks Insurance
Protects the construction project against specified accidental physical loss, damage and third-party liabilities.
A construction contract may require:
- Performance Bond
- Contractors All Risks
- WIBA
- Public Liability
- Professional Indemnity
- Advance Payment Bond
Each addresses a different risk.
Performance Bond vs Bank Guarantee
Both can secure contractual obligations.
Insurance bond
Issued by a licensed insurer after underwriting and indemnity arrangements.
Bank guarantee
Issued by a bank and may affect the contractor’s credit facilities or require cash collateral.
The better option depends on:
- Tender requirements
- Cost
- Available collateral
- Credit facilities
- Processing time
- Contract duration
- Applicant’s financial position
The tenderer must use a format and issuer accepted by the procuring entity.
How Contractors Can Improve Their Chances of Approval
Maintain proper financial records
Prepare:
- Audited accounts
- Management accounts
- Bank statements
- Tax records
- Cash-flow projections
Build contract experience
Keep evidence of:
- Completed contracts
- Completion certificates
- Recommendation letters
- Current project status
Avoid overcommitting
The insurer will consider all ongoing contracts and existing guarantees.
Maintain adequate working capital
A bond does not finance the project.
The contractor must still fund:
- Materials
- Labour
- Equipment
- Transport
- Site expenses
Keep company records current
Update:
- CR12
- Tax compliance
- Business permits
- Contractor registration
- Directors’ details
Apply early
Early application provides time to correct missing information and negotiate collateral.
How Imana Helps Businesses Arrange Insurance Bonds
Imana Insurance Agency Kenya Ltd helps contractors, suppliers, consultants and SMEs obtain quotations for Bid Bonds and Performance Bonds from suitable licensed insurers.
The process may include:
- Reviewing the tender or contract requirements.
- Confirming the required bond type.
- Checking the amount, format and validity period.
- Collecting company and financial documents.
- Submitting the application for underwriting.
- Comparing available insurer terms.
- Explaining premiums, collateral and indemnities.
- Coordinating bond execution.
- Assisting with extensions and amendments.
- Guiding the applicant through release requirements.
Other guarantees may include:
- Advance Payment Bonds
- Retention Bonds
- Customs Bonds
- Immigration Bonds
- Maintenance Bonds
- Other contract guarantees
Imana does not award tenders or guarantee insurer approval. The procuring entity makes the procurement decision, while the insurer determines whether it can issue the requested guarantee.
Bid Bonds and Performance Bonds in Nairobi and Across Kenya
Imana Insurance Agency Kenya Ltd
4th Floor, Krishna Centre
Woodvale Grove, Westlands
Nairobi, Kenya
Website: www.imana.co.ke
Call or WhatsApp: +254 796 209 402
Read the tender. Confirm the bond requirement. Apply early. Let Imana coordinate the insurance process.
Frequently Asked Questions
What is a Bid Bond?
A Bid Bond is a guarantee submitted with a tender to secure the bidder’s obligations during the procurement process.
Is a Bid Bond the same as Tender Security?
Yes. The terms are often used interchangeably.
What is a Performance Bond?
It is a guarantee provided by a successful bidder to secure proper performance of the awarded contract.
When is a Bid Bond submitted?
It is normally included with the tender before the closing deadline.
When is a Performance Bond submitted?
It is normally submitted after award and before contract signing or commencement, as directed by the tender.
How much is a Performance Bond?
For public procurement, the Act provides for Performance Security of not more than 10% of the contract amount, subject to applicable exemptions, regulations and tender requirements. (Kenya Law)
Can an insurance company issue a Bid Bond?
Yes. The procurement regulations recognise guarantees from licensed insurers listed by PPRA, subject to the tender conditions. (Kenya Law)
Does every insurer issue bonds?
No. The insurer must offer the product, accept the applicant and satisfy the procuring entity’s requirements.
Must I pay the full bond amount?
Not ordinarily. The applicant normally pays a premium and may provide collateral. The insurer guarantees the stated bond amount.
Will the insurer recover money from me after paying a claim?
Potentially, yes. Guarantee bonds normally include indemnity obligations allowing the insurer to seek reimbursement from the contractor after paying a valid demand.
Can a Bid Bond be extended?
Yes, subject to insurer approval and payment of any additional premium.
Can a Performance Bond be cancelled before the contract ends?
Usually only after the beneficiary formally releases the guarantee or the bond expires according to its terms.
Does obtaining a Bid Bond mean the tender will be awarded?
No. It only satisfies one tender requirement. The procuring entity evaluates the complete bid.
Does winning a tender guarantee Performance Bond approval?
No. The insurer must assess the contract, financial capacity, experience and security.
Can Imana arrange Bid and Performance Bond quotations?
Yes. Imana can coordinate applications through suitable licensed insurers, subject to underwriting approval.
The Bottom Line
Bid Bonds and Performance Bonds play different roles in procurement.
A Bid Bond:
- Is submitted with the tender
- Protects the procurement process
- Shows that the bidder intends to honour the bid
- May be called where the bidder breaches specified tender obligations
A Performance Bond:
- Is submitted after contract award
- Protects the employer during contract execution
- Guarantees the contractor’s performance
- May be called where the contractor defaults under the guaranteed terms
Before applying:
- Read the tender carefully.
- Confirm the exact bond type.
- Use the prescribed format.
- Check the amount and validity.
- Apply through a licensed provider.
- Submit complete financial documents.
- Understand collateral requirements.
- Review the indemnity before signing.
- Never alter an issued bond.
- Obtain formal release after the obligation ends.
A bond can help you qualify for a tender, but it does not finance the project or excuse poor performance. Bid responsibly, price accurately and accept only contracts you can deliver.
Imana Insurance Agency Kenya Ltd
Call or WhatsApp: +254 796 209 402
Website: www.imana.co.ke
Secure the tender. Protect the contract. Deliver as promised.
Bond premiums, collateral, validity periods, underwriting requirements and guarantee wording vary by insurer, beneficiary and contract. Procurement rules and approved-provider lists may change. Applicants should review the current tender documents, PPRA requirements, insurer terms and legal obligations before submitting a bond.