
Blog Details
Diskava. Beta. Kava
29Jul
Top 15 Affordable Medical Insurance Covers in Kenya 2026 and Beyond
Compare 15 affordable medical insurance options in Kenya for individuals, children, families, SMEs and senior citizens. Understand premiums, benefits, waiting periods and hospital access before buying.
Finding Affordable Medical Insurance in Kenya
Finding affordable medical insurance in Kenya does not mean choosing the cheapest policy and hoping for the best.
The lowest-priced medical cover may have a small inpatient limit, restricted hospital network, benefit sublimits, co-payments or long waiting periods. A more expensive plan may provide broader benefits, but it can also include features that your family does not necessarily need.
The right approach is to compare:
- Premiums
- Inpatient and outpatient limits
- Maternity benefits
- Waiting periods
- Chronic and pre-existing condition benefits
- Hospital networks
- Dental and optical limits
- Co-payments
- Claims and pre-authorisation procedures
- Entry and renewal ages
The following is an editorial shortlist of 15 medical insurance options and comparison channels to consider in 2026. It is not an official ranking of insurers. Premiums and benefits may change depending on age, family size, health information, underwriting terms and the selected level of cover.
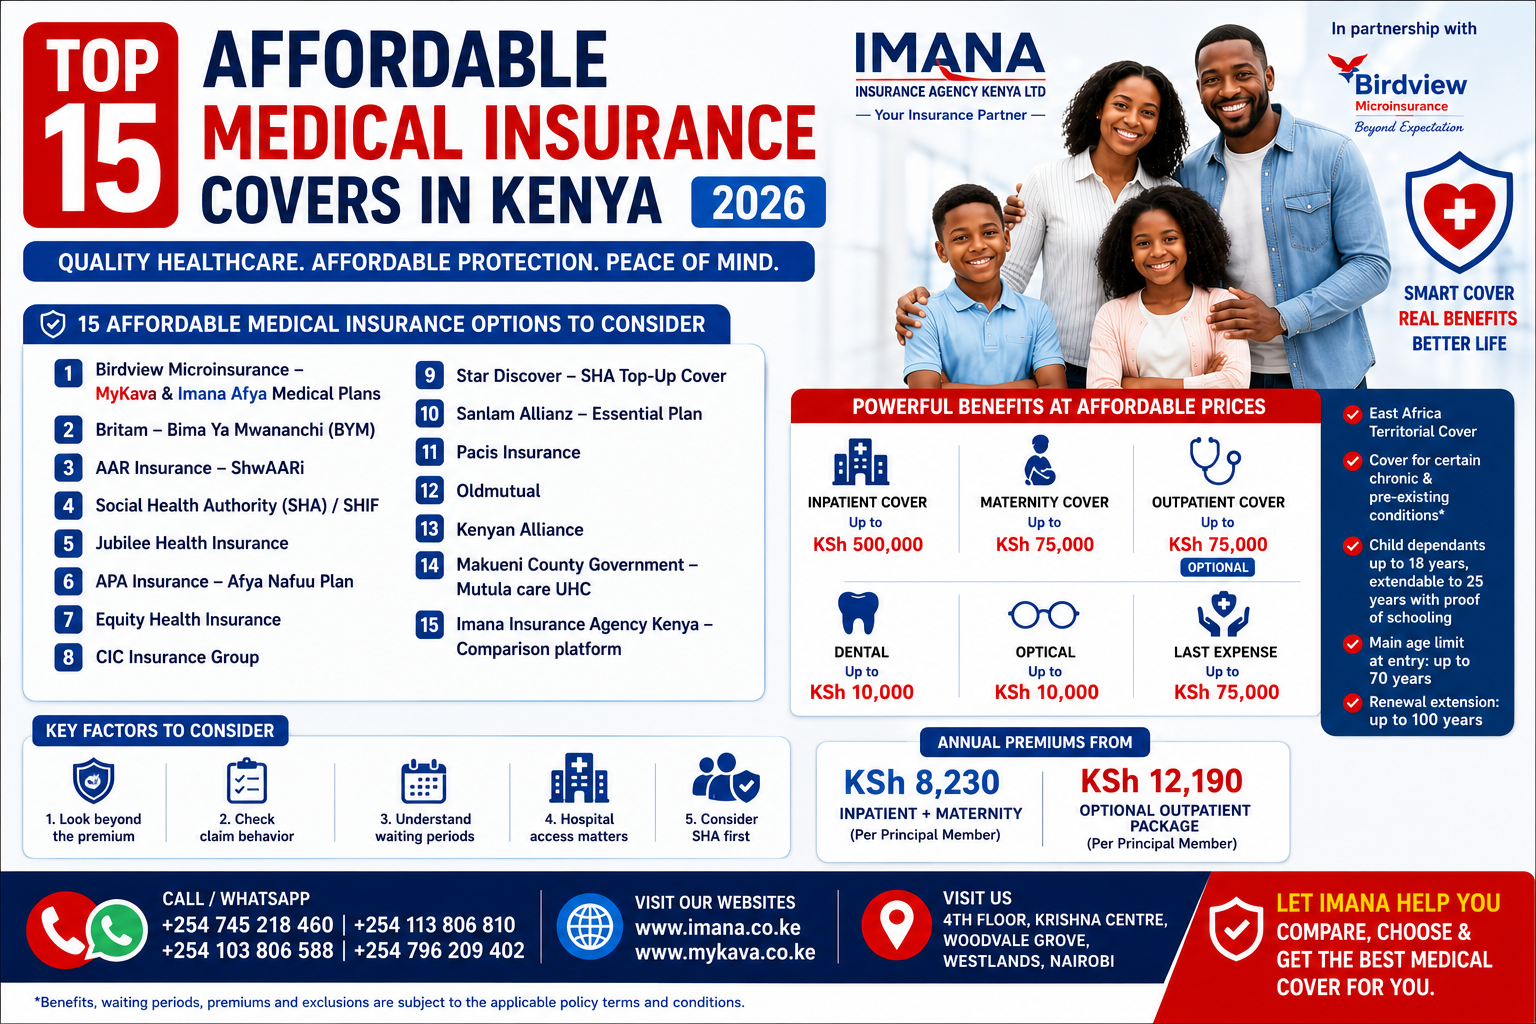
1. Birdview Microinsurance: MyKava and Imana Afya Medical Plans
Birdview Microinsurance supports two affordable medical options distributed through Imana Insurance Agency Kenya Ltd and MyKava.
MyKava Medical Insurance
MyKava provides flexible inpatient options ranging from KSh 100,000 to KSh 750,000 per person annually.
Optional outpatient limits range from KSh 30,000 to KSh 75,000. Depending on the selected plan, benefits may include:
- Inpatient treatment
- Outpatient treatment
- Maternity
- Dental and optical care
- Road ambulance services
- Psychiatric hospitalisation
- Last-expense benefits
- Certain chronic and pre-existing conditions
- East Africa territorial coverage
The cover is suitable for individuals, children, families and organised groups. Waiting periods apply to general illness, maternity, chronic conditions and pre-existing conditions.
Imana Afya Medical Cover
Imana Afya offers:
- Inpatient cover up to KSh 500,000
- Maternity cover up to KSh 75,000
- Optional outpatient cover up to KSh 75,000
- Dental benefit up to KSh 10,000
- Optical benefit up to KSh 10,000
- Last-expense benefit up to KSh 75,000
The inpatient and maternity package has indicative annual premiums starting from KSh 8,230 for a principal member. The separately priced outpatient package starts from approximately KSh 12,190 annually, subject to the membership structure and policy conditions.
These plans may be attractive to customers looking for flexible benefit combinations rather than one fixed medical package.
2. Britam Bima Ya Mwananchi
Britam’s Bima Ya Mwananchi, commonly known as BYM, is designed for individuals and families seeking entry-level medical protection.
Published information indicates that premiums start from approximately KSh 4,600 annually, with several options available depending on the required benefits.
Before purchasing Bima Ya Mwananchi, compare:
- Whether the selected option is inpatient-only
- Whether outpatient cover is included or optional
- Hospital network
- Age eligibility
- Waiting periods
- Maternity availability
- Chronic-condition limits
- Benefit sublimits
Britam also offers other medical products for children, families, groups and older adults, so BYM should be compared against the company’s other available plans rather than considered in isolation.
3. AAR Insurance ShwAARi Medical Cover
AAR’s ShwAARi Medical Cover is structured around a single annual medical limit and offers different plans for individuals and families.
AAR describes ShwAARi as suitable for members across a wide age range, with flexible payment options starting from approximately KSh 1,600 per month, depending on the selected plan and membership.
The single-limit structure can make benefits easier to understand because different eligible treatments draw from one overall annual limit. However, customers should still confirm:
- Treatments covered under the shared limit
- Whether maternity is included
- Dental and optical benefits
- Provider network
- Chronic-condition provisions
- Co-payments
- Waiting periods
- Whether the benefit is shared by the family or allocated per member
A single limit may offer flexibility, but a major claim by one family member can also reduce the amount remaining for everyone else where the benefit is shared.
4. Social Health Authority and the Social Health Insurance Fund
The Social Health Authority provides Kenya’s statutory social health insurance framework.
Contributions are generally calculated at 2.75% of gross income, with a minimum contribution of KSh 300 per month. Non-salaried households are assessed using the applicable income and means-testing framework.
SHA should be treated as an important foundation of healthcare financing rather than ignored when purchasing private medical insurance.
Private medical plans may complement SHA by addressing eligible expenses, facilities or benefits beyond what is payable under the statutory scheme. However, a private policy may exclude costs recoverable through SHA.
Before seeking treatment, members should understand:
- Whether the facility is empanelled
- Whether a referral is required
- Applicable tariffs
- Contribution status
- Pre-authorisation procedures
- What SHA pays
- What must be paid personally or through private insurance
At the statutory minimum, SHA is one of the lowest-cost healthcare protection options available, but contributions for many households will be higher than KSh 300 because they are income-based.
5. Jubilee Health Insurance
Jubilee offers several health products for individuals, families, organised groups and businesses.
For customers prioritising affordability, two notable options are:
Cover Nafuu
Cover Nafuu is marketed as an affordable outpatient medical plan, with published premiums starting from around KSh 4,000 annually.
CoverBora
CoverBora is an inpatient-focused option with published prices beginning from approximately KSh 6,200 for individuals and KSh 11,200 for families, subject to current terms.
Customers should establish whether they need outpatient-only, inpatient-only or combined protection.
Buying a low-cost outpatient plan without inpatient protection may leave a family exposed to major hospital-admission expenses. Similarly, inpatient-only cover may not address routine consultations and prescribed medication.
6. APA Insurance Afya Nafuu
APA’s Afya Nafuu is a family medical insurance plan covering hospitalisation expenses arising from covered illnesses and accidents.
The product is designed for families and provides options across a broad range of ages. Benefits and premiums depend on the selected plan and current underwriting terms.
When comparing Afya Nafuu quotations, examine:
- Inpatient limit
- Outpatient availability
- Maternity benefits
- Chronic and pre-existing condition cover
- Age limits
- Provider network
- Waiting periods
- Family composition
- Whether benefits are shared or allocated per person
APA also provides corporate medical solutions for groups of ten or more employees, which may offer better group terms for SMEs than purchasing separate individual policies.
7. Equity Health Insurance Options
Equity Bancassurance offers medical insurance through products such as Equihealth and Equimed.
Equihealth
Equihealth targets individuals who belong to registered groups. The published eligibility requirement is membership in a group of at least ten people. Members can arrange cover for themselves and their families.
Equimed
Equimed is positioned as a comprehensive inpatient and outpatient plan for:
- Individuals
- Families
- Groups
- Small businesses
It may suit customers who prefer arranging medical insurance through Equity’s branch and bancassurance network.
Customers should remember that Equity Afia clinics and Equity medical insurance products are not the same thing. One is a healthcare-provider network, while the other concerns insurance arrangements.
8. CIC Insurance Group Medical Plans
CIC provides several medical options for families, cooperatives, senior citizens and corporate organisations.
One of its budget-oriented products is Afya Bora.
Published product information describes a family plan covering up to six members, with:
- Inpatient limit of KSh 250,000
- Outpatient limit of KSh 50,000
- Indicative family premium of approximately KSh 32,000 annually
Eligibility and final pricing remain subject to the current policy terms.
CIC also offers Family Medisure, CoopCare, corporte medical insurance and specialist senior-citizen plans. Family Medisure provides a broader selection of limits, while CoopCare provides group medical terms for qualifying cooperative members.
Afya Bora may be affordable for a family, but customers should decide whether the KSh 250,000 inpatient limit is adequate for a serious hospital admission.
9. Star Discover SHA Top-Up Cover
Star Discover promotes medical solutions intended to complement SHA and help customers manage eligible healthcare expenses beyond the statutory benefit.
However, detailed public information on current premiums, hospital networks, limits and sublimits is limited. Prospective customers should request a written quotation, benefit schedule and complete policy wording before paying.
Important questions include:
- Which SHA shortfalls are covered?
- Is the plan inpatient-only or comprehensive?
- Does the member need active SHA status?
- Which hospitals are available?
- Is there a co-payment?
- Are maternity and chronic conditions included?
- Are benefits paid directly or through reimbursement?
- What happens when SHA rejects or limits a claim?
The words “SHA top-up” should not be interpreted as unlimited payment of every cost not covered by SHA.
10. Sanlam Allianz Medical Insurance Options
Sanlam and Allianz completed a significant consolidation of their African insurance operations, and entry-level medical options may be distributed under the combined brand.
Some market publications refer to a Sanlam Allianz Essential Plan targeting budget-conscious customers and first-time medical insurance buyers. However, detailed official public information on the Kenyan plan’s current premiums and benefits was not sufficiently clear during our review.
Anyone considering this option should ask for:
- Current product name
- Confirmation that it is available in Kenya
- Inpatient and outpatient limits
- Hospital network
- Family eligibility
- Waiting periods
- Maternity benefits
- Chronic and pre-existing condition terms
- Current premium schedule
No medical plan should be selected from an online list without a current insurer-issued quotation and benefit schedule.
11. Pacis Amani Medical Cover
Pacis Amani Medical is intended for individuals and families seeking flexible medical insurance.
Its benefits may include:
- Inpatient hospitalisation
- Optional outpatient care
- Optional maternity
- Dental and optical benefits
- Accident cover
- Chronic conditions
- Pre-existing conditions
- Congenital conditions
Pacis states that outpatient benefits cannot be purchased independently from inpatient cover. Maternity, surgical and illness-related waiting periods also apply.
The plan may be worth considering for customers who want the ability to add benefits gradually. Before buying, confirm the entry age, medical-examination requirements, provider restrictions and treatment available outside the approved hospital panel.
12. Old Mutual AfyaImara
Old Mutual offers several AfyaImara medical insurance options.
The principal family cover may include:
- Day-care procedures
- Inpatient hospitalisation
- Outpatient treatment
- Maternity
- Dental benefits
- Optical benefits
Old Mutual also offers child-focused, senior-citizen and county-oriented versions of the AfyaImara plan.
The range can be helpful because customers are not forced into one universal family structure.
A family with young children may need different benefits from a household insuring parents aged above 65. Compare the relevant AfyaImara version rather than assuming the standard family policy will suit every member.
13. Kenyan Alliance KAI Family Health Insurance
Kenyan Alliance offers KAI Family Health Insurance, designed to complement SHA.
The policy provides flexible benefit structures, including:
- Inpatient cover
- Inbuilt maternity benefits
- Personal accident benefits
- Last expense
- Outpatient treatment
- Dental care
- Optical care
- Chronic-disease management support
Clients may choose between family-shared and per-person benefit structures, depending on the available plan.
A shared family limit can be more affordable, but one large claim may use a substantial portion of the available benefit. Per-person limits normally provide clearer protection for each member but may cost more.
14. Makueni County MutulaCare UHC Programme
MutulaCare is different from an ordinary commercial medical insurance policy.
It is a Makueni County universal healthcare initiative targeting vulnerable and indigent households. The county pays qualifying households’ SHA contributions and supports their access to healthcare under the statutory framework.
Benefits described by the county include access to:
- Inpatient treatment
- Outpatient services
- Dental and optical care
- Chronic-disease management
- Emergency treatment
- Ambulance evacuation
Eligibility is limited to qualifying residents of Makueni County and is based on vulnerability assessment. It is therefore not a plan that any person in Kenya can simply purchase.
Makueni residents should check current registration exercises and eligibility requirements through official county channels.
15. Imana Insurance Agency Kenya Medical Comparison Service
Imana Insurance Agency Kenya Ltd is not a medical insurer. It is an insurance intermediary that helps customers compare medical insurance quotations from different providers.
Instead of approaching only one insurer, a customer can use Imana to compare:
- Premiums
- Inpatient limits
- Outpatient limits
- Maternity cover
- Dental and optical benefits
- Hospital networks
- Waiting periods
- Chronic-condition benefits
- Family-shared versus per-person limits
- Senior-citizen options
- Child-only options
- SHA supplementary cover
- Corporate and SME schemes
The comparison service is relevant to:
- Individuals
- Families
- Parents seeking child-only cover
- Senior citizens
- SMEs
- Employers
- Chamas
- Associations
- Corporate organisations
Imana serves customers from Westlands, Nairobi, and through digital quotation channels across Kenya.
Important Factors When Choosing Affordable Medical Cover
1. Look Beyond the Premium
A low premium may come with:
- Restricted hospitals
- Small benefit limits
- High co-payments
- Strict pre-authorisation procedures
- Limited medicine cover
- Long waiting periods
- Low maternity sublimits
- Shared family benefits
- Treatment-specific limits
Ask for the full benefit schedule, not just the price.
2. Understand the Claims and Pre-Authorisation Process
Rather than relying on rumours about whether an insurer “pays claims,” ask practical questions:
- How are planned admissions authorised?
- Is approval available outside working hours?
- How long does routine pre-authorisation normally take?
- Who should the hospital contact?
- What documents are required?
- How are reimbursements handled?
- Is treatment outside the panel covered?
- Is there an emergency hotline?
Claims experience often depends on policy conditions, hospital processes, documentation and whether the treatment is covered.
3. Check Waiting Periods
Waiting periods commonly apply to:
- General illness
- Maternity
- Pregnancy complications
- Surgery
- Chronic illnesses
- Pre-existing conditions
- Certain specialised treatments
Buying medical insurance after treatment is already required may be too late.
4. Examine Hospital Access Carefully
A hospital appearing on a provider list does not automatically mean every service at that hospital is fully covered.
Confirm:
- Whether inpatient and outpatient services are both available
- Whether the facility is available under your specific plan
- Applicable co-payments
- Whether specialists require referral
- Whether medicines are covered
- Whether limits apply to diagnostic tests
- Whether pre-authorisation is required
Hospital networks can also change during the insurance period.
5. Start With SHA, Then Assess the Gaps
SHA provides the statutory healthcare foundation for Kenyan residents.
Before purchasing private insurance, understand what SHA provides and identify the gaps that matter to you. A private policy or SHA top-up can then be selected to address eligible additional needs.
Avoid paying for duplicated benefits without understanding which scheme pays first.
6. Compare Family-Shared and Per-Person Benefits
Under a family-shared plan, all members use one common benefit.
Under a per-person plan, each insured member receives a separate annual limit.
Shared benefits may cost less, while per-person benefits may provide stronger protection where several family members require treatment in the same year.
7. Disclose Medical Information Honestly
Where the proposal form asks about existing conditions, medication, surgery or previous claims, provide accurate answers.
Non-disclosure can lead to:
- Delayed treatment authorisation
- Claim rejection
- Policy cancellation
- Disputes over pre-existing conditions
A lower premium obtained through incomplete disclosure is not a genuine saving.
Let Imana Help You Compare Medical Insurance Quotes
Choosing medical insurance can feel overwhelming because insurers package their benefits differently.
One company may offer a low annual premium with a restricted provider panel. Another may provide a wider hospital network but impose co-payments. A third may offer attractive inpatient benefits but limited outpatient, maternity or chronic-condition cover.
Imana Insurance Agency Kenya Ltd helps customers:
- Identify suitable medical plans
- Compare quotations from different insurers
- Understand benefits and exclusions
- Review hospital networks
- Examine waiting periods
- Compare family and individual structures
- Arrange child-only and senior medical options
- Review SHA supplementary solutions
- Obtain SME and corporate quotations
- Complete onboarding documentation
Imana is located at:
4th Floor, Krishna Centre, Woodvale Grove, Westlands, Nairobi
Call or WhatsApp: +254 796 209 402
Imana serves customers in Westlands, Nairobi and throughout Kenya through online quotation and digital support channels.
Affordable medical insurance is not simply the policy with the lowest premium. It is the cover that gives you the best practical protection within a budget you can sustain.
Frequently Asked Questions
What is the cheapest medical insurance in Kenya?
SHA has a statutory minimum contribution of KSh 300 per month, although most contributions depend on income. Private entry-level plans may begin from approximately KSh 4,000 annually, depending on age, benefits and eligibility.
Can I buy medical insurance for my child only?
Yes. Child-only options are available from selected providers, including MyKava and specialist children’s plans offered by other insurers. Entry age, waiting periods and dependant rules vary.
Can I get medical insurance for my parents?
Yes. Several insurers offer senior-citizen plans, but entry ages, chronic-condition benefits, medical assessments and premiums differ considerably.
Does affordable medical insurance cover maternity?
Some plans include maternity, while others offer it as an optional benefit. Maternity normally has a waiting period, commonly around ten to twelve months.
Are pre-existing conditions covered?
Some medical plans cover defined pre-existing and chronic conditions after a waiting period and within a sublimit. Other policies may exclude them entirely.
Can private medical insurance replace SHA?
Private insurance generally complements rather than automatically replaces the statutory SHA framework. Check the policy’s coordination-of-benefits conditions.
Can Imana compare quotations from several insurers?
Yes. Subject to insurer appetite and product availability, Imana can help clients compare medical insurance options from different trusted providers.
Prices and benefits referenced in this article are indicative and based on publicly available information reviewed in July 2026 or product presentations supplied to Imana. Final premiums, eligibility, waiting periods, provider access and claims remain subject to current insurer quotations, underwriting requirements and full policy wording.